



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models459 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes420 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care337 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance512 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs326 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets256 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income260 Questions
Exam 20: Unemployment and Inflation290 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles251 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies261 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run305 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money, Banks, and the Federal Reserve System278 Questions
Exam 26: Monetary Policy280 Questions
Exam 27: Fiscal Policy313 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy277 Questions
Exam 30: The International Financial System258 Questions
Select questions type


A downward sloping marginal product of labor curve demonstrates the law of diminishing marginal returns.
(True/False)
4.7/5  (79)
(79) State the law of diminishing returns. How do diminishing returns differ from diseconomies of scale? Be sure to define diseconomies of scale in your answer.
(Essay)
4.9/5 (91)
(91) Sally quit her job as an auto mechanic earning $50,000 per year to start her own business. To save money she operates her business out of a small building she owns which, until she started her own business, she had rented out for $10,000 per year. She also invested her $20,000 savings (which earned a market interest rate of 5% per year) in her business. You are given the following information about the first year of her operations.
Total revenue $120,000
Cost of labor 40,000
Cost of materials 15,000
Equipment rental 5,000
a. Calculate her economic costs for the first year.
b. Calculate her accounting costs for the first year.
c. Calculate her implicit costs for the first year.
d. Sally tells you that she would really like to move to a location closer to town but she decided against it because "right now I don't pay any rent and it will cost me $10,000 a year to rent near town." Do you agree with her reasoning?
(Essay)
4.8/5 (80)
(80) The difference between technology and technological change is that
(Multiple Choice)
4.9/5 (86)
(86) If another worker adds 9 units of output to a group of workers who had an average product of 7 units, then the average product of labor
(Multiple Choice)
4.7/5 (81)
(81) Figure 11-6  Figure 11-6 contains information about the short run cost structure of a firm.
-Refer to Figure 11-6. In the figure above, which letter represents the average total cost curve?
Figure 11-6 contains information about the short run cost structure of a firm.
-Refer to Figure 11-6. In the figure above, which letter represents the average total cost curve? (Multiple Choice)
4.8/5 (80)
(80) Table 11-7
 Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7. What is the average variable cost per unit of production when the firm produces 90 lanterns?
Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7. What is the average variable cost per unit of production when the firm produces 90 lanterns? (Multiple Choice)
5.0/5 (77)
(77) In the short run, if average product is at its maximum, then average variable cost is at its minimum.
(True/False)
4.9/5 (75)
(75) The president of Toyota's Georgetown plant was quoted as saying, "Demand for high volumes saps your energy. Over a period of time, it eroded our focus [and] thinned out the expertise and knowledge we painstakingly built up over the years." This quote suggests that
(Multiple Choice)
5.0/5 (81)
(81) If the average variable cost curve is above the marginal cost curve, then
(Multiple Choice)
4.8/5 (79)
(79) Figure 11-4 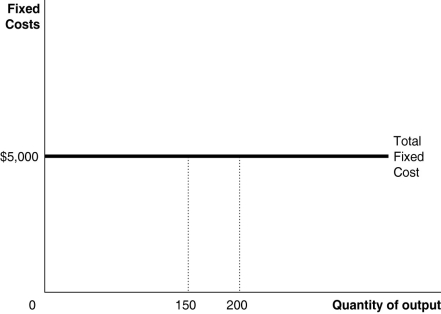 -Refer to Figure 11-4. What happens to the average fixed cost of production when the firm increases output from 150 to 200?
 (Multiple Choice)
4.7/5 (82)
(82) Table 11-3
 -Refer to Table 11-3. The table above refers to the relationship between the quantity of workers employed and the number of cardboard boxes produced per day by Manny's House of Boxes. The capital used to produce the boxes is fixed. The average product of labor will equal 66 boxes when Manny hires
 (Multiple Choice)
4.7/5 (87)
(87) If production displays economies of scale, the long-run average cost curve is
(Multiple Choice)
4.9/5 (83)
(83) Which of the following is an example of positive technological change?
(Multiple Choice)
4.8/5 (78)
(78) In economics, technology only refers to the development of new products.
(True/False)
4.9/5 (69)
(69) If the marginal cost curve is below the average variable cost curve, then
(Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)