



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models459 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes420 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care337 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance512 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs326 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets256 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income260 Questions
Exam 20: Unemployment and Inflation290 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles251 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies261 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run305 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money, Banks, and the Federal Reserve System278 Questions
Exam 26: Monetary Policy280 Questions
Exam 27: Fiscal Policy313 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy277 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Academic book publishers hire editors, designers, and production and marketing managers who help prepare books for publication. Because these employees work on several books simultaneously, the number of people the company hires will not go up and down with the quantity of books the company publishes during any particular year. The salaries and benefits of people in these job categories will be included in
(Multiple Choice)
4.7/5  (73)
(73) When a firm produces 50,000 units of output, its total cost equals $6.5 million. When it increases its production to 70,000 units of output, its total cost increases to $9.4 million. Within this range, the marginal cost of an additional unit of output is
(Multiple Choice)
4.7/5 (83)
(83) If a firm is producing no output in the short run, then its total costs are zero.
(True/False)
4.9/5 (84)
(84) The processes a firm uses to turn inputs into outputs of goods and services is called
(Multiple Choice)
4.9/5 (88)
(88) Figure 11-14 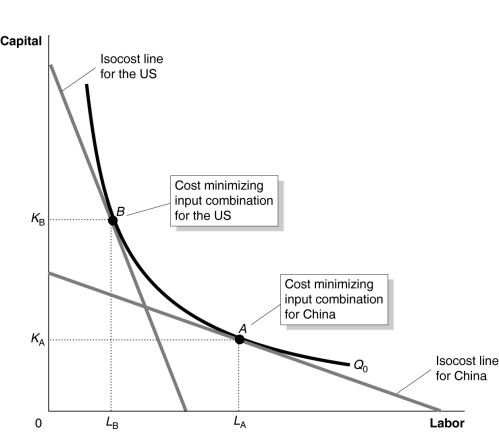 Figure 11-14 shows the optimal input combinations for the production of a given quantity of cotton in the United States and in China.
-Refer to Figure 11-14. Which of the following could explain why the United States and China use different input combinations to produce a given quantity of cotton and yet, each country produces that quantity at the lowest possible cost?
Figure 11-14 shows the optimal input combinations for the production of a given quantity of cotton in the United States and in China.
-Refer to Figure 11-14. Which of the following could explain why the United States and China use different input combinations to produce a given quantity of cotton and yet, each country produces that quantity at the lowest possible cost? (Multiple Choice)
4.9/5 (77)
(77) Figure 11-2  -Refer to Figure 11-2. The average product of labor declines after L2 because
 (Multiple Choice)
4.9/5 (90)
(90) Describe the difference between technology and positive technological change.
(Essay)
4.8/5 (69)
(69) Explain why the marginal cost of production must increase if the marginal product of a variable resource is decreasing.
(Essay)
4.8/5 (77)
(77) Figure 11-13  -Refer to Figure 11-13. The lines shown in the diagram are isocost lines. If the price of labor is $50 per unit, then along the isocost AF, the total cost
 (Multiple Choice)
5.0/5 (94)
(94) Suppose you have just opened a store to sell espresso machines. Both you and a competing store buy this machine from a manufacturer for $130 each. Your competitor ,who has a store of the same size as yours, is currently selling about 10 machines a month at a price of $200 per machine. You expect to sell about 6 machines a month at a price of $220 per machine. If you lower your price, you expect to make a loss. Which of the following could explain why your competitor is able to profitably sell the machine at a lower price although the cost of purchasing the machine is the same for the both of you?
(Multiple Choice)
4.9/5 (88)
(88) Figure 11-17  -Refer to Figure 11-17. Assume that production isoquants are convex. Total cost and output produced must increase for each of the following movements except one. Which movement is the exception?
 (Multiple Choice)
4.8/5 (68)
(68) Figure 11-13
-Refer to Figure 11-13. The lines shown in the diagram are isocost lines. Which of the following shows a decrease in the price of capital while the price of labor remains unchanged?
-Refer to Figure 11-13. The lines shown in the diagram are isocost lines. Which of the following shows a decrease in the price of capital while the price of labor remains unchanged? (Multiple Choice)
4.9/5 (75)
(75) Figure 11-6  Figure 11-6 contains information about the short run cost structure of a firm.
-Refer to Figure 11-6. In the figure above, which letter represents the average variable cost curve?
Figure 11-6 contains information about the short run cost structure of a firm.
-Refer to Figure 11-6. In the figure above, which letter represents the average variable cost curve? (Multiple Choice)
4.9/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)