



 Chat with AI
Exam 29: International Trade

Exam 1: The Central Idea156 Questions
Exam 2: Observing and Explaining the Economy143 Questions
Exam 3: The Supply and Demand Model166 Questions
Exam 4: Subtleties of the Supply and Demand Model176 Questions
Exam 5: The Demand Curve and the Behavior of Consumers176 Questions
Exam 6: The Supply Curve and the Behavior of Firms179 Questions
Exam 7: The Efficiency of Markets163 Questions
Exam 8: Costs and the Changes at Firms Over Time191 Questions
Exam 9: The Rise and Fall of Industries139 Questions
Exam 10: Monopoly184 Questions
Exam 11: Product Differentiation, Monopolistic Competition, and Oligopoly169 Questions
Exam 12: Antitrust Policy and Regulation152 Questions
Exam 13: Labor Markets179 Questions
Exam 14: Taxes, Transfers, and Income Distribution179 Questions
Exam 15: Public Goods, Externalities, and Government Behavior197 Questions
Exam 16: Capital and Financial Markets188 Questions
Exam 17: Macroeconomics: the Big Picture159 Questions
Exam 18: Measuring the Production, Income, and Spending of Nations177 Questions
Exam 19: The Spending Allocation Model166 Questions
Exam 20: Unemployment and Employment212 Questions
Exam 21: Productivity and Economic Growth162 Questions
Exam 22: Money and Inflation153 Questions
Exam 23: The Nature and Causes of Economic Fluctuations185 Questions
Exam 24: The Economic Fluctuations Model205 Questions
Exam 25: Using the Economic Fluctuations Model176 Questions
Exam 26: Fiscal Policy138 Questions
Exam 27: Monetary Policy180 Questions
Exam 28: Economic Growth Around the World157 Questions
Exam 29: International Trade242 Questions
Exam 30: International Finance125 Questions
Select questions type


Graphically illustrate how a tariff, quota, and VRA can all result in the same quantity of imports and the same equilibrium price.
(Essay)
4.9/5  (91)
(91) The following relationship between price, average total cost, and the number of firms describes an industry in a single country. 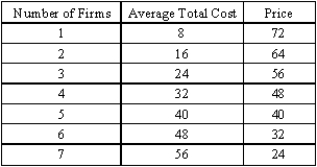
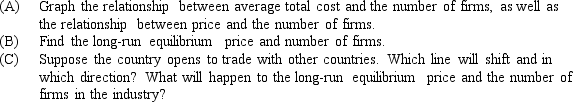
(Essay)
4.9/5 (82)
(82) Exhibit 30-1  -Refer to Exhibit 30-1. If the importing country imposes a tariff of $2 per unit, the new equilibrium price will be
 (Multiple Choice)
4.8/5 (79)
(79) Explain the connection between opportunity costs of production and complete specialization in the production of a good.
(Essay)
4.8/5 (86)
(86) Creating regional trading areas is an increasingly popular approach to reducing trade barriers.
(True/False)
4.7/5 (81)
(81) Exhibit 30-2  -Refer to the data in Exhibit 30-2. If the importing country sets a quota of 10 units, imports will be
 (Multiple Choice)
4.8/5 (72)
(72) If the world price of a good is lower than the no-trade equilibrium price for a particular country, the country will export the good.
(True/False)
4.9/5 (77)
(77) Workers in countries with higher productivity will be paid more than workers with lower productivity, even in countries that trade.
(True/False)
4.9/5 (89)
(89) Trade between countries in goods from different industries is called
(Multiple Choice)
4.8/5 (90)
(90) International trade as a share of world GDP has doubled in the last 40 years.
(True/False)
4.9/5 (75)
(75) The tariff that was passed in 1828 that brought the average tariff level in the United States to over 60 percent came to be known as
(Multiple Choice)
4.7/5 (89)
(89) Why has international trade grown more rapidly over the past 30 years?
(Essay)
4.9/5 (93)
(93) Exhibit 29-2  -Suppose the relative price of computers and rice in Japan is 2 computers per unit of rice. The relative price of computers and rice in Korea is 1/2 computer per unit of rice. If the two countries trade without government restrictions, transportation costs are negligible, and markets are competitive, then the likely terms of trade will fall in the range of
 (Multiple Choice)
4.8/5 (76)
(76) Which of the following statements about trade restrictions is true?
(Multiple Choice)
4.9/5 (75)
(75) Explain the connection between opportunity costs of production and the shape of the production possibilities curve.
(Essay)
4.7/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)