



 Chat with AI
Exam 19: Information for Decisions: Relevant Costs and Benefits

Exam 1: Management Accounting: Information for Creating Value and Managing Resources67 Questions
Exam 2: Management Accounting: Cost Terms and Concepts87 Questions
Exam 3: Cost Behaviour, Cost Drivers and Cost Estimation93 Questions
Exam 4: Product Costing Systems88 Questions
Exam 5: Process Costing and Operation Costing87 Questions
Exam 6: Service Costing91 Questions
Exam 7: A Closer Look at Overhead Costs99 Questions
Exam 8: Activity-Based Costing91 Questions
Exam 9: Budgeting Systems92 Questions
Exam 10: Standard Costs for Control: Direct Material and Direct Labour105 Questions
Exam 11: Standard Costs for Control: Flexible Budgets and Manufacturing Overhead109 Questions
Exam 12: Managing and Reporting Performance102 Questions
Exam 13: Financial Performance Measures and Incentive Schemes93 Questions
Exam 14: Strategic Performance Measurement Systems80 Questions
Exam 15: Managing Suppliers and Customers90 Questions
Exam 16: Managing Costs and Quality92 Questions
Exam 17: Sustainability and Management Accounting76 Questions
Exam 18: Cost Volume Profit Analysis111 Questions
Exam 19: Information for Decisions: Relevant Costs and Benefits116 Questions
Exam 20: Pricing and Product Mix Decisions113 Questions
Exam 21: Information for Capital Expenditure Decisions125 Questions
Select questions type


When making the decision of whether to process further a joint product, it is generally better to allocate the joint costs using the relative sales value method to ensure the correct decision is made.
(True/False)
5.0/5  (77)
(77) A firm produces three items from a single process in batches containing 40 units A (a by-product); 100 units B; 100 units C. Separable costs and selling prices are:
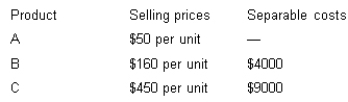 Joint process costs are $30 000 per batch.
What is the amount of joint costs that would be allocated to B using the net realisable value method and treats by-product revenue as a reduction of the cost of the principal products?
Joint process costs are $30 000 per batch.
What is the amount of joint costs that would be allocated to B using the net realisable value method and treats by-product revenue as a reduction of the cost of the principal products? (Multiple Choice)
4.8/5 (73)
(73) A joint product with very little value relative to other joint products is termed a:
(Multiple Choice)
4.9/5 (88)
(88) Sound Systems reported the following results from the sale of 24 000 radios:
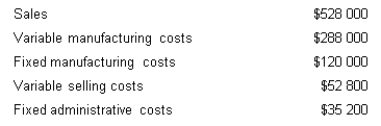 Sound Systems expects similar operating results during the current year. Rhythm Systems has offered to purchase 3000 radios at $16 each. Sound Systems estimates approximately 5000 additional units could be made with the capacity currently available in the factory. The owner of Sound Systems is in favour of accepting the order. She feels it would be profitable because no variable selling costs will be incurred. The plant manager is against acceptance because his 'full cost' of production is $17.
Determine the change in profit if the special order is accepted.
Sound Systems expects similar operating results during the current year. Rhythm Systems has offered to purchase 3000 radios at $16 each. Sound Systems estimates approximately 5000 additional units could be made with the capacity currently available in the factory. The owner of Sound Systems is in favour of accepting the order. She feels it would be profitable because no variable selling costs will be incurred. The plant manager is against acceptance because his 'full cost' of production is $17.
Determine the change in profit if the special order is accepted. (Multiple Choice)
4.8/5 (88)
(88) Lido Products produces two products (A and B) from a joint process. The joint cost of production is $80 000. Five thousand units of Product A can be sold at split-off for $20 per unit or processed further at an additional cost of $20 000 and sold for $25 per unit. Ten thousand units of Product B can be sold at split-off for $15 per unit or processed further at an additional cost of $20 000 and sold for $16 per unit.
What is the difference in profit if Lido decides to process further Product A, instead of selling it at split-off?
(Multiple Choice)
4.8/5 (94)
(94) Which of the following is least likely to be classified as a tactical decision?
(Multiple Choice)
4.8/5 (71)
(71) When making decisions, the quantitative information considered consists of factors relevant to the decision that cannot be expressed effectively in numerical terms.
(True/False)
4.8/5 (81)
(81) Xebex Pty Ltd is considering whether to make or buy a component used in the production of Faz Machines. The annual cost of producing the 100 000 components used by the company is as follows. 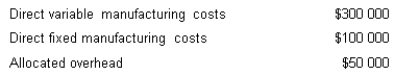 If Xebex were to discontinue production of the component, direct fixed manufacturing costs would be reduced by 80 per cent.
What are the irrelevant costs in the decision?
If Xebex were to discontinue production of the component, direct fixed manufacturing costs would be reduced by 80 per cent.
What are the irrelevant costs in the decision? (Multiple Choice)
4.9/5 (89)
(89) Which of the following would be a relevant cost that would need to be considered for pricing a special order?
(Multiple Choice)
4.7/5 (83)
(83) When performance incentives are part of a manager's remuneration, it is unlikely to influence their decision making.
(True/False)
4.8/5 (84)
(84) The very nature of tactical decisions means that in many situations most overhead costs are considered fixed and may not be relevant to the decision in hand.
(True/False)
4.8/5 (77)
(77) Sleepo Ltd has been manufacturing only one type of alarm clock, the PlainSnooze model. The company is considering developing some modifications to make another, more advanced model. Two options are available: the ToughSnooze and the MusicSnooze. Both ToughSnooze and MusicSnooze will start with the same processes as the PlainSnooze model, but with additional advanced functions. ToughSnooze has a voice activated snooze function, as well as an 'indestructible' aluminium casing, created for people who throw their alarm clocks around. The MusicSnooze also has a voice activated snooze function, but instead of the tough aluminium casing, it has a 'music choice' function.
In choosing between making the ToughSnooze or the MusicSnooze, which of the following costs are relevant?
I The cost of building the PlainSnooze model.
Ii) The cost of building a voice activated snooze function.
Iii The cost of building an 'indestructible' aluminium cover.
Iv The cost of building the 'music choice' function.
(Multiple Choice)
4.8/5 (89)
(89) A company produces products A, B and C and the profit and loss statement for the past twelve months shows the following (in thousands) details. 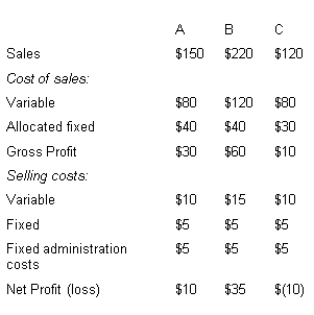 The company is considering dropping Product C. If it does this, the fixed costs will remain the same except that the firm will be able to rent out excess factory space at $30 000 per annum. If other revenue and cost figures remained the same, what would be the effect on annual profit of dropping Product C?
 (Multiple Choice)
4.9/5 (82)
(82) Effect of alternative costing systems on decisions
Traditional volume-based product costing systems and activity-based costing systems have been presented as alternative methods to use to determine product costs.
i. In a traditional volume-based costing system, costs are classified as fixed and variable. In an activity-based costing system, costs are classified into four categories. List those four categories.
ii. Is it possible for the quantitative analysis to differ depending on whether data is developed from a traditional volume-based costing system or an activity-based costing system? If so, explain which of the four categories of cost in question (i) are likely to cause the difference.
(Essay)
4.9/5 (74)
(74) An activity-based approach to cost analysis is similar to a job costing approach.
(True/False)
4.9/5 (82)
(82) The manager of Big Mac Ltd is considering the purchase of equipment to make hamburgers that will reduce annual operating costs by $1500. The equipment will cost $6000 and will have a useful life of five years with no resale value. The new equipment will replace equipment purchased five years ago at a cost of $10 000, that has a book value of $5000 and no resale value. What will be the net effect on profit for the next five years in total if the new equipment is purchased? (Ignore tax effects.)
(Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)