



 Chat with AI
Exam 19: Information for Decisions: Relevant Costs and Benefits

Exam 1: Management Accounting: Information for Creating Value and Managing Resources67 Questions
Exam 2: Management Accounting: Cost Terms and Concepts87 Questions
Exam 3: Cost Behaviour, Cost Drivers and Cost Estimation93 Questions
Exam 4: Product Costing Systems88 Questions
Exam 5: Process Costing and Operation Costing87 Questions
Exam 6: Service Costing91 Questions
Exam 7: A Closer Look at Overhead Costs99 Questions
Exam 8: Activity-Based Costing91 Questions
Exam 9: Budgeting Systems92 Questions
Exam 10: Standard Costs for Control: Direct Material and Direct Labour105 Questions
Exam 11: Standard Costs for Control: Flexible Budgets and Manufacturing Overhead109 Questions
Exam 12: Managing and Reporting Performance102 Questions
Exam 13: Financial Performance Measures and Incentive Schemes93 Questions
Exam 14: Strategic Performance Measurement Systems80 Questions
Exam 15: Managing Suppliers and Customers90 Questions
Exam 16: Managing Costs and Quality92 Questions
Exam 17: Sustainability and Management Accounting76 Questions
Exam 18: Cost Volume Profit Analysis111 Questions
Exam 19: Information for Decisions: Relevant Costs and Benefits116 Questions
Exam 20: Pricing and Product Mix Decisions113 Questions
Exam 21: Information for Capital Expenditure Decisions125 Questions
Select questions type


A firm currently makes a component, and requires 30 000 of them for the coming year's production. Another supplier has offered the part at a delivered price of $3 per unit. It would cost $3000 to check purchased units for quality. Product costs per unit for the past year were $2.35 variable and $1 fixed based on 30 000 units. If the component was bought, fixed overhead would be reduced by $6000, the cost of leasing specialised equipment. The space vacated by the equipment can be rented for $4000 for the year. Which of the following statements is the correct quantitative analysis of the make or buy decision?
(Multiple Choice)
4.8/5  (67)
(67) Kragle Ltd manufacturers a number of specialised electronic components, including the advanced X1000. Kragle Ltd has the capacity to produce 10 000 units of X1000 per year. Currently it is operating at 80 per cent capacity. The selling price for X1000 is $100 per unit. The variable cost per unit is $30. Fixed cost allocated to producing X1000 is $200 000 per year. Kragle Ltd receives a special order for 3000 units of X1000. The opportunity cost associated with taking this special order is:
(Multiple Choice)
4.8/5 (93)
(93) Steps in the decision-making process
The six steps in the decision-making process are to clarify the decision problem, specify the criterion, identify the alternatives, develop a decision model, collect the data and select an alternative.
i. In which step is the management accountant most heavily involved? Explain.
ii. Assume that a decision-making process has been underway for a while and that three alternatives have been developed. At the last step in the process, the managers suddenly realise there is another alternative. Describe which steps in the decision-making process will have to be revisited in order to consider this new alternative.
(Essay)
4.9/5 (76)
(76) Many decisions can be classified as tactical decisions or strategic decisions. Using an example to illustrate both types of decisions, briefly describe the differences between a tactical and strategic decision.
(Essay)
4.8/5 (77)
(77) Sunshine Products is a multiproduct firm. The revenues of a single product are $200 000 when 10 000 units are sold. Variable costs are $16 per unit. Direct fixed expenses of $25 000 consist primarily of depreciation on equipment specialised to the product. By what amount will Sunshine Products' cash flow change if the product is dropped?
(Multiple Choice)
4.8/5 (83)
(83) When a joint production process results in two or more products being produced simultaneously, the products are termed:
(Multiple Choice)
4.9/5 (76)
(76) Why are joint costs never relevant in deciding whether to sell a product at split-off or process it further?
(Multiple Choice)
4.7/5 (80)
(80) The book value of an asset such as equipment is an example of:
(Multiple Choice)
4.7/5 (84)
(84) SloGrowth has idle capacity. They have received a special order for 2000 units at a price of $6 per unit. Currently production and sales are budgeted for 20 000 units without considering the special order. Budget information for the year is presented below. 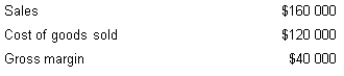 Cost of goods sold includes $20 000 of fixed manufacturing cost. Determine the effect on profit if the special order is accepted.
 (Multiple Choice)
4.8/5 (87)
(87) For which of the following should joint costs and joint cost allocations not be used?
(Multiple Choice)
4.9/5 (88)
(88) The joint cost allocation method that recognises the revenues at split-off but does not consider any further processing costs is the:
(Multiple Choice)
4.8/5 (77)
(77) A well-designed activity-based system helps managers because the costs are analysed in more detail and identify:
(Multiple Choice)
4.9/5 (87)
(87) The method under which the relative magnitude of the final products' net realisable values is used to allocate the joint cost is the:
(Multiple Choice)
4.8/5 (84)
(84) When a business has idle capacity and has two options to choose from that will maximise capacity, the potential benefit that is surrendered by choosing only one option is known as the opportunity cost.
(True/False)
4.7/5 (92)
(92) Lipex Pty Ltd produces two products (A and B) from a particular joint process. Each product may be sold at the split-off point or processed further. Additional processing requires no special facilities, and production costs of further processing are entirely variable and traceable to the products involved. Joint production costs for the year were $60 000. Sales values and costs are as follows. 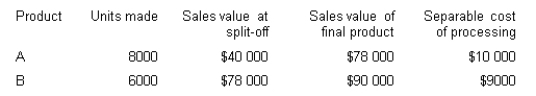 Allocate the joint production costs based on the physical units method. What are the joint costs assigned to product A?
 (Multiple Choice)
4.8/5 (77)
(77) North Central Publishing is considering outsourcing its printing process. Which of the following are relevant for this outsourcing decision?
I The rent associated with the freed-up space when the printing equipment is sold
Ii Supplier's financial stability
Iii The carrying amount of the printing equipment
(Multiple Choice)
4.8/5 (78)
(78) A firm currently makes a component, and requires 30 000 for the coming year's production. Another supplier has offered the part at a delivered price of $3 per unit. It would cost $3000 to check purchased units for quality. Product costs per unit for the past year were $2.35 variable and $1 fixed based on 30 000 units. If the component was bought, fixed overhead would be reduced by $6000, the cost of leasing specialised equipment. The space vacated by the equipment can be rented for $4000 for the year. At what level of units of production is the firm indifferent between making and buying?
(Multiple Choice)
4.8/5 (63)
(63) Kragle Ltd manufacturers a number of specialised electronic components, including the advanced X1000. Kragle Ltd has the capacity to produce 10 000 units of X1000 per year. Currently it is operating at 80 per cent capacity. The selling price for X1000 is $100 per unit. The variable cost per unit is $30. Fixed cost allocated to producing X1000 is $200 000 per year. Kragle Ltd receives a special order for 2000 units of X1000. The opportunity cost associated with taking this special order is:
(Multiple Choice)
4.9/5 (76)
(76) For a firm that currently makes a particular component, which of the following are qualitative factors that would be considered following a quantitative analysis in favour of buying?
(Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)