



 Chat with AI
Exam 20: Managing Credit Risk on the Balance Sheet

Exam 1: Introduction50 Questions
Exam 2: Determinants of Interest Rates62 Questions
Exam 3: Interest Rates and Security Valuation72 Questions
Exam 4: The Federal Reserve System, monetary Policy, and Interest Rates60 Questions
Exam 5: Money Markets61 Questions
Exam 6: Bond Markets61 Questions
Exam 7: Mortgage Markets60 Questions
Exam 8: Stock Markets67 Questions
Exam 9: Foreign Exchange Markets60 Questions
Exam 10: Derivative Securities Markets61 Questions
Exam 11: Commercial Banks: Industry Overview48 Questions
Exam 12: Commercial Banks Financial Statements and Analysis59 Questions
Exam 13: Regulation of Commercial Banks60 Questions
Exam 14: Other Lending Institutions: Savings Institutions, credit Unions, and Finance Companies62 Questions
Exam 15: Insurance Companies62 Questions
Exam 16: Securities Firms and Investment Banks57 Questions
Exam 17: Investment Companies64 Questions
Exam 18: Pension Funds60 Questions
Exam 19: Types of Risks Incurred by Financial Institutions55 Questions
Exam 20: Managing Credit Risk on the Balance Sheet63 Questions
Exam 21: Managing Liquidity Risk on the Balance Sheet60 Questions
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet58 Questions
Exam 23: Managing Risk Off the Balance Sheet With Derivative Securities63 Questions
Exam 24: Managing Risk Off the Balance Sheet With Loan Sales and Securitization60 Questions
Select questions type


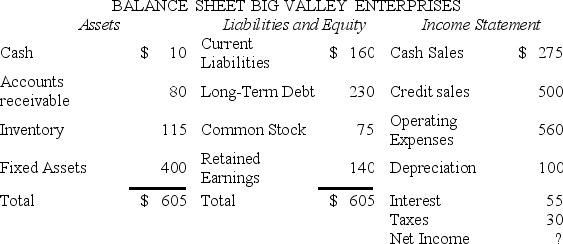 Interest is Big Valley's only fixed cash charge.
Big Valley's market value of equity to book value of debt ratio = 1.5.
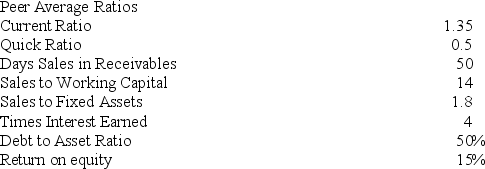 Altman's Z-score model is Z = 1.2X1 + 1.4X2 + 3.3X3 + 0.6X4 + 1.0X5.
X1 = Working Capital/Total Assets
X2 = Retained Earnings/Total Assets
X3 = EBIT/Total Assets
X4 = Market Value Equity/Book Value Long-Term Debt
X5 = Sales/Total Assets
Using the Altman's Z model,Big Valley's Z-score is
Interest is Big Valley's only fixed cash charge.
Big Valley's market value of equity to book value of debt ratio = 1.5.
Altman's Z-score model is Z = 1.2X1 + 1.4X2 + 3.3X3 + 0.6X4 + 1.0X5.
X1 = Working Capital/Total Assets
X2 = Retained Earnings/Total Assets
X3 = EBIT/Total Assets
X4 = Market Value Equity/Book Value Long-Term Debt
X5 = Sales/Total Assets
Using the Altman's Z model,Big Valley's Z-score is (Multiple Choice)
4.8/5  (72)
(72) A corporate loan applicant has had a growing cash account for the last three years,but cash flow from operations has been negative in every year. Would this concern you if you were the loan officer charged with approving the loan? If so,why? If not,why not?
(Essay)
4.9/5 (75)
(75) The more variable a borrower's cash flows are,the lower the fixed charge coverage ratio should be to limit risk.
(True/False)
4.7/5 (79)
(79) 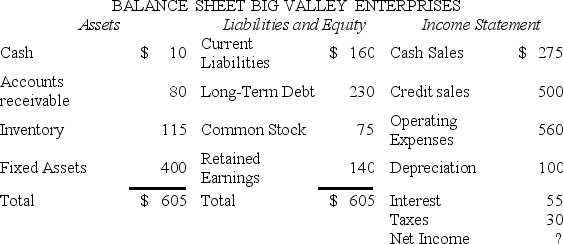 Interest is Big Valley's only fixed cash charge.
Big Valley's market value of equity to book value of debt ratio = 1.5.
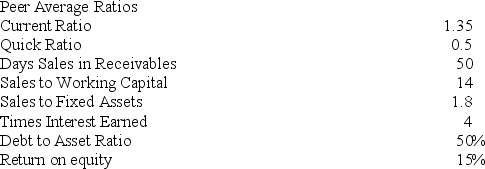 Big Valley has a times interest earned ratio that is ________,which indicates that Big Valley has ________ long-term insolvency risk than the typical firm in the industry.
Interest is Big Valley's only fixed cash charge.
Big Valley's market value of equity to book value of debt ratio = 1.5.
Big Valley has a times interest earned ratio that is ________,which indicates that Big Valley has ________ long-term insolvency risk than the typical firm in the industry. (Multiple Choice)
4.9/5 (81)
(81) Explain what each ratio in the Altman credit model measures and explain why higher values of each of the variables predict lower default probability.
(Essay)
4.8/5 (83)
(83) Mid-market commercial lending may be typically defined as borrowers
I. with sales revenue between $5 million and $100 million.
II. with a recognizable corporate structure.
III. with ready access to deep and liquid capital markets.
(Multiple Choice)
4.9/5 (78)
(78) 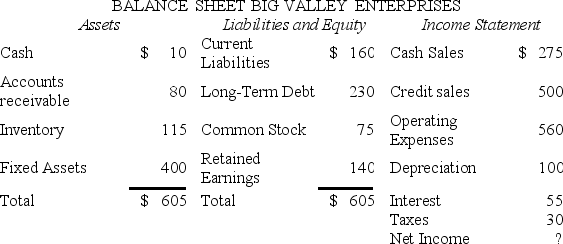 Interest is Big Valley's only fixed cash charge.
Big Valley's market value of equity to book value of debt ratio = 1.5.
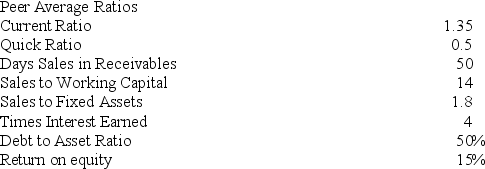 Big Valley's use of debt to finance assets indicates that Big Valley has ________ the typical firm in the industry.
Interest is Big Valley's only fixed cash charge.
Big Valley's market value of equity to book value of debt ratio = 1.5.
Big Valley's use of debt to finance assets indicates that Big Valley has ________ the typical firm in the industry. (Multiple Choice)
4.8/5 (72)
(72) Gross debt service usually must be greater than 30 percent before a residential mortgage will be approved.
(True/False)
4.8/5 (82)
(82) Collateral on a mortgage is normally only considered if the applicant has enough income to service the loan.
(True/False)
4.9/5 (73)
(73) Why is bank lending to large corporations more difficult than making loans to small or mid-size firms? What additional factors are involved? Do banks have some additional tools to help in assessing credit risk of large firms? What are some examples?
(Essay)
4.9/5 (73)
(73) Credit scoring models are probabilistic models based on economic and financial borrower characteristics aiming to determining the likelihood of default of a borrower.
(True/False)
4.8/5 (85)
(85) The conditions specified in a credit agreement that must be fulfilled before a drawdown is allowed are called
(Multiple Choice)
4.7/5 (85)
(85) In analyzing credit risk for a loan to a major diversified corporation,the bank typically has which of the following advantages?
I. Market-based models to analyze credit risk
II. Greater negotiating power due to the size of the loan required
III. Ratings agency measures of default risk
(Multiple Choice)
4.8/5 (75)
(75) The five Cs of credit are financial capacity,collateral,conditions,connections with the bank,and capital.
(True/False)
4.9/5 (74)
(74) If you were a loan officer evaluating a small business credit application for a loan secured by working capital,you would generally want to see a higher (rather than lower)number of days in inventory and number of days' sales in receivables.
(True/False)
4.9/5 (83)
(83) Management of credit risk is achieved through diversification effect by combining numerous loans in a portfolio.
(True/False)
4.9/5 (74)
(74) Business credit-scoring models suffer from several weaknesses. These include which of the following?
I. Credit-score models are not statistically sound tools to use in making a lending decision.
I. The appropriate weights on a credit-score model are likely to change unpredictably over time.
II. These models ignore non-quantifiable behavioral factors,such as a relationship with the bank and reputation.
IV. Credit-scoring models discriminate against minorities.
(Multiple Choice)
4.9/5 (77)
(77) Why won't a loan officer usually approve a loan solely on the basis of collateral?
(Essay)
4.9/5 (83)
(83) ________ is the process of taking possession of the mortgaged property to satisfy the debt in the event of failure to repay the mortgage and foregoing claim to any deficiency.
(Multiple Choice)
4.8/5 (97)
(97) Which one of the following is usually the better predictor of default?
(Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)