



 Chat with AI
Exam 10: Derivative Securities Markets


What determines the success or failure of an exchange-traded derivative contract? Why were currency and interest rate futures introduced in the early and late 1970s,respectively?

 (91)
 Verified
The success of derivative contracts depends upon trading volume (or trader interest),which is in turn dependent on price volatility in the underlying security or commodity value. Currency futures were introduced in the early 1970s in response to the collapse of fixed exchange rates as Bretton Woods collapsed. Exchange rates quickly proved themselves very volatile. Interest rate futures were needed once the Federal Reserve stopped targeting interest rates and began targeting non-borrowed reserves in 1979,allowing interest rates to float and interest rate volatility to increase.
FNMA has direct holdings of 30-year fixed-rate mortgages financed by three- to five-year agency securities sold to the public.
What kind of interest rate swap could FNMA use to limit their interest rate risk? Explain.
(84) VerifiedFNMA's risk is from rising interest rates because the bonds mature more quickly than the mortgages (the mortgage duration is greater). Rising interest rates will increase FNMA's funding cost,but the mortgage income will stay the same. To offset this risk,FNMA could agree to pay a fixed rate of interest on a given notional principal and receive a variable rate of interest. If rates rose,FNMA would receive more interest income,but pay out the same fixed rate on the swap. The swap gain could then offset any loss on the balance sheet.
Refer to the Listed Stock Option Price Quote from February and assume it is now January:
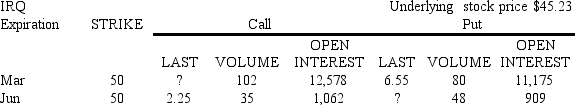 If you buy the March put and don't exercise before contract maturity,you will make a profit if the stock price at maturity ________ from today's price.
 (78) VerifiedC
In a futures contract,if funds in the margin account fall below the maintenance margin requirement,a margin call is issued.
(87) The type of swap most closely linked to the subprime mortgage crisis is the ________.
(76) A speculator may write a put option on stock with an exercise price of $15 and earn a $3 premium only if he thought
(98) By convention,a swap buyer on an interest rate swap agrees to
(71) The buyer of a call option on stock benefits if the underlying stock price rises or if the volatility of the stock's price increases.
(79) A higher level of which of the following variables would make a put option on common stock more valuable,ceteris paribus?
I. Stock price
II. Stock price volatility
III. Interest rates
IV. Exercise price
(73) FNMA has direct holdings of 30-year fixed-rate mortgages financed by three- to five-year agency securities sold to the public.
What kind of interest rate option could FNMA use to limit the interest rate risk? Explain how this would work. Explain how a collar could also be used.
(84) Writing a put option results in a potentially limited gain and a potentially unlimited loss.
(77) A stock has a spot price of $55. Its May options are about to expire. One of its puts is worth $5 and one of its calls is worth $10. The exercise price of the put must be ________ and the exercise price of the call must be ________.
(76) Using the Black-Scholes model,explain what happens to the value of a call as S,T,and σ2 change. Why is the relationship between risk and price different for options than for other securities?
1. As S increases,C (the call premium)increases because the right to buy at the fixed price E has more value as the sale price S rises.
2. As T increases,C increases and as T decreases,C decreases. The less time remaining on the option,the lower its value since there is less time during which the option right is available.
3. As σ increases,C increases.
(86) You would expect the price quote for a put option to be at least $10 if the put had an exercise price of $40 and the underlying stock was selling for $50.
(75) You have taken a stock option position and,if the stock's price drops,you will get a level gain no matter how far prices fall,but you could go bankrupt if the stock's price rises. You have________.
(81) A bank with short-term floating-rate assets funded by long-term fixed-rate liabilities could hedge this risk by
I. buying a T-bond futures contract.
II. buying options on a T-bond futures contract.
III. entering into a swap agreement to pay a fixed rate and receive a variable rate.
IV. entering into a swap agreement to pay a variable rate and receive a fixed rate.
(82) A bank has made a risky loan to a midsize consumer goods manufacturer. With the weaker economy,the borrower is expected to have trouble repaying the loan. The bank decides to purchase a digital default option. Which one of the following payout patterns does a digital option provide?
(82) A bank lender is concerned about the creditworthiness of one of its major borrowers. The bank is considering using a swap to reduce its credit exposure to this customer. Which type of swap would best meet this need?
(88) You find the following current quote for the March T-bond contract: $100,000; Pts 32nd,of 100 percent.
 You went long in the contract at the open. Which of the following is/are true?
I. At the end of the day,your margin account would be increased.
II. 55,210 contracts were traded that day.
III. You agreed to deliver $100,000 face value T-bonds in March in exchange for $89,120.
IV. You agreed to purchase $100,000 face value T-bonds in March in exchange for $89,375.
You went long in the contract at the open. Which of the following is/are true?
I. At the end of the day,your margin account would be increased.
II. 55,210 contracts were traded that day.
III. You agreed to deliver $100,000 face value T-bonds in March in exchange for $89,120.
IV. You agreed to purchase $100,000 face value T-bonds in March in exchange for $89,375. (71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)