



 Chat with AI
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet

Exam 1: Introduction50 Questions
Exam 2: Determinants of Interest Rates62 Questions
Exam 3: Interest Rates and Security Valuation72 Questions
Exam 4: The Federal Reserve System, monetary Policy, and Interest Rates60 Questions
Exam 5: Money Markets61 Questions
Exam 6: Bond Markets61 Questions
Exam 7: Mortgage Markets60 Questions
Exam 8: Stock Markets67 Questions
Exam 9: Foreign Exchange Markets60 Questions
Exam 10: Derivative Securities Markets61 Questions
Exam 11: Commercial Banks: Industry Overview48 Questions
Exam 12: Commercial Banks Financial Statements and Analysis59 Questions
Exam 13: Regulation of Commercial Banks60 Questions
Exam 14: Other Lending Institutions: Savings Institutions, credit Unions, and Finance Companies62 Questions
Exam 15: Insurance Companies62 Questions
Exam 16: Securities Firms and Investment Banks57 Questions
Exam 17: Investment Companies64 Questions
Exam 18: Pension Funds60 Questions
Exam 19: Types of Risks Incurred by Financial Institutions55 Questions
Exam 20: Managing Credit Risk on the Balance Sheet63 Questions
Exam 21: Managing Liquidity Risk on the Balance Sheet60 Questions
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet58 Questions
Exam 23: Managing Risk Off the Balance Sheet With Derivative Securities63 Questions
Exam 24: Managing Risk Off the Balance Sheet With Loan Sales and Securitization60 Questions
Select questions type


The duration gap model is a more complete measure of interest rate risk than the repricing model.

Free
(True/False)
4.8/5  (78)
(78) Correct Answer: Verified
True
A bank has a negative repricing gap using a six-month maturity bucket. Which one of the following statements is most correct if MMDAs are rate-sensitive liabilities?
Free
(Multiple Choice)
4.7/5 (69)
(69) Correct Answer:Verified
VerifiedE
A bank has a negative repricing gap and estimates that the spread between RSAs and RSLs will move inversely with interest rates. If interest rates increase,NII will
Free
(Multiple Choice)
4.7/5 (77)
(77) Correct Answer:Verified
VerifiedB
The repricing gap is the most comprehensive measure of interest rate risk used by financial intermediaries.
(True/False)
4.8/5 (75)
(75) The loss in value caused by credit risk is borne first by the liability holders,and then by the equity holders.
(True/False)
4.9/5 (65)
(65) A bank has DA = 2.4 years and DL= 0.9 years. The bank has total equity of $82 million and total assets of $850 million. Interest rates are at 6 percent.
To get DE to equal zero to protect the equity value in the event of an interest rate change,the bank could
(Multiple Choice)
4.9/5 (88)
(88) If DA > kDL,then falling interest rates will cause the market value of equity to rise.
(True/False)
4.9/5 (74)
(74) What are arguments for and against requiring banks to mark all assets and liabilities to market continuously? Relate your arguments to managing credit risk and interest rate risk.
(Essay)
4.8/5 (86)
(86) A bank has a positive repricing gap and estimates that the spread between RSAs and RSLs will move directly with interest rates. If interest rates fall,the bank's overall NII will
(Multiple Choice)
4.8/5 (93)
(93) A bank has an average asset duration of 2.25 years,the average duration of the liabilities is 1.25 years,and the bank has total assets of $2 billion and $200 million in equity. The bank has an ROE of 9.00 percent. If all interest rates decrease 50 basis points,the predicted change in the bank's market value of equity is ________.
(Multiple Choice)
4.9/5 (78)
(78) According to the CGAP effect,when CGAP is positive the change in NII is negatively related to the change in interest rates.
(True/False)
4.9/5 (77)
(77) The maturity bucket is the time window over which the dollar amounts of assets and liabilities are measured.
(True/False)
4.9/5 (78)
(78) A bank has a positive duration gap. Which one of the following statements is most correct?
(Multiple Choice)
4.8/5 (90)
(90) In a bank's three-month maturity bucket,a 30-year ARM with a rate reset in six months would be considered a fixed-rate asset,but in its one-year maturity bucket,this ARM would be considered a rate-sensitive asset.
(True/False)
4.9/5 (90)
(90) Convexity arises because a fixed-income's price is a nonlinear function of interest rates.
(True/False)
4.9/5 (81)
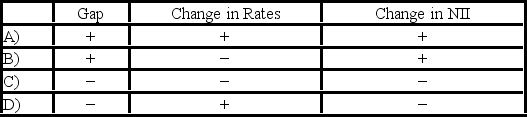
(81) A thrift has an annual CGAP of −$25 million. A credit union has an annual CGAP of +$5 million. The thrift has total assets of $500 million and net income of $7.5 million,and the credit union has total assets of $40 million and net income of $0.7 million.
In each of the following cases indicate whether the change in profits due to the spread effect was (i)greater than (ii)less than,or (iii)equal to the change in profitability due to the repricing GAP. In some cases you may not be able to tell; indicate which ones.
(Essay)
4.9/5 (86)
(86) Due to convexity problems,banks are actually better off using the simpler repricing model to manage interest rate risk rather than the duration model.
(True/False)
4.7/5 (76)
(76) The effect of an interest rate change on the market value of an FI's equity is a function of three things. What are they and how do they affect the equity value change?
(Essay)
4.8/5 (84)
(84) The structure of a bank's balance sheet as evidenced by its repricing gap and its duration gap affects a bank's sensitivity to interest rate changes. Which one of the following statements about the two types of gaps is true?
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)