



 Chat with AI
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet

Exam 1: Introduction50 Questions
Exam 2: Determinants of Interest Rates62 Questions
Exam 3: Interest Rates and Security Valuation72 Questions
Exam 4: The Federal Reserve System, monetary Policy, and Interest Rates60 Questions
Exam 5: Money Markets61 Questions
Exam 6: Bond Markets61 Questions
Exam 7: Mortgage Markets60 Questions
Exam 8: Stock Markets67 Questions
Exam 9: Foreign Exchange Markets60 Questions
Exam 10: Derivative Securities Markets61 Questions
Exam 11: Commercial Banks: Industry Overview48 Questions
Exam 12: Commercial Banks Financial Statements and Analysis59 Questions
Exam 13: Regulation of Commercial Banks60 Questions
Exam 14: Other Lending Institutions: Savings Institutions, credit Unions, and Finance Companies62 Questions
Exam 15: Insurance Companies62 Questions
Exam 16: Securities Firms and Investment Banks57 Questions
Exam 17: Investment Companies64 Questions
Exam 18: Pension Funds60 Questions
Exam 19: Types of Risks Incurred by Financial Institutions55 Questions
Exam 20: Managing Credit Risk on the Balance Sheet63 Questions
Exam 21: Managing Liquidity Risk on the Balance Sheet60 Questions
Exam 22: Managing Interest Rate Risk and Insolvency Risk on the Balance Sheet58 Questions
Exam 23: Managing Risk Off the Balance Sheet With Derivative Securities63 Questions
Exam 24: Managing Risk Off the Balance Sheet With Loan Sales and Securitization60 Questions
Select questions type


If a bank wishes to have a positive balance sheet repricing gap and a negative balance sheet duration gap,then the bank should predominantly have short-term rate-sensitive assets funded by long-term fixed-rate liabilities.
(True/False)
4.8/5  (81)
(81) A bank has three assets. It has $75 million invested in consumer loans with a three-year duration,$39 million invested in T-bonds with a 16-year duration,and $39 million in six-month maturity T-bills. What is the duration of the bank's asset portfolio in years?
(Multiple Choice)
4.7/5 (91)
(91) The cash flow from the interest a bank receives on a long-term loan that is normally reinvested is called the runoff from the loan.
(True/False)
4.9/5 (82)
(82) A bank is facing a forecast of rising interest rates. How should it set the repricing and duration gap?
(Multiple Choice)
4.8/5 (73)
(73) A bank manager would want to set the repricing gap greater than zero when interest rates are expected to rise.
(True/False)
4.8/5 (77)
(77) For a bank with a positive duration gap,an increase in interest rates will
(Multiple Choice)
4.9/5 (79)
(79) A thrift has an annual CGAP of −$25 million. A credit union has an annual CGAP of +$5 million. The thrift has total assets of $500 million and net income of $7.5 million,and the credit union has total assets of $40 million and net income of $0.7 million.
Calculate each institution's CGAP as a percent of assets. Based on the gap,which institution's NII is more sensitive to interest rates? Explain.
(Essay)
4.8/5 (87)
(87) For large interest rate declines,duration ________ the increases in the bond's price,and for large interest rate decreases,it ________ the decline in the bond's price.
(Multiple Choice)
4.7/5 (75)
(75) A rate-sensitive asset is one that either matures within the maturity bucket or one that will have a payment change within the maturity bucket if interest rates change.
(True/False)
4.9/5 (59)
(59) For a one-year maturity bucket,the repricing model assumes that a nine-month loan is as equally rate-sensitive as a three-month loan.
(True/False)
5.0/5 (81)
(81) If a bank has a negative repricing gap,falling interest rates increase profitability.
(True/False)
4.8/5 (71)
(71) A bank has the following balance sheet:
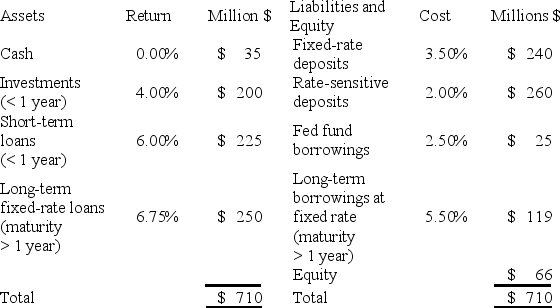 If the spread effect is zero and all interest rates decline 50 basis points,the bank's NII will change by ________ over the year.
 (Multiple Choice)
4.9/5 (73)
(73) A bank has a negative duration gap. Which one of the following statements is most correct?
(Multiple Choice)
4.9/5 (72)
(72) A bank manager would want to set the duration gap greater than zero when interest rates are expected to rise.
(True/False)
4.8/5 (74)
(74) Weaknesses of the repricing model include the fact that
I. it ignores changes in present values caused by changes in interest rates.
II. it ignores different cash flow sensitivities within a maturity bucket.
III. it fails to account for runoffs and prepayments.
(Multiple Choice)
4.8/5 (82)
(82) A bank has the following balance sheet:
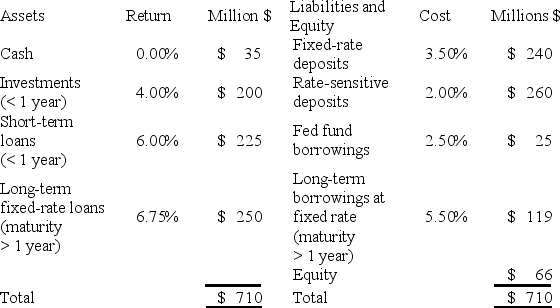 For a nine-month maturity bucket,the bank has ________ in fixed-rate assets and ________ in fixed-rate liabilities.
 (Multiple Choice)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)