



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics438 Questions
Exam 2: Thinking Like an Economist620 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand700 Questions
Exam 5: Elasticity and Its Application598 Questions
Exam 6: Supply, Demand, and Government Policies648 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets550 Questions
Exam 8: Application: The Costs of Taxation514 Questions
Exam 9: Application: International Trade496 Questions
Exam 10: Externalities522 Questions
Exam 11: Public Goods and Common Resources434 Questions
Exam 12: The Costs of Production420 Questions
Exam 13: Firms in Competitive Markets543 Questions
Exam 14: Monopoly637 Questions
Exam 15: Measuring a Nations Income522 Questions
Exam 16: Measuring the Cost of Living545 Questions
Exam 17: Production and Growth507 Questions
Exam 18: Saving, Investment, and the Financial System567 Questions
Exam 19: The Basic Tools of Finance513 Questions
Exam 20: Unemployment699 Questions
Exam 21: The Monetary System518 Questions
Exam 22: Money Growth and Inflation487 Questions
Exam 23: Aggregate Demand and Aggregate Supply563 Questions
Exam 24: The Influence of Monetary and Fiscal Policy on Aggregate Demand512 Questions
Select questions type


Figure 7-1  -Refer to Figure 7-1. If the price of the good is $200, then
 (Multiple Choice)
4.9/5  (85)
(85) Suppose Raymond and Victoria attend a charity benefit and participate in a silent auction. Each has in mind a maximum amount that he or she will bid for an oil painting by a locally famous artist. This maximum is called
(Multiple Choice)
4.7/5 (83)
(83) At the equilibrium price of a good, the good will be sold by those sellers
(Multiple Choice)
4.8/5 (89)
(89) Table 7-5
For each of three potential buyers of oranges, the table displays the willingness to pay for the first three oranges of the day. Assume Allison, Bob, and Charisse are the only three buyers of oranges, and only three oranges can be supplied per day.
 -Refer to Table 7-5. If the market price of an orange is $0.40, then
 (Multiple Choice)
5.0/5 (71)
(71) Which of the Ten Principles of Economics does welfare economics explain more fully?
(Multiple Choice)
4.9/5 (70)
(70) Dallas buys strawberries, and he would be willing to pay more than he now pays. Suppose that Dallas has a change in his tastes such that he values strawberries more than before. If the market price is the same as before, then
(Multiple Choice)
4.7/5 (72)
(72) Figure 7-13  -Refer to Figure 7-13. If the equilibrium price is $60, what is the producer surplus?
 (Multiple Choice)
4.9/5 (81)
(81) Figure 7-2 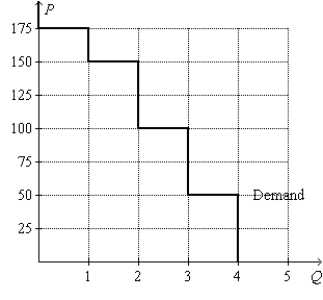 -Refer to Figure 7-2. If the price of the good is $100, then consumer surplus amounts to
 (Multiple Choice)
4.9/5 (74)
(74) Economists say that a market where goods are not consumed by those valuing the goods most highly is
(Multiple Choice)
4.9/5 (82)
(82) Market power and externalities are examples of market failures.
(True/False)
4.8/5 (69)
(69) Wendy is willing to pay $50 for a concert ticket and Bruce would like to receive $25. If the market price is $40 for this transaction, then the total surplus would be $15.
(True/False)
4.7/5 (92)
(92) Figure 7-27  -Refer to Figure 7-27. Sellers whose costs are less than the equilibrium price are represented by which line segment?
 (Multiple Choice)
4.9/5 (82)
(82) Figure 7-34  -Refer to Figure 7-34. Suppose there is initially a price ceiling set at $4 in this market. If the government removed the price ceiling, by how much would total producer surplus increase for those producers entering the market after the price ceiling is removed?
 (Essay)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)