



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


The property factor includes business assets that the taxpayer owns, but also those merely used under a lease agreement.
(True/False)
4.8/5  (76)
(76) Chipper Corporation realized $1,000,000 taxable income from the sales of its products in States X and Z. Chipper's activities establish nexus for income tax purposes only in Z, the state of its incorporation. Chipper's sales, payroll, and property among the states include the following. 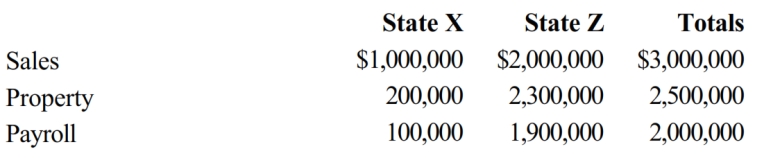 X utilizes a sales-only factor in its three-factor apportionment formula. How much of Chipper's taxable income is apportioned to X?
 (Multiple Choice)
4.9/5 (78)
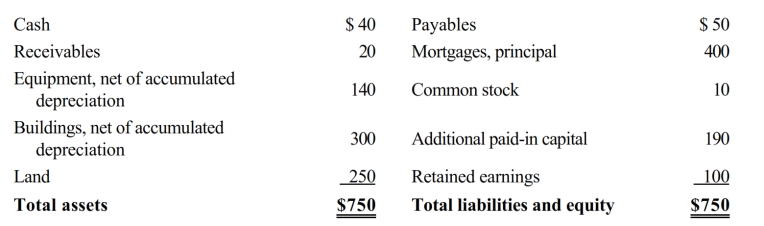
(78) Hambone Corporation is subject to the State E capital stock tax. The tax is levied at 2% of the entity's net worth that is apportioned to E. Hambone conducts 30% of its operations in State E. Hambone's current book balance sheet is as follows, with amounts in millions. Compute Hambone's liability for the E capital stock tax.
(Essay)
4.9/5 (72)
(72) Double weighting the sales factor effectively decreases the corporate income tax burden on taxpayers based in the state, such as entities with in-state headquarters.
(True/False)
4.8/5 (76)
(76) Match each of the following terms with the appropriate description, in the state income tax formula. Apply the UDITPA rules in your responses.
a. Addition modification
b. Subtraction modification
c. No modification
-Deduction for advertising expenditures.
(Short Answer)
4.9/5 (80)
(80) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a. Taxable
b. Not taxable
-Computer equipment purchased by a charity.
(Short Answer)
4.8/5 (80)
(80) Typically exempt from the sales/use tax base is the purchase of clothing from a neighbor's "garage sale."
(True/False)
4.8/5 (81)
(81) In computing the property factor, property owned by the corporation typically is valued at its ________________, but without adjusting for depreciation.
(Short Answer)
4.8/5 (65)
(65) ________________ describe(s) the degree of business activity that must be present before a taxing jurisdiction has the right to impose a tax on an out-of-state entity's income.
(Short Answer)
4.8/5 (94)
(94) Compost Corporation has finished its computation of Federal taxable income. In State Q, the derivation of state corporate taxable income starts with the Federal amount and makes a number of modifications. List at least five such modifications that Compost is likely to encounter. In this regard, follow the general UDITPA rules, and list both addition and subtraction modifications.
(Essay)
4.8/5 (84)
(84) Match each of the following items with the appropriate description, in applying the P.L. 86-272 definition of solicitation.
a. More than solicitation, creates nexus
b. Solicitation only, no nexus created
-Making a decision as to the creditworthiness of customers.
(Short Answer)
4.8/5 (81)
(81) In international taxation, we discuss income sourcing rules and the permanent establishment doctrine. In multistate taxation, an analogous term might be the "ultimate destination concept." Define this term, and identify at least two of the most important exceptions to the general rule.
(Essay)
4.8/5 (71)
(71) Match each of the following terms with the appropriate description, in the state income tax formula. Apply the UDITPA rules in your responses.
a. Addition modification
b. Subtraction modification
c. No modification
-Treasury Bond interest income.
(Short Answer)
4.8/5 (86)
(86) The ________________ tax levied by a state usually is based on the book value of a corporation's "net worth."
(Short Answer)
4.8/5 (75)
(75) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a. Taxable
b. Not taxable
-A textbook purchased by a State University student.
(Short Answer)
5.0/5 (100)
(100) Typical indicators of income-tax nexus include the presence of customers in the state.
(True/False)
4.9/5 (100)
(100) Typically exempt from the sales/use tax base is the purchase by a symphony orchestra of printed music for its players.
(True/False)
5.0/5 (76)
(76) In ________________ states, a(n ________________) election permits a multinational corporation to elect to limit the reach of the state's taxing jurisdiction to activities occurring within the boundaries of the United States.
(Short Answer)
4.8/5 (91)
(91) Cruz Corporation owns manufacturing facilities in States A, B, and C. A uses a three-factor apportionment formula under which the sales, property and payroll factors are equally weighted. B uses a three-factor apportionment formula under which sales are double-weighted. C employs a single-factor apportionment factor, based solely on sales. Cruz's operations generated $1,000,000 of apportionable income, and its sales and payroll activity and average property owned in each of the three states is as follows.
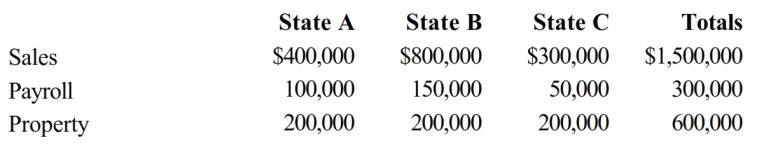 Cruz's apportionable income assigned to C is:
 (Multiple Choice)
4.7/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)