



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


You are completing the State A income tax return for Quaint Company, LLC. Quaint operates in various states, showing the following results.
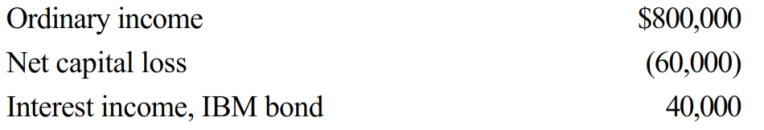 In A, all interest is treated as apportionable income. A uses a sales-only apportionment factor. Compute Quaint's A taxable income.
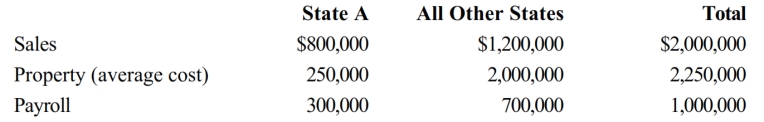
In A, all interest is treated as apportionable income. A uses a sales-only apportionment factor. Compute Quaint's A taxable income.
(Essay)
4.9/5  (70)
(70) A taxpayer wishing to reduce the negative tax effects of the application of the unitary theory might:
(Multiple Choice)
4.7/5 (89)
(89) Troy, an S corporation, is subject to tax only in State a. On Schedule K of its Federal Form 1120S, Troy reported ordinary income of $2,000,000 from its business, municipal bond interest of $150,000, taxable interest of $150,000,
and charitable contributions of $300,000. A does not recognize S status, but it does follow the Federal provisions with respect to the determination of taxable income for a corporation. Determine Troy's A taxable income.
(Essay)
5.0/5 (70)
(70) Under the UDITPA's ________________ concept, sales are assumed to take place at the point of delivery, as opposed to the location at which the shipment originates.
(Short Answer)
4.9/5 (72)
(72) A typical state taxable income subtraction modification is the interest income earned from another state's bonds.
(True/False)
4.7/5 (89)
(89) State Q has adopted sales-factor-only apportionment for its corporate income tax. As a result, a ________________ (larger/smaller) percentage of an out-of-state corporation's income is assigned to tax in the state.
(Short Answer)
4.9/5 (76)
(76) Indicate for each transaction whether a sales (S) or use (U) applies, or whether the transaction is nontaxable (N).
Where the laws vary among various states, assume that the most common rules apply. All taxpayers are individuals.
a. A resident of State A purchases a computer in A.
b. A resident of State A purchases prescription medicine in A.
c. A resident of State B purchases a computer in A.
d. A church purchases office supplies in A.
e. A State A retailer purchases in B an item that will be in the inventory of its business.
f. A resident of State A purchases hardware from a retail home improvement store in a.
g. A business based in State A purchases vacant A land, to be held for a future expansion project.
h. A business based in State A purchases repair services from an A plumbing contractor.
(Essay)
4.9/5 (98)
(98) Some of the states use, in determining whether an out-of-state entity has income tax nexus:
(Multiple Choice)
4.9/5 (77)
(77) Typically exempt from the sales/use tax base is the purchase of tools by a manufacturer to make the widgets that it sells.
(True/False)
4.8/5 (78)
(78) The benefits of a passive investment company typically include:
(Multiple Choice)
4.7/5 (82)
(82) Helene Corporation owns manufacturing facilities in States A, B, and C. A uses a three-factor apportionment formula under which the sales, property and payroll factors are equally weighted. B uses a three-factor apportionment formula under which sales are double-weighted. C employs a single-factor apportionment factor, based solely on sales. Helene's operations generated $1,000,000 of apportionable income, and its sales and payroll activity and average property owned in each of the three states is as follows.
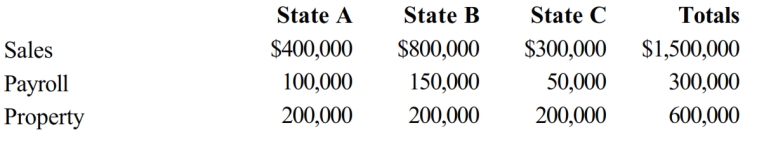 Helene's apportionable income assigned to A is:
 (Multiple Choice)
5.0/5 (73)
(73) The typical local property tax falls on both an investor's principal residence and her stock portfolio.
(True/False)
4.8/5 (94)
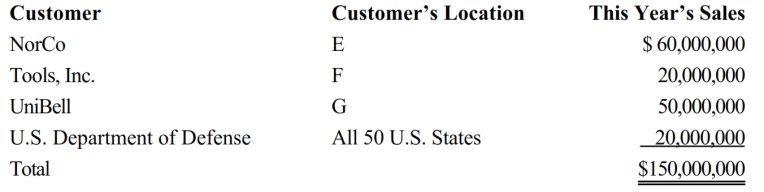
(94) Mercy Corporation, headquartered in State F, sells wireless computer devices, including keyboards and bar code readers. Mercy's degree of operations is sufficient to establish nexus only in States E and F. Determine its sales factor in those states.
State E applies a throwback rule to sales, while State F does not. State G has not adopted an income tax to date. Mercy reported the following sales for the year. All of the goods were shipped from Mercy's F manufacturing facilities.
(Essay)
4.8/5 (73)
(73) The typical state sales/use tax falls on sales of both real and personal property.
(True/False)
4.9/5 (75)
(75) An ad valorem property tax is based on the asset's current ________________ .
(Short Answer)
4.8/5 (79)
(79) In determining a corporation's taxable income for state income tax purposes, which of the following does not constitute a subtraction from Federal income?
(Multiple Choice)
4.9/5 (87)
(87) In the broadest application of the unitary theory, the U.S. unitary business files a combined tax return using factors and income amounts for all affiliates:
(Multiple Choice)
4.7/5 (76)
(76) By making a water's edge election, the multinational taxpayer can limit the reach of unitary principles to the apportionment factors and income of its U.S. and E.U. affiliates.
(True/False)
4.9/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)