



 Chat with AI
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges


Milton purchases land and a factory building for his business for $300,000 with $100,000 being allocated to the land.
During the first year, Milton deducts cost recovery of $4,922. Milton's adjusted basis for the building at the end of the first year is $195,078 ($200,000 - $4,922).

 (74)
 Verified
True
Taylor inherited 100 acres of land on the death of his father in 2018. A Federal estate tax return was filed and this land was valued therein at $650,000, its fair market value at the date of the father's death. The father had originally acquired the land in 1972 for $112,000 and prior to his death he had expended $20,000 on permanent improvements. Determine Taylor's holding period for the land.
(85) VerifiedB
Samuel's hotel is condemned by the City Housing Authority on July 5, 2018, for which he is paid condemnation proceeds of $950,000. He first received official notification of the pending condemnation on May 2, 2018. Samuel's adjusted basis for the hotel is $600,000 and he uses a fiscal year for tax purposes with a September 30 tax year-end.
a. How much must Samuel reinvest in qualifying replacement property in order to postpone the recognition of realized gain?
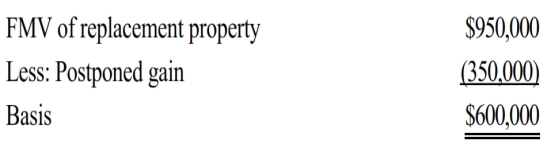
b. If Samuel reinvests the minimum amount required to avoid recognition of realized gain, what is his basis for the replacement property?
c. What is qualifying replacement property?
d. What is the earliest date that Samuel can acquire qualifying replacement property?
e. What is the latest date that Samuel can acquire qualifying replacement property?
f. How would the answer in e. change if Samuel's hotel had been destroyed in a flood?
(85) Verifieda. Samuel must reinvest at least $950,000, an amount equal to the amount realized. This results in a postponed gain of $350,000 ($950,000 amount realized - $600,000 adjusted basis).
b. Samuel's basis for the replacement property would be:
c. Since business real property has been condemned, the broader like-kind exchange rules apply. Thus, any realty (i.e., improved or unimproved) will suffice as replacement property.
d. The earliest date that Samuel can acquire another hotel is May 2, 2018, the date of the threat or imminence of requisition or condemnation of the property.
e. The latest date that Samuel can acquire another hotel is September 30, 2021 (three years after the close of the tax year in which the proceeds received are large enough to produce a realized gain).
f. The latest date that Samuel can acquire another hotel is September 30, 2020 (two years after the close of the tax year in which the proceeds received are large enough to produce a realized gain).
Neal and his wife Faye reside in Texas, a community property state. Their community property consists of real estate (adjusted basis of $800,000? fair market value of $6 million) and personal property (adjusted basis of $390,000? fair market value of $295,000). Neal dies first and leaves his estate to Faye. What is Faye's basis in the property after Neal's death?
(72) Terry owns Lakeside, Inc. stock (adjusted basis of $80,000), which she sells to her brother, Jake, for $64,000 (its fair market value). Eighteen months later, Jake sells the stock to Pamela, a friend, for $78,000 (its fair market value). What is Terry's recognized loss, Jake's recognized gain or loss, and Pamela's adjusted basis for the stock? 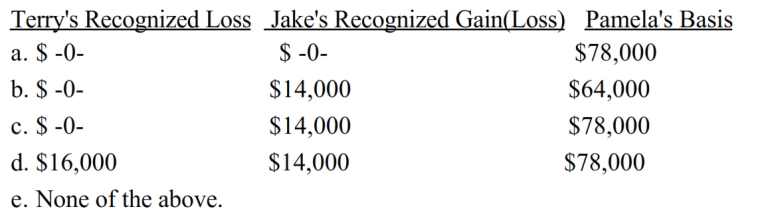
(87) What effect do the assumption of liabilities have on a § 1031 like-kind exchange?
(90) Kevin purchased 5,000 shares of Purple Corporation stock at $10 per share. Two years later, he receives a 5% common stock dividend. At that time, the common stock of Purple Corporation had a fair market value of $12.50 per share. What is the basis of the Purple Corporation stock, the per share basis, and gain recognized upon receipt of the common stock dividend?
(89) During 2018, Ted and Judy, a married couple, decided to sell their residence, which had a basis of $300,000. They had owned and occupied the residence for 20 years. To make it more attractive to prospective buyers, they had the outside painted in April at a cost of $6,000 and paid for the work immediately. They sold the house in May for $880,000. Broker's commissions and other selling expenses amounted to $53,000. Since they both are age 68, they decide to rent an apartment. They purchase an annuity with the net proceeds from the sale. What is the recognized gain?
(84) Ed and Cheryl have been married for 27 years. They own land jointly with a basis of $300,000. Ed dies in 2018, when the fair market value of the land is $500,000. Under the joint ownership arrangement, the land passed to Cheryl.
a. If Ed and Cheryl reside in a community property state, what is Cheryl's basis in the land?
b. If Ed and Cheryl reside in a common law state, what is Cheryl's basis in the land?
(73) Melissa, age 58, marries Arnold, age 50, on June 1, 2018. Melissa decides to sell her principal residence on August 1, 2018, which she has owned and occupied for the past 30 years. Arnold has never owned a house. However, while he was married to Kelly who died 6 months prior to his marriage to Melissa, Kelly used the § 121 election on the sale of her residence in January 2016 to reduce her realized gain from $123,000 to $0. Kelly used the sales proceeds to pay off Arnold's gambling debts. Can Melissa elect the § 121 exclusion on the sale of her residence? What is the maximum § 121 exclusion available to Melissa and Arnold if they file a joint return?
(83) What requirements must be satisfied to receive nontaxable exchange treatment under § 1031?
(89) When a taxpayer has purchased several lots of stock on different dates at different purchase prices and cannot identify the lot of stock that is being sold, he should use either a weighted average approach or a LIFO approach.
(69) An exchange of two items of personal property (personalty) that belong to different general business asset classes qualifies for nonrecognition under § 1031 as long as both properties are used in the taxpayer's trade or business.
(77) Maud exchanges a rental house at the beach with an adjusted basis of $225,000 and a fair market value of $200,000 for a rental house at the mountains with a fair market value of $180,000 and cash of $20,000. What is the recognized gain or loss?
(69) In a nontaxable exchange, recognition is postponed. In a tax-free transaction, nonrecognition is permanent.
(74) Discuss the treatment of realized gains from involuntary conversions.
(73) A strip along the boundary of Joy's land is condemned for a utility easement. She receives a payment of $7,500 from the utility company. Her basis in the land is $80,000. Which of the following is correct?
(74) Weston sells his residence to Joanne on October 15, 2018. Indicate which of the following statements is correctly associated with § 121 (exclusion of gain on sale of principal residence).
(89) Purchased goodwill is assigned a basis equal to cost, which is calculated using the residual method associated with the purchase of a business.
(80) A factory building owned by Amber, Inc. is destroyed by a hurricane. The adjusted basis of the building was $400,000 and the appraised value was $425,000. Amber receives insurance proceeds of $390,000. A factory building is constructed during the nine-month period after the hurricane at a cost of $450,000. What is the recognized gain or loss and what is the basis of the new factory building?
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)