



 Chat with AI
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


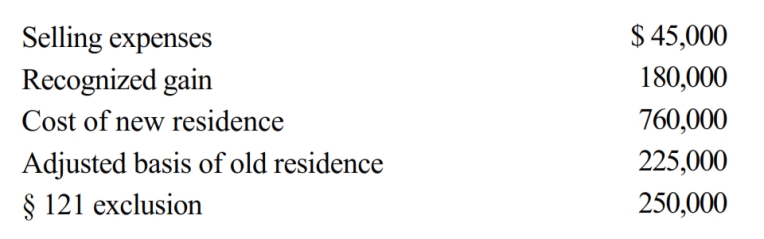
Use the following data to determine the sales price of Etta's principal residence and the realized gain. She is not married. The sale of the old residence qualifies for the § 121 exclusion.
(Essay)
4.9/5  (70)
(70) Discuss the relationship between the postponement of realized gain under § 1031 (like-kind exchanges) and the adjusted basis and holding period for the replacement property.
(Essay)
4.9/5 (80)
(80) The exchange of unimproved real property located in Topeka (KS) for improved real property located in Atlanta (GA) does not qualify as a like-kind exchange.
(True/False)
4.9/5 (80)
(80) Lynn purchases a house for $52,000. She converts the property to rental property when the fair market value is $115,000. After deducting depreciation (cost recovery) expense of $1,130, she sells the house for $120,000. What is her recognized gain or loss?
(Multiple Choice)
4.9/5 (83)
(83) Kendra owns a home in Atlanta. Her company transfers her to Chicago on January 2, 2018, and she sells the Atlanta house in early February 2018. She purchases a residence in Chicago on February 3, 2018. On December 15, 2018, Kendra's company transfers her to Los Angeles. In January 2019, she sells the Chicago residence and purchases a residence in Los Angeles. Because multiple sales have occurred within a two-year period, § 121 treatment does not apply to the sale of the second home.
(True/False)
4.9/5 (77)
(77) To qualify for the § 121 exclusion, the property must have been used by the taxpayer for the 5 years preceding the date of sale and owned by the taxpayer as the principal residence for the last 2 of those years.
(True/False)
4.7/5 (66)
(66) Wade is a salesman for a real estate development company. Because he is the "salesperson of the year," he is permitted to purchase a lot from the developer for $90,000. The fair market value of the lot is $150,000 and the developer's adjusted basis is $100,000. Wade must recognize a gain of $10,000 ($100,000 developer's adjusted basis- $90,000 cost to Wade), and his adjusted basis for the lot is $100,000 ($90,000 cost + $10,000 recognized gain).
(True/False)
4.8/5 (78)
(78) To be eligible to elect postponement of gain treatment for an involuntary conversion, what are the three tests for qualifying replacement property?
(Essay)
4.9/5 (74)
(74) Evelyn, a calendar year taxpayer, lists her principal residence with a realtor on February 7, 2018, enters into a contract to sell on July 12, 2018, and sells (i.e., the closing date) the residence on August 1, 2018. The realized gain on the sale is $225,000. Which date is the appropriate ending date in determining if the residence has been owned and used by the Evelyn as the principal residence for at least two years during the prior five-year period?
(Multiple Choice)
4.8/5 (71)
(71) On October 1, Paula exchanged an apartment building (adjusted basis of $375,000 and subject to a mortgage of $125,000) for another apartment building owned by Nick (fair market value of $550,000 and subject to a mortgage of $125,000). The property transfers were made subject to the mortgages. What amount of gain should Paula recognize?
(Multiple Choice)
4.8/5 (84)
(84) Why is it generally undesirable to pass property by death when its fair market value is less than basis?
(Essay)
4.9/5 (87)
(87) Discuss the effect of a liability assumption on the seller's amount realized and the buyer's adjusted basis.
(Essay)
4.8/5 (82)
(82) In a deductible casualty or theft, the basis of property involved is reduced by the amount of insurance proceeds received and by any resulting recognized loss.
(True/False)
4.8/5 (87)
(87) Mona purchased a business from Judah for $1,000,000. Judah's records and an appraiser provided her with the following information regarding the assets purchased: 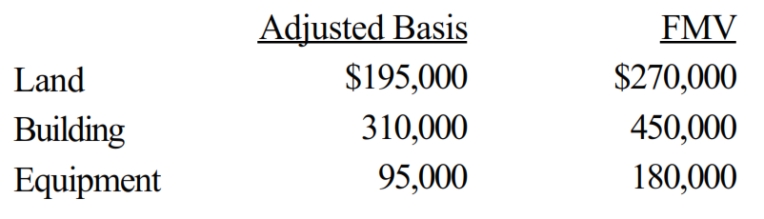 What is Mona's adjusted basis for the land, building, and equipment?
 (Multiple Choice)
4.9/5 (69)
(69) Lump-sum purchases of land and a building are allocated on the basis of the relative fair market values of the individual assets acquired.
(True/False)
4.9/5 (77)
(77) A realized gain whose recognition is postponed results in the temporary recovery of more than the taxpayer's cost or other basis.
(True/False)
4.8/5 (81)
(81) Alice owns land with an adjusted basis of $610,000, subject to a mortgage of $350,000. On April 1, Alice sells her land subject to the mortgage for $650,000 in cash, a note for $600,000, and property with a fair market value of $120,000. What is the amount realized?
(Multiple Choice)
4.7/5 (68)
(68) The basis for gain and loss of personal use property converted to business use is the lower of the adjusted basis or the fair market value on the date of conversion.
(True/False)
4.9/5 (91)
(91) Alice owns land with an adjusted basis of $305,000, subject to a mortgage of $175,000. On April 1, 2018, Alice sells her land subject to the mortgage for $325,000 in cash, a note for $300,000, and property with a fair market value of $60,000. What is Alice's amount realized on this sale?
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)