



 Chat with AI
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


On April 5, 2018, Orange Corporation purchased, and placed in service, seven-year class assets costing $1,030,000 and five-year class assets costing $140,000. Orange elects to expense the maximum amount under § 179. Orange does not take additional first-year depreciation. Assume taxable income is not a limitation. Determine Orange Corporation's maximum cost recovery with respect to the assets for 2018.

Free
(Essay)
4.8/5  (83)
(83) Correct Answer: Verified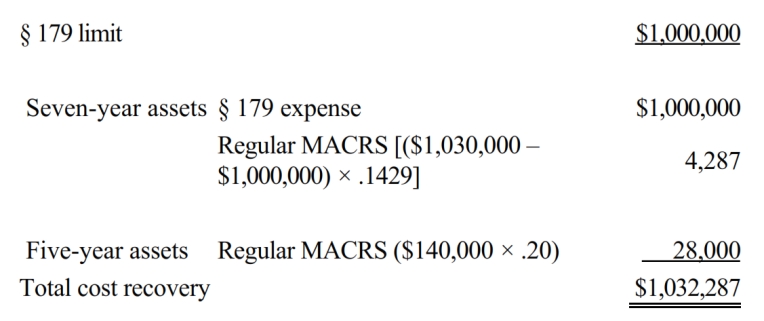
Percentage depletion enables the taxpayer to recover more than the cost of an asset in the form of tax deductions.
Free
(True/False)
4.9/5 (86)
(86) Correct Answer:Verified
VerifiedTrue
A used $35,000 automobile that is used 100% for business is placed in service in 2018. If the automobile fails the 50% business usage test in the second year, no cost recovery will be recaptured.
Free
(True/False)
4.8/5 (72)
(72) Correct Answer:Verified
VerifiedFalse
James purchased a new business asset (three-year personalty) on July 23, 2018, at a cost of $40,000. James takes additional first-year depreciation but does not elect Section 179 expense on the asset. Determine the cost recovery deduction for 2018.
(Multiple Choice)
4.8/5 (86)
(86) Hazel purchased a new business asset (five-year asset) on September 30, 2018, at a cost of $100,000. On October 4, 2018, Hazel placed the asset in service. This was the only asset Hazel placed in service in 2018. Hazel did not elect § 179 or additional first-year depreciation. On August 20, 2019, Hazel sold the asset. Determine the cost recovery for 2019 for the asset.
(Multiple Choice)
4.9/5 (86)
(86) Jenna acquires a new seven-year class asset on September 20, 2018, for $80,000. She placed the asset in service on October 5, 2018. She does not elect to expense any of the asset under § 179 or elect straight-line, cost recovery. She takes additional first-year depreciation. She sells the asset on August 25, 2019. This is the only asset she acquires in 2018. Determine Jenna's cost recovery in 2018 and 2019.
(Essay)
4.9/5 (79)
(79) For real property, the ADS convention is the mid-month convention.
(True/False)
4.9/5 (76)
(76) The only asset Bill purchased during 2018 was a new seven-year class asset. The asset, which was listed property, was acquired on June 17 at a cost of $50,000. The asset was used 40% for business, 30% for the production of income, and the rest of the time for personal use. Bill always elects to expense the maximum amount under § 179 whenever it is applicable. The net income from the business before the § 179 deduction is $100,000. Determine Bill's maximum deduction with respect to the property for 2018.
(Multiple Choice)
4.9/5 (76)
(76) Taxpayers may elect to use the straight-line method under MACRS for personalty.
(True/False)
4.9/5 (73)
(73) On June 1, 2018, Red Corporation purchased an existing business. With respect to the acquired assets of the business, Red allocated $300,000 of the purchase price to a patent. The patent will expire in 20 years. Determine the total amount that Red may amortize for 2018 for the patent.
(Multiple Choice)
4.9/5 (88)
(88) The inclusion amount for a leased automobile is adjusted by a business usage percentage.
(True/False)
4.9/5 (72)
(72) Pat purchased a used five-year class asset on March 15, 2018, for $60,000. He did not elect § 179 expensing. Determine the cost recovery deduction for 2018 for earnings and profits purposes.
(Multiple Choice)
4.9/5 (79)
(79) If more than 40% of the value of property, other than real property, is placed in service during the last quarter, all of the property placed in service in the second quarter will be allowed 7.5 months of cost recovery.
(True/False)
4.8/5 (83)
(83) Hans purchased a new passenger automobile on August 17, 2018, for $30,000. During the year the car was used 40% for business and 60% for personal use. Determine his cost recovery deduction for the car for 2018.
(Multiple Choice)
4.7/5 (83)
(83) Norm purchases a new sports utility vehicle (SUV) on October 12, 2018, for $60,000. The SUV has a gross vehicle weight of 6,200 lbs. It is used 100% of the time for business and it is the only business asset acquired by Norm during 2018. Compute the maximum deduction with respect to the SUV for 2018. Norm does not take additional first-year depreciation.
(Essay)
4.9/5 (70)
(70) Diane purchased a factory building on April 15, 1993, for $5,000,000. She sells the factory building on February 2, 2018. Determine the cost recovery deduction for the year of the sale.
(Multiple Choice)
4.7/5 (77)
(77) The § 179 deduction can exceed $1,000,000 in 2018 if the taxpayer had a § 179 amount which exceeded the taxable income limitation in the prior year.
(True/False)
4.9/5 (93)
(93) White Company acquires a new machine (seven-year property) on January 10, 2018, at a cost of $620,000. White makes the election to expense the maximum amount under § 179, and wants to take any additional first-year depreciation allowed. No election is made to use the straight-line method. Determine the total deductions in calculating taxable income related to the machine for 2018 assuming White has taxable income of $800,000.
(Multiple Choice)
4.9/5 (87)
(87) Under the MACRS straight-line election for personalty, only the half-year convention is applicable.
(True/False)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)