



 Chat with AI
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


The amount of startup expenditures that can be deducted in the year incurred is the greater of the actual amount of such expenses or $5,000.
(True/False)
5.0/5  (84)
(84) On August 20, 2018, May placed in service a building for her business. On November 28, 2018, May paid $80,000 for improvements to the building. What is May's cost recovery deduction for the building improvements in 2018?
(Essay)
4.9/5 (69)
(69) Discuss the requirements in order for startup expenditures to be amortized under § 195.
(Essay)
4.9/5 (80)
(80) Martin is a sole proprietor of a sandwich business. On March 4, 2018, Martin purchased and placed in service new seven-year class assets costing $580,000. Martin's business reports taxable income for the year, before any deductions associated with the purchased assets, of $160,000. Martin also received $30,000 of interest income for the year, which is not related to the business. Martin wants his adjusted gross income for the year to be as low as possible. With this objective in mind, determine how Martin should recover the cost of the acquired assets.
(Essay)
4.8/5 (76)
(76) Rod paid $1,950,000 for a new warehouse on April 14, 2018. He sold the warehouse on September 29, 2023.
Determine the cost recovery deduction for 2018 and 2023.
(Essay)
4.8/5 (80)
(80) If startup expenses total $53,000, $51,000 of those costs are amortized over 180 months.
(True/False)
4.9/5 (80)
(80) Nora purchased a new automobile on July 20, 2017, for $29,000. The car was used 60% for business and 40% for personal use. In 2018, the car was used 30% for business and 70% for personal use. Nora elects not to take additional first-year depreciation. Determine the cost recovery recapture and the cost recovery deduction for 2018.
(Essay)
4.9/5 (86)
(86) MACRS does not use salvage value. As a result, if a 7-year MACRS asset is held for 10 years, its adjusted basis will be zero.
(True/False)
4.8/5 (71)
(71) Audra acquires the following new five-year class property in 2018:
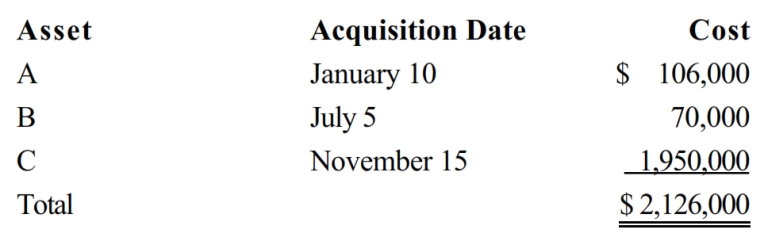 Audra elects § 179 treatment for Asset C. Audra's taxable income from her business would not create a limitation for purposes of the § 179 deduction. Audra does not claim any available additional first-year depreciation deduction. Determine her total cost recovery deduction (including the § 179 deduction) for the year.
 (Essay)
4.9/5 (85)
(85) If an automobile is placed in service in 2018, the limitation for cost recovery in 2020 will be based on the cost recovery limits for the year 2018.
(True/False)
4.9/5 (80)
(80) In 2018, Marci is considering starting a new business. Marci incurs the following costs associated with this venture.
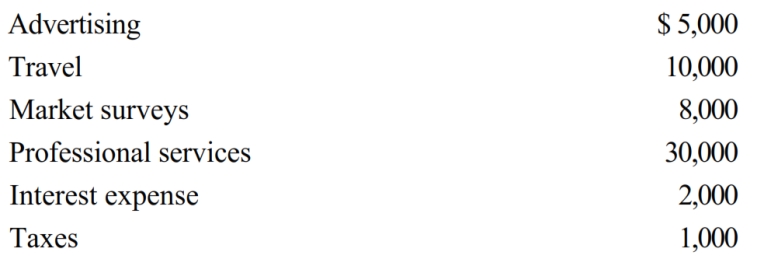 Marci started the new business on January 5, 2019. Determine the deduction for Marci's startup costs for 2018.
 (Essay)
4.8/5 (78)
(78) The cost recovery basis for property converted from personal use to business use may be the fair market value of the property at the time of the conversion.
(True/False)
4.7/5 (79)
(79) Residential rental real estate includes property where 80% or more of the net rental revenues are from nontransient dwelling units.
(True/False)
4.8/5 (79)
(79) Tan Company acquires a new machine (ten-year property) on January 15, 2018, at a cost of $200,000. Tan also acquires another new machine (seven-year property) on November 5, 2018, at a cost of $40,000. No election is made to use the straight-line method. The company does not make the § 179 election and elects to not take additional first-year depreciation. Determine the total deductions in calculating taxable income related to the machines for 2018.
(Multiple Choice)
4.8/5 (84)
(84) Augie purchased one new asset during the year (five-year property) on November 10, 2018, at a cost of $660,000. She would like to use the § 179 election and will also take additional first-year depreciation. The income from the business before the cost recovery deduction and the § 179 deduction was $600,000. Determine the maximum cost recovery deduction available on this asset for 2018.
(Multiple Choice)
4.8/5 (76)
(76) For a new car that is used predominantly in business, the "luxury auto" limit depends on whether the taxpayer takes MACRS or straight-line depreciation.
(True/False)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)