



 Chat with AI
Exam 16: Accounting Periods and Methods

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


Ramon sold land in 2018 with a cost of $80,000 for $200,000. The sales agreement called for a $50,000 down payment and a $50,000 payment plus 8% interest to be received on the first day of each year for the next three years. What would be the consequences of the following (treat each part independently and assume Ramon uses the installment method whenever possible):
a. In 2018, Ramon gave one of the $50,000 installment obligations to a close relative.
b. In 2018, Ramon transferred the installment obligations ($50,000) to his 100% owned corporation.
c. Ramon collected the $50,000 plus $12,000 interest on January 1, 2019, and died on January 2,2019.

Free
(Essay)
4.7/5  (79)
(79) Correct Answer: Verified
a. The gift is a taxable disposition and, thus, Ramon must recognize a $30,000 gain($120,000/$200,000 × $50,000).
b. The transfer to the controlled corporation is not a taxable disposition. The corporation will recognize the gain when it collects the amount due.
c. Death is not a taxable disposition. Ramon's beneficiaries will recognize the gain (as income in respect of a decedent) when the payments are collected. Ramon recognizes a $30,000 gain ($120,000/$200,000 × $50,000) plus $12,000 interest on his final return for 2019.
Todd, a CPA, sold land for $300,000 cash on the date of sale plus a note for $500,000 due in one year. The interest rate on the note was equal to the Federal rate. The fair market value of the note was $400,000. Todd's basis in the land was $80,000.
Free
(Multiple Choice)
4.8/5 (84)
(84) Correct Answer:Verified
VerifiedC
Gold Corporation sold its 40% of the Ruby Corporation common stock. Gold received $10 million in the year of the sale and a note for $15 million, payable in three years with interest at the Federal rate. Gold's basis in the stock was $5 million. Assume that Gold Corporation will report the gain by the installment method where the method is permitted.
Free
(Multiple Choice)
4.8/5 (78)
(78) Correct Answer:Verified
VerifiedB
Generally, deductions for additions to reserves for estimated future costs (e.g., an allowance for estimated warranty costs) are not allowed for Federal income tax purposes because allowing the deduction would:
(Multiple Choice)
4.8/5 (79)
(79) Kathy was a shareholder in Matrix, Inc., when she sold the corporation a commercial building. The building cost $500,000 and the balance in the accumulated depreciation account was $400,000. Matrix, Inc., paid $100,000 in the year of sale and gave Kathy a note for $400,000 plus adequate interest due in 2019.
(Multiple Choice)
4.8/5 (87)
(87) In 2018, Norma sold Zinc, Inc., common stock for $100,000 cash and a note receivable for $900,000. The note was due in 2019 with accrued interest at the Federal rate. Norma's basis in the stock was $250,000. This was Norma's only installment sale transaction. Which of the following statements is correct?
(Multiple Choice)
4.9/5 (76)
(76) Which of the following statements regarding a 52-53 week tax year is not correct?
(Multiple Choice)
4.7/5 (80)
(80) A C corporation provides lawn maintenance services to various businesses and homeowners. The corporation has average annual gross receipts of $7 million. The corporation may use the cash method of accounting.
(True/False)
4.8/5 (89)
(89) Red Corporation and Green Corporation are equal partners in the R & G Partnership. Red Corporation's tax year ends September 30th, and Green Corporation is a calendar year taxpayer. The greatest aggregate deferral of income would occur if the partnership used a calendar year for tax purposes.
(True/False)
4.8/5 (80)
(80) Gold Corporation, Silver Corporation, and Platinum Corporation are equal partners in the GSP Partnership, which was formed on July 1, 2018. Gold and Silver use a calendar tax year, and Platinum's tax year ends June 30. GSP is not a seasonal business.
(Multiple Choice)
4.8/5 (81)
(81) Taylor sold a capital asset on the installment basis and did not charge interest on the deferred payment due in three years.
(Multiple Choice)
4.8/5 (86)
(86) In 2018, Father sold land to Son for $50,000 cash and an installment note for $150,000 due in 2022. Father's basis was $100,000. In 2019, after paying $8,000 interest but nothing on the principal, Son sold the land for $300,000 cash. What gain, if any, must Father recognize in 2019?
(Multiple Choice)
4.9/5 (79)
(79) John sold an apartment building for $600,000. His basis in the building was $360,000 and it was subject to $30,000 of depreciation recapture. John received $150,000 in the year of sale, the buyer assumed John's mortgage payable of $240,000, and the buyer gave John an 8% (the current Federal rate) note of $210,000 due in 5 years. The interest on the note was payable each June 30, beginning in the year following the year of the sale. John incurred $30,000 of selling expenses which he paid in the year of sale. Compute John's installment sales gain that should be reported in the year of sale.
(Essay)
4.8/5 (69)
(69) Laura Corporation changed its tax year-end from July 31st to December 31st in 2018. The income for the period August 1, 2018 through December 31, 2018 was $35,000. The corporate tax rate in the state where the corporation performs all of its business is 5% on the first $50,000 of income and 7% on income above $50,000. Laura's state tax for the short period is $2,033.
(True/False)
4.9/5 (83)
(83) Dr. Stone incorporated her medical practice and elected to use a fiscal year ending September 30. For the fiscal year ending September 30, 2018, the corporation earned $40,000 profits each month, before Dr. Stone's salary and income tax. Dr. Stone received a salary that averaged $30,000 per month. Next year (fiscal year ending September 30, 2019), Dr. Stone expects the average monthly profits before salary and taxes to be $48,000. What is the minimum salary Dr. Stone can receive for the last three months of calendar year 2018 to ensure that the corporation can deduct salary equal to the corporation's before salary income for the fiscal year ending September 30, 2019?
(Essay)
4.9/5 (75)
(75) This year, Yuan started a business selling computer parts both in-store and online. He purchased via credit card, $60,000 of goods during the year. His ending inventory was $9,000. For tax purposes, Yuan adopted the cash method and the treatment of inventory as deductible when purchased per his books. His deduction for inventory for the year is:
(Multiple Choice)
4.7/5 (66)
(66) The taxpayer had consistently used the cash method of accounting even though inventories were a material income- producing factor to its business and average annual gross receipts in the prior-3 year period exceeded $25 million. The taxpayer decided to voluntarily change to the accrual method of accounting. The adjustment to income due to the change was that the correct beginning balances for the year of the change as follows: $600,000 for inventories, $300,000 for accounts receivable, and $120,000 for accounts payable. The adjustment due to the change in accounting method is:
(Multiple Choice)
4.9/5 (77)
(77) Albert is in the 35% marginal tax bracket. He sold a building in the current year for $450,000. Albert received $110,000 cash at closing, the buyer assumed Albert's mortgage for $120,000, and the buyer gave Albert a 6% note for $220,000 due in two years. The Federal rate was 6%. Albert's basis in the building was $180,000 ($500,000 cost -$320,000 accumulated straight-line depreciation). Assuming he did not elect out of the installment method, Albert's § 1231 gain and gain taxed at the 25% rate in the year of sale are what amounts? 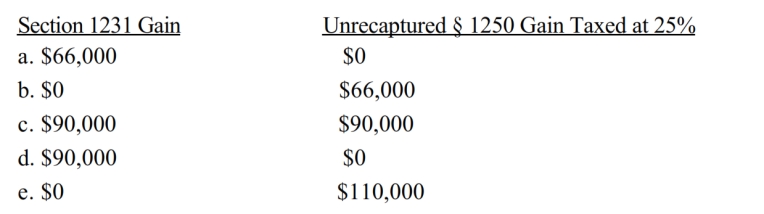
(Short Answer)
4.8/5 (72)
(72) Father sold land to Son for $500,000 in 2018. Father's basis in the land was $100,000. Son paid Father $50,000 and gave Father a note for $450,000 due in 2021. In 2019, Son sold the land for $600,000 cash. The note bore interest at the appropriate Federal rate and both Father and Son held the land as an investment.
(Multiple Choice)
4.8/5 (80)
(80) Yard Corporation, a cash basis taxpayer, received $10,000 from a customer in 2016. In 2016, the customer filed a claim for a refund of the fee. In 2017, Yard refunded the customer $6,000. In 2016, Yard paid $5,000 in estimated state income tax. In May 2017, Yard received a state income tax refund of $2,000 for overpayment of its 2016 income tax. Yard was in the 35% marginal tax bracket in 2016 and in the 15% marginal tax bracket in 2017. What are the tax effects of the 2017 payment to the customer and the collection of the state income taxes overpaid?
(Essay)
4.8/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)