



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law211 Questions
Exam 2: Working with the Tax Law102 Questions
Exam 3: Computing the Tax180 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions113 Questions
Exam 6: Deductions and Losses: In General156 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses94 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion120 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses153 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions104 Questions
Exam 11: Investor Losses130 Questions
Exam 12: Tax Credits and Payments111 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges285 Questions
Exam 14: Property Transactions: Capital Gains and Losses, Section 1231, and Recapture Provisions167 Questions
Exam 15: Taxing Business Income60 Questions
Exam 16: Accounting Periods and Methods88 Questions
Exam 17: Corporations: Introduction and Operating Rules108 Questions
Exam 18: Corporations: Organization and Capital Structure109 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation185 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations71 Questions
Exam 21: Partnerships248 Questions
Exam 22: S Corporations129 Questions
Exam 23: Exempt Entities153 Questions
Exam 24: Multistate Corporate Taxation204 Questions
Exam 25: Taxation of International Transactions146 Questions
Exam 26: Tax Practice and Ethics184 Questions
Exam 27: The Federal Gift and Estate Taxes141 Questions
Exam 28: Income Taxation of Trusts and Estates161 Questions
Select questions type


A state can levy an income tax on a business only if the business was incorporated in the state.
(True/False)
5.0/5  (93)
(93) The sale of groceries to an individual probably is exempt from sales/use tax under the _________________________ rule.
(Short Answer)
4.8/5 (73)
(73) Identify some state/local income tax issues facing pass-through entities such as S corporations, partnerships, and LLCs.
(Essay)
4.9/5 (99)
(99) José Corporation realized $900,000 taxable income from the sales of its products in States X and Z. José's activities in both states establish nexus for income tax purposes. José's sales, payroll, and property among the states include the following. 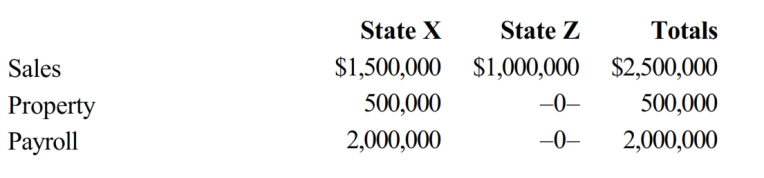 Z utilizes a double-weighted sales factor in its three-factor apportionment formula. How much of José's taxable income is apportioned to Z?
 (Multiple Choice)
4.9/5 (84)
(84) For most taxpayers, which of the traditional apportionment factors yields the greatest opportunities for tax reduction?
(Multiple Choice)
4.9/5 (85)
(85) List at least five items that are included in the payroll factor of a typical state. Consider all forms of compensation that an employee might receive. Apply the general UDITPA rules.
(Essay)
4.9/5 (86)
(86) José Corporation realized $900,000 taxable income from the sales of its products in States X and Z. José's activities in both states establish nexus for income tax purposes. José's sales, payroll, and property among the states include the following. 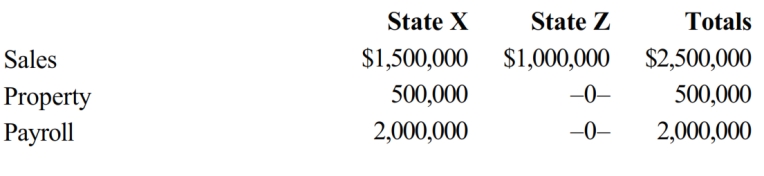 X utilizes an equally weighted three-factor apportionment formula. How much of José's taxable income is apportioned to X?
 (Multiple Choice)
4.9/5 (69)
(69) A unitary group of entities files a combined return that includes all of the affiliates' income and apportionment data.
(True/False)
4.7/5 (81)
(81) All of the U.S. states use an apportionment formula based on the sales, property, and payroll factors.
(True/False)
4.8/5 (88)
(88) State Q wants to increase its income tax collections, but politically it would be unwise to raise taxes on in-state individuals or businesses. Q currently follows all UDITPA rules and employs an equally weighted three-factor apportionment formula. Q allocates nonbusiness income amounts.
Identify some changes to the income tax apportionment formula that would shift the scheduled income tax increases to out-of-state businesses.
(Essay)
4.8/5 (73)
(73) Match each of the following items with the appropriate description, in determining whether sales/use tax typically must be collected.
a. Taxable
b. Not taxable
-A garment purchased by a self-employed actress.
(Short Answer)
4.9/5 (69)
(69) Dott Corporation generated $300,000 of state taxable income from selling its mapping software in States A and B.
For the taxable year, the corporation's activities within the two states were as follows.
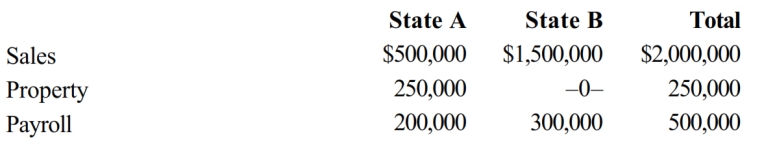 Dott has determined that it is subject to tax in both A and B. Both states utilize a three-factor apportionment formula which equally weights sales, property, and payroll. The rates of corporate income tax imposed in A and B are 7% and 10%, respectively. Determine Dott's state income tax liability.
 (Essay)
4.8/5 (84)
(84) Sylvia spends time working at the offices of her employer as a consultant to clients who are located in three different U.S. states. To which state(s)' payroll factor(s) is Sylvia's compensation assigned? Apply the general UDITPA rules.
(Essay)
5.0/5 (72)
(72) A service engineer spends 80% of her time maintaining the employer's productive business property, and 20% maintaining the employer's nonbusiness rental properties. This year, her compensation totaled $90,000. The payroll factor assigns $90,000 to the state in which the employer is based.
(True/False)
4.7/5 (75)
(75) What is the significance of the term nexus when discussing state income taxation?
(Essay)
4.9/5 (69)
(69) Parent Corporation owns all of the stock of Junior Corporation, a Delaware passive investment company. Parent operates strictly in nonunitary State B, which levies a 9% income tax. This year, Junior earned $200,000 of portfolio interest income and paid a $150,000 dividend to Parent. In which state(s) will the interest income create an income tax liability?
(Multiple Choice)
4.9/5 (89)
(89) Although apportionment formulas vary among jurisdictions, most states use the same three factors in the formula.
The factors are ____________________, ____________________, and ____________________.
(Short Answer)
5.0/5 (92)
(92) Which of the following is not immune from state income taxation, even if P.L. 86-272 is in effect?
(Multiple Choice)
4.8/5 (73)
(73) General Corporation is taxable in a number of states. This year, General made a $100,000 sale from its A headquarters to a customer in B. This activity is not sufficient for General to create nexus with B. State B applies a throwback rule, but State A does not. In which state(s) will the sale be included in the sales factor numerator?
(Multiple Choice)
4.7/5 (89)
(89) Adams Corporation owns and operates two manufacturing facilities, one in State X and the other in State Y. Due to a temporary decline in the corporation's sales, Adams has rented 20% of its Y facility to an unaffiliated corporation. Adams generated $1,000,000 net rental income and $5,000,000 income from manufacturing. Adams is incorporated in Y. For X and Y purposes, rental income is classified as allocable nonbusiness income. By applying the statutes of each state, Adams determined that its apportionment factors are .65 for X and .35 for Y.
Adams's income attributed to X is:
(Multiple Choice)
4.9/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)