



 Chat with AI
Exam 22: Long-Run Economic Growth: Sources and Policies

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


Increased foreign direct investment in India has contributed to its recent economic growth.
(True/False)
4.7/5  (69)
(69) Table 22-6
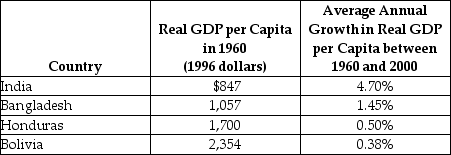 -Refer to Table 22-6. Consider the statistics in the table above in describing the developing countries. Are these consistent with the economic growth model? Briefly explain.
 (Essay)
4.9/5 (84)
(84) Figure 22-4  -Refer to Figure 22-4. Which of the following combinations of points illustrates changes in the Soviet Union's economy from 1950 to 1980?
 (Multiple Choice)
4.9/5 (76)
(76) By offering more generous unemployment insurance programs, European countries can expect
(Multiple Choice)
4.8/5 (74)
(74) Table 22-3
 -Growth in the United States from 1800 to 1900 can be characterized as
 (Multiple Choice)
4.9/5 (73)
(73) Figure 22-3  -Refer to Figure 22-3. Technological change is shown in the figure above by the movement from
 (Multiple Choice)
4.7/5 (82)
(82) Knowledge capital is ________ in production and ________. As a result, firms ________ free ride.
(Multiple Choice)
4.7/5 (80)
(80) According to a study by economists Raymond Fisman and Edward Miguel, as the level of corruption in a country increases,
(Multiple Choice)
4.9/5 (91)
(91) Disease, poor nutrition, and substandard health care in developing nations can reduce growth in an economy by
(Multiple Choice)
4.8/5 (85)
(85) The opportunity cost of being unemployed tends to be the highest in which of the following countries?
(Multiple Choice)
4.9/5 (67)
(67) For how long does a patent give a firm the exclusive legal right to a product?
(Multiple Choice)
4.8/5 (80)
(80) Figure 22-1  -Refer to Figure 22-1. Technological change is illustrated in the per-worker production function in the figure above by a movement from
 (Multiple Choice)
4.7/5 (79)
(79) High-income countries have ________ and ________ as compared to developing countries.
(Multiple Choice)
4.8/5 (75)
(75) Suggest two policies the government could pursue to help increase the accumulation of knowledge.
(Essay)
4.9/5 (74)
(74) In a small Asian country, it is estimated that changing the level of capital from $8 million to $12 million will increase real GDP from $4 million to $6 million. What level of GDP would you expect the economy to be able to reach if spending on capital continued to rise to $16 million, assuming no technological change and no change in the hours of work?
(Multiple Choice)
4.9/5 (82)
(82) Explain how advances in technology are critical to sustaining economic growth, even if capital per hour worked is consistently increasing. Provide a graph of a per-worker production function to support your answer.
(Essay)
4.8/5 (80)
(80) Robert Lucas argues that there are ________ returns to human capital, and these productivity increases are not completely captured by individuals as they decide how much education to purchase. As a result, the market produces ________ education and training.
(Multiple Choice)
5.0/5 (82)
(82) The per-worker production function shows the relationship between ________ per hour worked and ________ per hour worked, holding ________ constant.
(Multiple Choice)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)