



 Chat with AI
Exam 22: Long-Run Economic Growth: Sources and Policies

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


The U.S. economy has seen a faster increase in productivity since the mid-1990s as compared to the economies of many Western European countries. Which of the following explains this?
(Multiple Choice)
4.9/5  (76)
(76) According to Nobel laureate Douglass North, one reason why the Industrial Revolution occurred in England before many other countries was because the king in England consistently maintained control over the court system and the government.
(True/False)
4.8/5 (64)
(64) Because of diminishing returns, an economy can continue to increase real GDP per hour worked only if
(Multiple Choice)
4.7/5 (94)
(94) Table 22-4
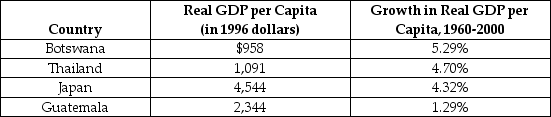 -Refer to Table 22-4. In the table above, which countries are consistent with the predictions of the economic growth model?
 (Multiple Choice)
4.8/5 (80)
(80) Empirical evidence from 1960 to 2010 shows that convergence in economic growth is occurring in which of the following cases?
(Multiple Choice)
5.0/5 (78)
(78) The Soviet Union consistently increased the amount of capital available to its workers, but found that increases in capital resulted in progressively smaller and smaller increases in GDP per worker. This phenomenon is referred to as
(Multiple Choice)
4.8/5 (77)
(77) In the long run, ________ differences in economic growth rates result in ________ differences in GDP per capita.
(Multiple Choice)
4.8/5 (72)
(72) An increase in ________ shifts the production function ________, and makes it possible to produce a higher level of GDP with ________ capital per hour worked.
(Multiple Choice)
4.7/5 (77)
(77) Foreign direct investment occurs when a Chinese corporation
(Multiple Choice)
5.0/5 (61)
(61) The easiest way for a country to obtain access to technology is through
(Multiple Choice)
4.8/5 (76)
(76) Growth in real GDP per capita for the world economy was greatest during
(Multiple Choice)
5.0/5 (85)
(85) Explain how market economies are generally better able to achieve technological progress than are centrally planned economies.
(Essay)
4.9/5 (87)
(87) The labor productivity slowdown in the United States in the 1970s was due to declining quality of education in the United States, because no other industrialized country experienced the same labor productivity slowdown at the same time.
(True/False)
4.9/5 (69)
(69) Which of the following accurately describes growth rates in the United States from 1900 to the present?
(Multiple Choice)
4.9/5 (88)
(88) In a small European country, it is estimated that changing the level of capital from $8 million to $10 million will increase real GDP from $2 million to $3 million. If the number of hours worked in the labor force does not change, what does this information tell you about the slope of the per-worker production function in this range?
(Multiple Choice)
4.9/5 (71)
(71) The owner of a firm wants some advice on how to increase productivity. Suggest three ways the entrepreneur could increase labor productivity through improving technology.
(Essay)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)