



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


A taxpayer wishing to reduce the negative tax effects of the application of the unitary theory might:
(Multiple Choice)
4.8/5  (82)
(82) The individual seller of a used auto should collect and remit sales tax to the state.
(True/False)
4.8/5 (68)
(68) A few states assess a state-level tax on an S corporation that operates in the state.
(True/False)
4.9/5 (81)
(81) Bert Corporation, a calendar-year taxpayer, owns property in States M and O.Both M and O require that the average value of assets be included in the property factor.M requires that the property be valued at its historical cost, and O requires that the property be included in the property factor at its net depreciated book value. 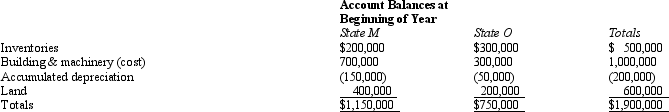
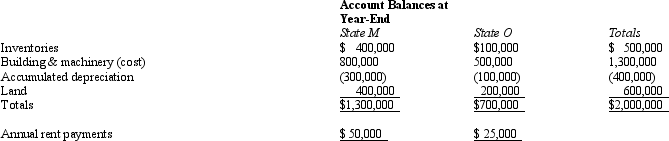 Bert's M property factor is:
 (Multiple Choice)
4.8/5 (75)
(75) All of the U.S.states have adopted a tax based on net taxable income.
(True/False)
4.8/5 (82)
(82) S corporations flow-through income amounts to its shareholders, and most states require a withholding of shareholder taxes on the allocated amounts.
(True/False)
4.8/5 (71)
(71) In unitary states, a(n) ____________________ provision permits a multinational corporation to elect to limit the reach of the state's taxing jurisdiction to activities occurring within the boundaries of the United States.
(Short Answer)
4.9/5 (79)
(79) Norman Corporation owns and operates two manufacturing facilities, one in State X and the other in State Y.Due to a temporary decline in the corporation's sales, Norman has rented 20% of its Y facility to an unaffiliated corporation.Norman generated $1,000,000 net rental income and $2,000,000 income from manufacturing. Norman is incorporated in Y. For X and Y purposes, rental income is classified as allocable nonbusiness income.By applying the statutes of each state, Norman determined that its apportionment factors are .65 for X and .35 for Y.
Norman's income attributed to X is:
(Multiple Choice)
4.7/5 (91)
(91) Match each of the following events to its likely effect on WillCo's various apportionment factors. WillCo is based in Q and has customers in Q, R, and S. To this point, WillCo has not established nexus with S.More than one choice may be correct.
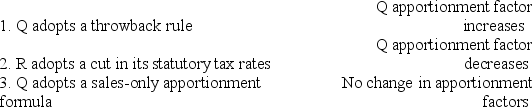
(Essay)
4.9/5 (68)
(68) Typically, the state's payroll factor ____________________ (does/does not) include the fringe benefits provided to its sales force.
(Short Answer)
4.8/5 (75)
(75) You are preparing to make a presentation to a client who has some familiarity with state income tax rules. At a general level, list for the client the principles of multistate tax planning.
(Essay)
4.9/5 (81)
(81) Almost all of the states assess some form of consumer-level sales/use tax.
(True/False)
4.9/5 (71)
(71) The property factor includes land and buildings used for business purposes.
(True/False)
4.8/5 (81)
(81) José Corporation realized $600,000 taxable income from the sales of its products in States X and Z.José's activities in both states establish nexus for income tax purposes.José's sales, payroll, and property among the states include the following.  X utilizes an equally weighted three-factor apportionment formula.How much of José's taxable income is apportioned to X?
 (Multiple Choice)
4.7/5 (73)
(73) The typical state sales/use tax falls on sales of both real and personal property.
(True/False)
4.8/5 (84)
(84) Most states begin the computation of taxable income with an amount from the Federal income tax return.
(True/False)
4.9/5 (88)
(88) Judy, a regional sales manager, has her office in State X.Her region includes several states, as indicated in the sales report below.Determine how much of Judy's $200,000 compensation is assigned to the payroll factor of State X. 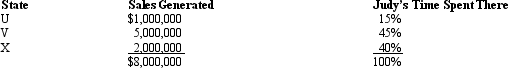
(Multiple Choice)
4.9/5 (77)
(77) List which items are included in the payroll factor of a state. Consider all forms of compensation that an employee might receive. Apply the general UDITPA rules.
(Essay)
4.8/5 (75)
(75) Bulky Company sold an asset on the first day of the tax year for $500,000.Bulky's Federal tax basis for the asset was $300,000.Because of differences in cost recovery schedules, the state regular-tax basis in the asset was $375,000.What adjustment, if any, should be made to Bulky's Federal taxable income in determining the correct taxable income for the typical state?
(Multiple Choice)
4.8/5 (75)
(75) Troy, an S corporation, is subject to tax only in State
A. On Schedule K of its Federal Form 1120S, Troy reported ordinary income of $2,000,000 from its business, municipal bond interest of $150,000, taxable interest of $150,000, and charitable contributions of $300,000.A does not recognize S status, but it does follow the Federal provisions with respect to the determination of taxable income for a corporation.Determine Troy's A taxable income.
(Essay)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)