



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


A state wants to increase its income tax collections, but politically it would be unwise to raise taxes on in-state individuals or businesses. Identify some changes to the income tax apportionment formula that would shift the scheduled income tax increases to out-of-state businesses.
(Essay)
4.8/5  (81)
(81) Under P.L.86-272, which of the following transactions by itself would create nexus with a state?
(Multiple Choice)
5.0/5 (70)
(70) If a state follows Federal income tax rules, the state's tax compliance and enforcement become easier to accomplish.
(True/False)
4.7/5 (83)
(83) 
Determine Bowl's sales factors for States K, M, and N.
Bowl Corporation's manufacturing facility, distribution center, and retail store are located in State K.Bowl sells its products to residents located in States K, M, and N.
Sales to residents of K are conducted through a retail store.Sales to residents of M are obtained by Bowl's sales representative, who has the authority to accept and approve sales orders.Residents of N can purchase Bowl's product only if they place an order online and arrange to take delivery of the product at Bowl's shipping dock.Bowl's sales were as follows.
 Bowl's activities within the three states are limited to those described above.All of the states have adopted a throwback provision and utilize a three-factor apportionment formula under which sales, property, and payroll are equally weighted.K sources dock sales to the destination state.
 (Essay)
4.7/5 (69)
(69) Double weighting the sales factor effectively increases the tax burden on taxpayers based in the state, such as corporations with in-state headquarters.
(True/False)
5.0/5 (77)
(77) A state can levy an income tax on a business only if the business was incorporated in the state.
(True/False)
4.9/5 (65)
(65) In most states, a taxpayer's income is apportioned on the basis of a formula measuring the extent of business contact, and allocated according to the location of property owned or used.
(True/False)
4.8/5 (98)
(98) Hermann Corporation is based in State A (corporate income tax rate 10%).It sells its goods to customers in both A and State B (corporate income tax rate 4%). Hermann's state taxable income for the year is $1 million, 30% of which relates to B customers. Hermann's level of activities in B is insufficient to create nexus there, but A has adopted a throwback rule as to multistate sales. Would Hermann reduce its total state income tax liability by creating nexus with B, say by allowing its sales force to make credit decisions? Elaborate.
(Essay)
4.8/5 (83)
(83) In international taxation, we discuss income sourcing rules and the permanent establishment doctrine. In multistate taxation, an analogous term might be the "ultimate destination concept." Define this term, and identify at least two of the most important exceptions to the general rule.
(Essay)
4.9/5 (78)
(78) Typically exempt from the sales/use tax base is the purchase of prescription medicines by an individual.
(True/False)
4.9/5 (81)
(81) Cruz Corporation owns manufacturing facilities in States A, B, and C. A uses a three-factor apportionment formula under which the sales, property and payroll factors are equally weighted.B uses a three-factor apportionment formula under which sales are double-weighted.C employs a single-factor apportionment factor, based solely on sales.
Cruz's operations generated $1,000,000 of apportionable income, and its sales and payroll activity and average property owned in each of the three states is as follows.
 Cruz's apportionable income assigned to C is:
 (Multiple Choice)
4.7/5 (82)
(82) For most taxpayers, which of the traditional apportionment factors yields the greatest opportunities for tax reduction?
(Multiple Choice)
4.8/5 (78)
(78) ____________________ describe(s) the degree of business activity that must be present before a taxing jurisdiction has the right to impose a tax on an entity's income.
(Short Answer)
4.7/5 (83)
(83) A(n) ____________________ business operates its separate companies as a whole.It cannot be segregated into independently operating divisions or branches.
(Short Answer)
4.9/5 (77)
(77) Mercy Corporation, headquartered in F, sells wireless computer devices, including keyboards and bar code readers. Mercy's degree of operations is sufficient to establish nexus only in E and
F.Determine its sales factor in those states.
State E applies a throwback rule to sales, while State F does not.State G has not adopted an income tax to date.Mercy reported the following sales for the year.All of the goods were shipped from Mercy's F manufacturing facilities.
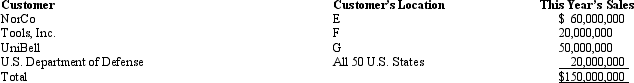 Because F has not adopted a throwback rule, the sales to customers in G and to the U.S.government are not included in either state's sales factor.Mercy creates $70 million in "nowhere sales."
E Sales factor = $60 million/$150 million = 40.00%
F Sales factor = $20 million/$150 million = 13.33%
Because F has not adopted a throwback rule, the sales to customers in G and to the U.S.government are not included in either state's sales factor.Mercy creates $70 million in "nowhere sales."
E Sales factor = $60 million/$150 million = 40.00%
F Sales factor = $20 million/$150 million = 13.33% (Essay)
4.9/5 (76)
(76) Compost Corporation has finished its computation of Federal taxable income. In State Q, the derivation of state corporate taxable income starts with the Federal amount and makes a number of modifications. List at least five such modifications that Compost is likely to encounter.
(Essay)
4.8/5 (83)
(83) Most of the U.S.states have adopted an alternative minimum tax, similar to the Federal system.
(True/False)
4.7/5 (73)
(73) Kurt Corporation realized $900,000 taxable income from the sales of its products in States X and Z.Kurt's activities establish nexus for income tax purposes in both states.Kurt's sales, payroll, and property among the states include the following.  Z utilizes an equally weighted three-factor apportionment formula.Kurt is incorporated in X.How much of Kurt's taxable income is apportioned to Z?
 (Multiple Choice)
4.8/5 (78)
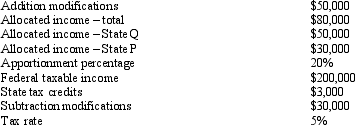
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)