



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


In most states, medical services are exempt from the sales/use tax base.

Free
(True/False)
4.9/5  (76)
(76) Correct Answer: Verified
True
Slattery Corporation sells widgets in two states. State A levies a 9% effective tax rate, and State B levies a 4% rate. A and B have adopted sales-factor-only apportionment formulas. To reduce overall multistate income tax liabilities, Slattery should:
Free
(Multiple Choice)
4.8/5 (90)
(90) Correct Answer:Verified
VerifiedA
In determining taxable income for state income tax purposes, the state NOL deduction typically constitutes a(n) ____________________ modification.
Free
(Short Answer)
4.8/5 (84)
(84) Correct Answer:Verified
Verifiedsubtraction
Your supervisor has shifted your responsibilities from the Federal corporate income tax to a multistate corporate income tax practice. In what areas might your Federal income tax knowledge also be applicable in your new assignment?
(Essay)
4.8/5 (73)
(73) General Corporation is taxable in a number of states. This year, General made a $100,000 sale from its A headquarters to a customer in B. This activity is not sufficient for General to create nexus with B. State B applies a throwback rule, but State A does not. In which state(s) will the sale be included in the sales factor numerator?
(Multiple Choice)
4.9/5 (88)
(88) Several states allow the S corporation to file a(n) ____________________ income tax return, usually in the form of a state-by-state spreadsheet, on behalf of its out-of-state shareholders.
or
(Short Answer)
4.8/5 (64)
(64) Hopper Corporation's property holdings in State E are as follows. 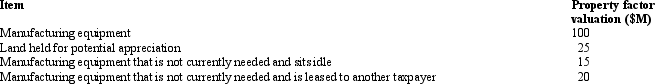 Compute the numerator of Hopper's E property factor.
 (Multiple Choice)
4.7/5 (81)
(81) A ____________________ tax is designed to complement the local sales tax structure, to prevent the consumer from making purchases in a lower-tax state or online, and then bringing the asset into the state.
(Short Answer)
4.8/5 (86)
(86) Federal taxable income is used as the starting point in computing the state's income tax base, but numerous state adjustments or modifications generally are required to:
(Multiple Choice)
5.0/5 (75)
(75) Perez Corporation is subject to tax only in State A.Perez generated the following income and deductions.  Federal taxable income is the starting point in computing A taxable income.State income taxes are not deductible for A tax purposes.Perez's A taxable income is:
 (Multiple Choice)
4.9/5 (77)
(77) In determining state taxable income, all of the following are adjustments to Federal income except:
(Multiple Choice)
4.7/5 (86)
(86) In determining taxable income for state income tax purposes, the Federal NOL deduction typically constitutes a(n) ____________________ modification.
(Short Answer)
4.7/5 (77)
(77) Most states' consumer sales taxes apply directly to the final purchaser of the taxable asset, who then remits the tax to the state treasury.
(True/False)
4.9/5 (74)
(74) The typical local property tax falls on both an investor's real estate and her stock portfolio.
(True/False)
4.8/5 (87)
(87) José Corporation realized $600,000 taxable income from the sales of its products in States X and Z.José's activities in both states establish nexus for income tax purposes.José's sales, payroll, and property among the states include the following.  Z utilizes a double-weighted sales factor in its three-factor apportionment formula.How much of José's taxable income is apportioned to Z?
 (Multiple Choice)
4.8/5 (70)
(70) P.L.86-272 ____________________ (does/does not) create nexus when the seller runs a booth with inventory samples, at a one-week trade show in the state.
(Short Answer)
4.9/5 (74)
(74) Dott Corporation generated $300,000 of state taxable income from selling its mapping software in States A and
B.Both states utilize a three-factor apportionment formula which equally weights sales, property, and payroll.The rates of corporate income tax imposed in A and B are 7% and 10%, respectively.Determine Dott's state income tax liability.
B.For the taxable year, the corporation's activities within the two states were as follows.
 Dott has determined that it is subject to tax in both A and
 (Essay)
5.0/5 (86)
(86) Overall tax liabilities typically ____________________ (increase/decrease) if the members of a unitary group begin to include affiliates that generate net operating losses.
(Short Answer)
4.9/5 (81)
(81) The use tax is designed to complement the sales tax.A use tax typically covers purchases made out of state and brought into the jurisdiction.
(True/False)
4.7/5 (90)
(90) In most states, Federal S corporations must make a separate state-level election of the flow-through status.
(True/False)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)