



 Chat with AI
Exam 22: S: Corporations


Estela, Inc., a calendar year S corporation, incurred the following items in 2012.
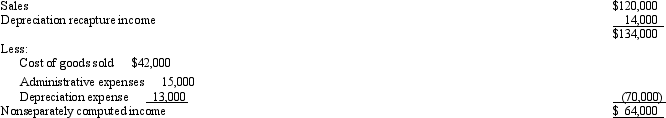
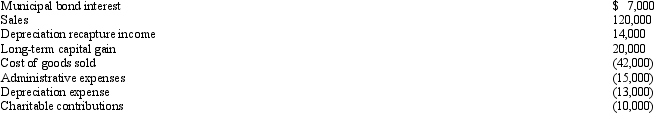 Calculate Estela's nonseparately computed income.
 (75)
 Verified
The Schedule M-3 is the same for a C corporation and an S corporation.
(81) VerifiedFalse
Compare the distribution of property rules for an S corporation with the corresponding partnership rules.
(83) VerifiedThe major difference involves distributions of appreciated property.Under the S corporation rules, realized gain on distributed appreciated property is recognized to the corporation, which passes through to the shareholders with no corporate-level tax (other than the built-in gains tax).The gain increases the shareholder's stock basis.A realized loss, however, is not recognized for an S corporation distribution.The shareholder takes a market value basis in the property.
On the distribution, the shareholder's stock basis is reduced by the fair market value of the property (but not below zero).
No gain or loss is recognized to a partnership or partners on the distribution of property.Basis to the partner in the asset is the lesser of the partner's basis in the partnership or the entity's basis in the asset.
In the case of a complete termination of an S corporation interest, a ____________________ tax year may occur.
(84) On January 2, 2011, David loans his S corporation $10,000, and by the end of 2011 David's stock basis is zero and the basis in his note has been reduced to $8,000.During 2012, the company's operating income is $10,000.The company also makes distributions to David of $11,000.David reports a(n):
(73) Several individuals acquire assets on behalf of Skip Corporation on May 28, 2012, purchased assets on June 3, 2012, and began business on June 11, 2012.They subscribe to shares of stock, file articles of incorporation for Skip, and become shareholders on June 21, 2012.The S election must be filed no later than 2 1/2 months after:
(92) If an S corporation excludes cancellation of debt (COD) income from gross income, the excluded amount is applied to _________________ S corporation tax attributes.
(70) Realized gain is recognized by an S corporation on its distribution of ____________________ property.
(79) Which equity arrangement cannot be used by an S corporation?
(73) Which of these tax provisions does not apply to an S corporation?
(76) Non-separately computed loss ____________________ a S shareholder's stock basis.
(79) An S corporation may not have a ____________________ alien shareholder.
(84) Charitable contributions are subject to a 10% limitation at the S corporation level.
(76) Compensation for services rendered to an S corporation is subject to FICA taxes.
(87) An S shareholder's basis is increased by stock purchases and capital contributions.
(80) S corporation status allows shareholders to realize tax benefits from corporate losses ____________________.
(80) Any losses that are suspended under the at-risk rules are carried forward and are available during an S corporation's post-termination period.
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)