



 Chat with AI
Exam 22: S: Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


A per-day, per-share allocation of flow-through S corporation items must be used, unless the shareholder disposes of the entire interest in the entity.
(True/False)
4.8/5  (94)
(94) An S corporation reports a recognized built-in gain of $110,000 and taxable income of $98,000.The company has an $8,000 NOL carryforward from a C corporation year, and a $7,000 business credit carryforward from a C corporation year.The built-in gains tax liability is:
(Multiple Choice)
4.7/5 (75)
(75) Which, if any, of the following items has no effect on the stock basis of an S corporation shareholder?
(Multiple Choice)
4.9/5 (74)
(74) The corporate ____________________ ____________________ tax is avoided in an S corporation.
(Short Answer)
4.9/5 (77)
(77) Which transaction affects the Other Adjustments Account on an S corporation's Schedule M-2?
(Multiple Choice)
4.9/5 (77)
(77) An S corporation does not recognize a loss when distributing assets that are worth less than their basis.
(True/False)
4.8/5 (72)
(72) Stock basis first is increased by income items, then ____________________ by distributions, and finally decreased by ____________________.
(Short Answer)
4.8/5 (85)
(85) Post-termination distributions by a former S corporation that are charged against ____________________ do not get tax-free treatment.
(Short Answer)
4.9/5 (83)
(83) Depletion in excess of basis in property causes a(n) ____________________ adjustment to an S shareholder's basis.
or
(Short Answer)
4.9/5 (69)
(69) Form 1120S provides a shareholder's computation of his or her stock basis.
(True/False)
4.8/5 (81)
(81) A calendar year C corporation reports a $41,000 NOL in 2011, but it elects S status for 2012 and generates an NOL of $30,000 in that year. At all times during 2012, the stock of the corporation was owned by the same 10 shareholders, each of whom owned 10% of the stock. Kris, one of the 10 shareholders, holds an S stock basis of $2,300 at the beginning of 2012. How much of the 2012 loss, if any, is deductible by Kris?
(Multiple Choice)
4.7/5 (79)
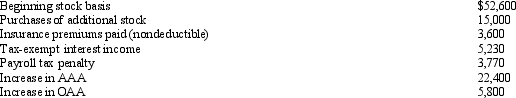
(79) You are a 60% owner of an S corporation. Calculate your ending stock basis, based upon these facts.
(Essay)
4.9/5 (83)
(83) For a new corporation, a premature S election may not be effective.
(True/False)
4.8/5 (94)
(94) Discuss the two methods of allocating tax-related items to S corporation shareholders.
(Essay)
4.8/5 (81)
(81) Which transaction affects the Other Adjustments Account on an S corporation's Schedule M-2?
(Multiple Choice)
4.8/5 (67)
(67) An S corporation recognizes a ____________________ on any distribution of appreciated property.
(Short Answer)
5.0/5 (75)
(75) A distribution of cash or other property by an S corporation to shareholders that does not exceed the balance of AAA during a one-year period following an S election termination receives special capital gain treatment.
(True/False)
4.7/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)