



 Chat with AI
Exam 11: Investor Losses


In 2012, Emily invests $100,000 in a limited partnership that is not a passive activity.During 2012, her share of the partnership loss is $70,000.In 2013, her share of the partnership loss is $50,000.How much can Emily deduct in 2012 and 2013?

 (88)
 Verified
Although the passive loss rules do not apply, the at-risk rules limit Emily's deductions.She can deduct $70,000 in 2012 and her at-risk amount will be reduced to $30,000 ($100,000 - $70,000 deducted).She will be limited to a $30,000 deduction in 2013 unless she increases her amount at risk.For example, if Emily invests an additional $20,000 in 2012, her at-risk amount would be $50,000 ($30,000 balance + $20,000 additional investment), and she would be able to deduct the entire $50,000 loss in 2013.
Identify the types of income that are classified as investment income. Discuss the flexibility that a taxpayer has with respect to certain types of income that may potentially be considered investment income.
(81) VerifiedInvestment income is gross income from interest, dividends (in certain cases), annuities, and royalties not derived in the ordinary course of a trade or business. Passive activity income and income from a real estate activity in which the taxpayer actively participates are not included as investment income.
The taxpayer may elect to treat net capital gain and qualified dividends as investment income. Net capital gain includes gain attributable to the dispositions of property producing investment income or held for investment purposes. Qualified dividends are dividends that are taxed at the same marginal rate that is applicable to a net capital gain. If the taxpayer elects to treat net capital gain and qualified dividend income as investment income, they may not be taxed using the preferential capital gains rates.
During the year, James performs the following personal services in three separate activities: 800 hours as a CPA in his tax practice, 400 hours in a real estate development business (in which he is not a material participant), and 600 hours in an apartment leasing operation.He expects that losses will be realized from the two real estate ventures while his tax practice will show a profit.James files a joint return with his wife whose salary is $200,000.What is the character of the income and losses generated by these activities?
(76) VerifiedJames is a material participant in the tax practice but not in the real estate development business.This causes the real estate development activity to be classified as passive.Further, the apartment leasing operation is a passive activity.It is a rental activity and does not qualify for the real estate rental exception given the taxpayers' level of income.Therefore, the income from the tax practice may not be offset by either the losses from the real estate development business or the apartment leasing operation.
James does not qualify for the exception for real estate professionals because he has not spent more than half of his personal services in real estate trades or businesses in which he materially participates.
Stuart is the sole owner and a material participant in a business in which he has $50,000 at risk.If the business incurs a loss of $80,000 from operations, Stuart can deduct the full amount.
(82) Sarah, who owns a 50% interest in a grocery store, was a material participant in the activity for the last 25 years.She retired from the grocery store at the end of last year and will not participate in the activity in the future.However, she continues to be a material participant in an office supply store in which she is a 50% partner.The operations of the grocery store resulted in a loss for the current year and Sarah's share of the loss is $40,000.Sarah's share of the income from the office supply store is $75,000.She does not own interests in any other activities.
(66) Jon owns an apartment building in which he is a material participant and a computer consulting business.Of the 2,000 hours he spends on these activities during the year, 55% of the time is spent operating the apartment building and 45% of the time is spent in the computer consulting business.
(85) Hugh has four passive activities which generate the following income and losses in the current year.
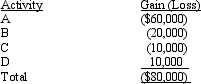 How much of the $80,000 net passive loss can Hugh deduct this year? Calculate the suspended losses (by activity).
 (80) Vail owns interests in a beauty salon, a natural foods store, and a tanning salon. Several full-time employees work at each of the enterprises. As of the end of November of the current year, Vail has worked 180 hours in the beauty salon, 220 hours at the natural foods store, and 80 hours at the tanning salon. These three ventures collectively will produce income. Vail also owns one other passive activity that is producing a loss (a limited partnership in which she has reported no participation). How should Vail plan her activities for the remainder of the year?
(71) Sam, who earns a salary of $400,000, invested $160,000 for a 40% working interest in an oil and gas limited partnership (not a passive activity) last year.Through the use of $1,600,000 of nonrecourse financing, the partnership acquired assets worth $2 million.Depreciation, interest, and other deductions related to the activity resulted in a loss in the partnership's initial year of $300,000, of which Sam's share was $120,000.Sam's share of loss from the partnership is $60,000 in the current year.How much of the loss from the partnership can Sam deduct in each year?
(96) Ahmad owns four activities. He participated for 120 hours in Activity A, 150 hours in Activity B, 140 hours in Activity C, and 100 hours in Activity D. Which of the following statements is correct?
(80) Eric makes an installment sale of a passive activity having suspended losses of $40,000.He collects 25% of the sales price in the current year, and will collect 25% in each of the next three years.Eric can deduct $10,000 of the passive loss this year.
(73) Emily earns a salary of $150,000, and invests $60,000 for a 20% interest in a passive activity. Operations of the activity result in a loss of $400,000, of which Emily's share is $80,000. How is her loss characterized?
(83) Orange Corporation, a closely held (non-personal service) C corporation, earns active income of $300,000 in the current year.The corporation also receives $35,000 in dividends and incurs a loss of $50,000 from an investment in a passive activity.What is Orange's income for the year after considering the passive investment?
(69) Sarah purchased for $100,000 a 10% interest in a business venture that is not subject to the passive activity rules.During the first year, her share of the entity's loss was $120,000.At the beginning of the second year, the entity obtained $800,000 of recourse financing.During the second year, Sarah withdrew cash of $20,000, and her share of the entity's loss was $25,000.Calculate the amount of loss that Sarah may claim in each of the two years and determine her at-risk amount at the end of each year.
(88) Joe participates 95 hours in an activity, while an employee participates 5 hours.Joe has materially participated in the activity.
(81) Judy owns a 20% interest in a partnership (not real estate) in which her at-risk amount was $35,000 at the beginning of the year.The partnership borrowed $50,000 on a recourse note and made a $40,000 profit during the year.Her at-risk amount at the end of the year is $43,000.
(74) Judy incurred $58,500 of interest expense this year related to her investments.Her investment income includes $15,000 of interest, $9,000 of qualified dividends, and a $22,500 net capital gain on the sale of securities.The maximum amount of Judy's investment interest expense deduction for the year is:
(86) Charles owns a business with two separate departments. Department A produces $100,000 of income and Department B incurs a $60,000 loss. Charles participates for 550 hours in Department A and 100 hours in Department B. He has full-time employees in both departments.
(85) Gail exchanges passive Activity A, which has suspended losses of $15,000, for passive Activity B in a nontaxable exchange.The new owner of passive Activity A can offset the $15,000 suspended losses against passive income in the future.
(84) Services performed by an employee are treated as being related to a real estate trade or business if the employee performing the services has more than a 5% ownership interest in the employer.
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)