



 Chat with AI
Exam 28: Income Taxation of Trusts and Estates

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


The deduction for the Goodman Trust's $100,000 gift to charity is ____________________ when one-fourth of Goodman's accounting income for the tax year is exempt interest income.

Free
(Short Answer)
4.8/5  (67)
(67) Correct Answer: Verified
$75,000
Corpus, principal, and assets of the trust are synonyms.
Free
(True/False)
4.8/5 (88)
(88) Correct Answer:Verified
VerifiedTrue
The Whitmer Trust operates a manufacturing business. When Whitmer incurs a net operating loss, the current-year deduction passes through to the income beneficiaries.
Free
(True/False)
4.9/5 (87)
(87) Correct Answer:Verified
VerifiedFalse
During the current year, the Santo Trust received $30,000 of taxable interest income, paid trustee's commissions of $3,000, and had no other income or expenses.The Santo trust instrument requires that $20,000 be paid annually to Marilyn, and $40,000 be paid annually to Domingo.How much gross income must Marilyn and Domingo recognize?
(Multiple Choice)
4.9/5 (76)
(76) The Bard Estate incurs a $25,000 fee in disposing of the real property of the decedent. The executor can decide to claim a $5,000 deduction against the Federal estate tax, and a $20,000 deduction on the estate's income tax return.
(True/False)
4.8/5 (70)
(70) Your client Ming is a complex trust that operates exclusively in the U.S. Make a list of five or more tax planning opportunities that you might suggest to Ming.
(Essay)
4.8/5 (84)
(84) The Suarez Trust generated distributable net income (DNI) this year of $150,000, one-third of which was portfolio income, and the balance of which was exempt interest.Under the terms of the trust, Clara Suarez is to receive an annual income distribution of $30,000.At the discretion of the trustee, additional distributions can be made to Clara, or to Clark Suarez III.This year, the trustee's distributions to Clara totaled $90,000.Clark also received $90,000.How much of the trust's DNI is assigned to Clark?
(Multiple Choice)
5.0/5 (79)
(79) A fiduciary's cost recovery deductions are assigned corresponding to the disposition of entity ____________________ income for the year.
(Short Answer)
4.7/5 (74)
(74) When a trust distributes an in-kind asset with a realized loss, most likely this loss should be allocated to and immediately deducted by the first-tier beneficiaries.
(True/False)
4.9/5 (73)
(73) A complex trust pays tax on the income that it retains and adds to corpus.
(True/False)
4.9/5 (88)
(88) The Form 1041 of a calendar-year trust is due on ____________________ 15.
(Short Answer)
4.9/5 (79)
(79) The grantor of a trust generally designates both ____________________ and ____________________ beneficiaries under the controlling agreement.
or
(Short Answer)
4.9/5 (74)
(74) A ____________________ tier distribution is one that the trust agreement requires to be made by the trustee to the income beneficiary.
or
(Short Answer)
4.8/5 (83)
(83) An estate's income beneficiary generally must wait until the entity is terminated by the executor to receive any distribution of income.
(True/False)
4.8/5 (83)
(83) The IRS encourages ____________________ filing for Forms 1041.
(Short Answer)
4.8/5 (74)
(74) Generally, an estate's taxable income is computed in a manner similar to that used for a(n) ____________________.
(Short Answer)
4.9/5 (99)
(99) A realized loss is recognized by a trust when it distributes a non-cash asset.
(True/False)
4.7/5 (75)
(75) Consider the term distributable net income as it is used with respect to the Federal income taxation of trusts and estates. How is this amount computed? Where is it used in computing the parties' taxable incomes?
(Essay)
4.8/5 (82)
(82) Counsell is a simple trust that correctly uses the calendar year for tax purposes.Its income beneficiaries (Kathie, Lynn, Mark, and Norelle) are entitled to the trust's annual accounting income in shares of one-fourth each.For the current calendar year, the trust has ordinary business income of $40,000, a long-term capital gain of $20,000 (allocable to corpus), and a trustee commission expense of $4,000 (allocable to corpus).Use the format of Figure 28.3 in the text to address the following items.
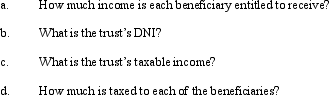
(Essay)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)