



 Chat with AI
Exam 22: S: Corporations

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


If an S corporation shareholder's basis in a loan to the entity has been _________________, the shareholder recognizes gross income when the S corporation repays the shareholder.
(Short Answer)
4.8/5  (77)
(77) An S shareholder's stock basis is reduced by flow-through losses before accounting for distributions.
(True/False)
4.8/5 (73)
(73) Where the S corporation rules are silent, partnership rules apply to the S corporation.
(True/False)
4.8/5 (72)
(72) An S corporation that has total assets of at least $7.5 million on Schedule L at the end of the tax year must file a Schedule M-3.
(True/False)
4.7/5 (80)
(80) The passive loss limitations apply at the S corporation shareholder level.
(True/False)
4.9/5 (81)
(81) Blue Corporation elects S status effective for tax year 2012. As of January 1, 2012, Blue's assets were appraised as follows.
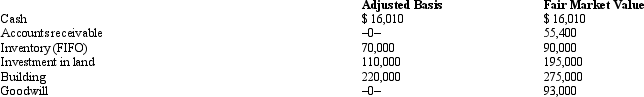 In each of the following situations, calculate any built-in gains tax, assuming that the highest corporate tax rate is 35%. C corporation taxable income would have been $100,000.
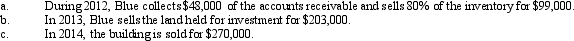
In each of the following situations, calculate any built-in gains tax, assuming that the highest corporate tax rate is 35%. C corporation taxable income would have been $100,000.
(Essay)
4.8/5 (79)
(79) ____________________ common stock and ____________________ preferred stock (with preference on dividends) are treated as two different classes of stock by the S corporation rules.
(Short Answer)
4.9/5 (69)
(69) Since loss property receives a ____________________ in basis without any loss recognition, S corporation distributions of loss property should be ____________________.
(Short Answer)
4.7/5 (77)
(77) An item that appears in the "Other Adjustments Account" affects stock basis, but not AAA, such as tax-exempt interest.
(True/False)
4.8/5 (83)
(83) Trent Huynh is a 45% owner of a calendar year S corporation during 2012.His beginning stock basis is $292,000, and the S corporation reports the following items.
 Calculate Huynh's stock basis at year-end.
 (Essay)
4.7/5 (76)
(76) Pass-through S corporation losses can reduce the basis in the shareholder's loan to the entity, but distributions do not.
(True/False)
4.8/5 (94)
(94) On January 1, 2012, Zundel, Inc., an electing S corporation, has $4,000 of AEP and a balance of $10,000 in AAA.Zundel has two shareholders, Erin and Maine, each of whom owns 500 shares of Zundel's stock.Zundel's 2012 taxable income is $5,000.Zundel distributes $6,000 to each shareholder on February 1, 2012, and distributes another $3,000 to each shareholder on September 1.How is Erin taxed on this distribution?
(Multiple Choice)
4.9/5 (73)
(73) The LIFO recapture tax is a variation of the passive investment income penalty tax.
(True/False)
5.0/5 (90)
(90) A new S corporation shareholder can revoke the S election unilaterally, if he/she owns how much of the existing S corporation's stock?
(Multiple Choice)
4.8/5 (75)
(75) Depreciation recapture income is a ____________________ computed amount.
(Short Answer)
4.9/5 (70)
(70) Pepper, Inc., an S corporation, reports sales revenues of $400,000, taxable interest of $380,000, operating expenses of $250,000, and deductions attributable to the interest income of $140,000.What is Pepper's passive income penalty tax payable, if any?
(Multiple Choice)
4.8/5 (82)
(82) Which type of distribution from an S corporation is taxed at the 0/15% Federal income tax rate?
(Multiple Choice)
5.0/5 (81)
(81) The carryover period for the NOLs of a C corporation continues to run during S corporation years.
(True/False)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)