



 Chat with AI
Exam 24: Multistate Corporate Taxation

Exam 1: An Introduction to Taxation and Understanding the Federal Tax Law159 Questions
Exam 2: Working With the Tax Law85 Questions
Exam 3: Computing the Tax150 Questions
Exam 4: Gross Income: Concepts and Inclusions125 Questions
Exam 5: Gross Income: Exclusions116 Questions
Exam 6: Deductions and Losses: in General153 Questions
Exam 7: Deductions and Losses: Certain Business Expenses and Losses97 Questions
Exam 8: Depreciation, Cost Recovery, Amortization, and Depletion116 Questions
Exam 9: Deductions: Employee and Self-Employed-Related Expenses166 Questions
Exam 10: Deductions and Losses: Certain Itemized Deductions106 Questions
Exam 11: Investor Losses103 Questions
Exam 12: Tax Credits and Payments109 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 1200 Questions
Exam 13: Property Transactions: Determination of Gain or Loss, Basis Considerations, and Nontaxable Exchanges-Part 292 Questions
Exam 14: Property Transactions: Capital Gains and Losses, 1231, Recapture Provisions144 Questions
Exam 15: Alternative Minimum Tax125 Questions
Exam 16: Accounting Periods and Methods87 Questions
Exam 17: Corporations: Introduction and Operating Rules109 Questions
Exam 18: Corporations: Organization and Capital Structure93 Questions
Exam 19: Corporations: Distributions Not in Complete Liquidation145 Questions
Exam 20: Corporations: Distributions in Complete Liquidation and an Overview of Reorganizations70 Questions
Exam 21: Partnerships159 Questions
Exam 22: S: Corporations159 Questions
Exam 23: Exempt Entities151 Questions
Exam 24: Multistate Corporate Taxation145 Questions
Exam 25: Taxation of International Transactions148 Questions
Exam 26: Tax Practice and Ethics147 Questions
Exam 28: Income Taxation of Trusts and Estates145 Questions
Select questions type


In computing the property factor, property owned by the corporation typically is valued at its ____________________, but without adjusting for depreciation.
or
(Short Answer)
4.7/5  (76)
(76) Parent and Junior form a unitary group of corporations.Parent is located in a state with an effective tax rate of 3%, while Junior's effective tax rate is 9%.Acting in concert to reduce overall tax liabilities, the group should:
(Multiple Choice)
4.9/5 (83)
(83) A typical state taxable income addition modification is for the Federal income tax paid for the period.
(True/False)
5.0/5 (80)
(80) The starting point in computing state taxable income generally is ____________________.
(Short Answer)
4.8/5 (80)
(80) A service engineer spends 60% of her time maintaining the employer's productive business property and 40% maintaining the employer's nonbusiness rental properties.This year, her compensation totaled $90,000.The payroll factor assigns $54,000 to the state in which the employer is based.
(True/False)
4.9/5 (83)
(83) Boot Corporation is subject to income tax in States A and B.Boot's operations generated $200,000 of apportionable income, and its sales and payroll activity and average property owned in each of the states is as follows.  How much more (less) of Boot's income is subject to A income tax if, instead of using an equally-weighted three-factor apportionment formula, A uses a formula with a double-weighted sales factor?
 (Multiple Choice)
4.8/5 (81)
(81) Net Corporation's sales office and manufacturing plant are located in State X.Net also maintains a manufacturing plant and sales office in State W.For purposes of apportionment, X defines payroll as all compensation paid to employees, including contributions to § 401(k) deferred compensation plans.Under the statutes of W, neither compensation paid to officers nor contributions to § 401(k) plans are included in the payroll factor.Net incurred the following personnel costs. 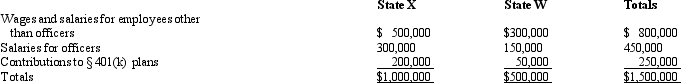 Net's payroll factor for State W is:
 (Multiple Choice)
4.9/5 (91)
(91) In the broadest application of the unitary theory, the U.S.unitary business files a combined tax return using factors and income amounts for all affiliates:
(Multiple Choice)
4.8/5 (92)
(92) State Q has adopted sales-factor-only apportionment for its corporate income tax. As a result, a ____________________ (larger/smaller) percentage of an out-of-state corporation's income is assigned to tax in the state.
(Short Answer)
4.9/5 (72)
(72) Typically exempt from the sales/use tax base is the purchase of clothing from a neighbor's "garage sale."
(True/False)
4.9/5 (89)
(89) Valdez Corporation, a calendar-year taxpayer, owns property in States M and O.Both M and O require that the average value of assets be included in the property factor.M requires that the property be valued at its historical cost, and O requires that the property be included in the property factor at its net depreciated book value. 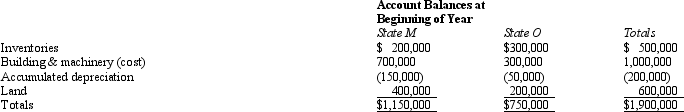
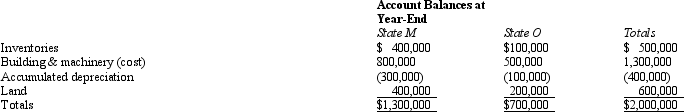 Valdez's O property factor is:
 (Multiple Choice)
4.9/5 (90)
(90) You are completing the State A income tax return for Quaint Company, LLC.Quaint operates in various states, showing the following results.
 In A, all interest is treated as business income.A uses a sales-only apportionment factor.Compute Quaint's A taxable income.
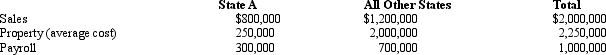
In A, all interest is treated as business income.A uses a sales-only apportionment factor.Compute Quaint's A taxable income.
(Essay)
4.8/5 (84)
(84) Typically exempt from the sales/use tax base is the purchase of tools by a manufacturer to make the widgets that it sells.
(True/False)
4.9/5 (81)
(81) Typically, corporate income taxes constitute about 20 percent of a state's tax collections.
(True/False)
4.9/5 (91)
(91) Property taxes generally are collected by local taxing jurisdictions, not the state or Federal governments.
(True/False)
4.7/5 (91)
(91) Bobby and Sally work for the same employer, Wooster Manufacturing. Bobby manages the company's speculative investment portfolio, and Sally is a foreman in the factory. How are the salaries paid to Bobby and Sally treated in computing Wooster's payroll factor? Apply the general UDITPA rules.
(Essay)
4.8/5 (84)
(84) Roughly five percent of all taxes paid by businesses in the U.S.are to state, local, and municipal jurisdictions.
(True/False)
4.9/5 (75)
(75) Typically, a sales/use tax is applied to a retail sale of ____________________ property.
(Short Answer)
4.7/5 (69)
(69) Indicate for each transaction whether a sales (S) or use (U) applies, or whether the transaction is nontaxable (N).Where the laws vary among various states, assume that the most common rules apply.All taxpayers are individuals.
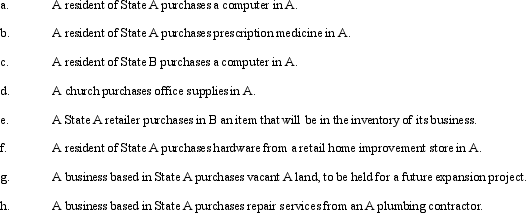
(Essay)
4.9/5 (90)
(90) The sales/use tax that is employed by most U.S.states does not fall on all retail transactions. Identify at least five sales/use tax exemptions that states often allow, eliminating certain transactions from the tax base.
(Essay)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)