



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics347 Questions
Exam 2: Thinking Like an Economist535 Questions
Exam 3: Interdependence and the Gains From Trade442 Questions
Exam 4: The Market Forces of Supply and Demand569 Questions
Exam 5: Elasticity and Its Application503 Questions
Exam 6: Supply, Demand, and Government Policies556 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets460 Questions
Exam 8: Application: The Costs of Taxation422 Questions
Exam 9: Application: International Trade409 Questions
Exam 10: Measuring a Nations Income428 Questions
Exam 11: Measuring the Cost of Living436 Questions
Exam 12: Production and Growth417 Questions
Exam 13: Saving, Investment, and the Financial System473 Questions
Exam 14: The Basic Tools of Finance419 Questions
Exam 15: Unemployment571 Questions
Exam 16: The Monetary System423 Questions
Exam 17: Money Growth and Inflation388 Questions
Exam 18: Open-Economy Macroeconomic Models448 Questions
Exam 19: A Macroeconomic Theory of the Open Economy374 Questions
Exam 20: Aggregate Demand and Aggregate Supply471 Questions
Exam 21: The Influence of Monetary and Fiscal Policy on Aggregate Demand416 Questions
Exam 22: The Short-Run Trade-Off Between Inflation and Unemployment400 Questions
Exam 23: Six Debates Over Macroeconomic Policy235 Questions
Select questions type


Table 7-3
The only four consumers in a market have the following willingness to pay for a good:
Buyer Willingritis to Pay Carlos \ 15 Quilena \ 25 Wilbur \ 35 Ming-la \ 45
-Refer to Table 7-3. If the price is $20, then consumer surplus in the market is
(Multiple Choice)
4.8/5  (79)
(79) Table 7-7
The following table represents the costs of five possible sellers. Seller Cost Abby \ 1,500 Babby \ 1,200 Carlos \ 1,000 Dianne \ 750 Evalina \ 500
-Refer to Table 7-7. If the price is $775, who would be willing to supply the product?
(Multiple Choice)
4.9/5 (74)
(74) If the demand for leather decreases, producer surplus in the leather market
(Multiple Choice)
4.9/5 (72)
(72) Moving production from a high-cost producer to a low-cost producer will
(Multiple Choice)
4.8/5 (88)
(88) The consumption of water by local residents that may include pesticide runoff from local farmers' fields is an example of
(Multiple Choice)
4.8/5 (84)
(84) Figure 7-21  -Refer to Figure 7-21. Sellers whose costs are greater than the equilibrium price are represented by segment
 (Multiple Choice)
4.9/5 (66)
(66) Figure 7-18  -Refer to Figure 7-18. Assume demand increases and as a result, equilibrium price increases to $22 and equilibrium quantity increases to 110. The increase in producer surplus to producers already in the market would be
 (Multiple Choice)
4.7/5 (68)
(68) Figure 7-13  -Refer to Figure 7-13. If the price of the good is $600, then producer surplus amounts to
 (Multiple Choice)
4.7/5 (75)
(75) The study of how the allocation of resources affects economic well-being is called
(Multiple Choice)
4.7/5 (74)
(74) Figure 7-13
-Refer to Figure 7-13. If the price of the good is $500, then producer surplus amounts to
-Refer to Figure 7-13. If the price of the good is $500, then producer surplus amounts to (Multiple Choice)
4.8/5 (78)
(78) Justin builds fences for a living. Justin's out-of-pocket expenses (for wood, paint, etc.) plus the value that he places on his own time amount to his
(Multiple Choice)
5.0/5 (76)
(76) Answer each of the following questions about supply and producer surplus.
a.What is producer surplus, and how is it measured?
b.What is the relationship between the cost to sellers and the supply curve?
c.Other things equal, what happens to producer surplus when the price of a good rises? Illustrate your answer on a supply curve.
(Essay)
4.9/5 (75)
(75) Table 7-1
Buger Willingnits Ta Raz Lari \ 50.00 Audrey \ 30.00 Zach \ 20.00 Calvin \ 10.00
-Refer to Table 7-1. If the price of the product is $22, then who would be willing to purchase the product?
(Multiple Choice)
4.9/5 (86)
(86) Figure 7-12 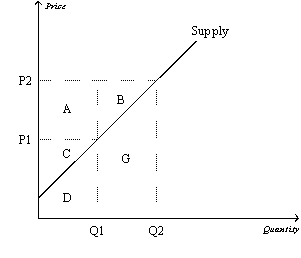 -Refer to Figure 7-12. When the price falls from P2 to P1, producer surplus
 (Multiple Choice)
4.8/5 (74)
(74) Table 7-5
For each of three potential buyers of oranges, the table displays the willingness to pay for the first three oranges of the day. Assume Alex, Barb, and Carlos are the only three buyers of oranges, and only three oranges can be supplied per day. First Orangp Second Orange Third Orange Alliton \ 2.00 \ 1.50 \ 0.75 Bob \ 1.50 \ 1.00 \ 0.80 Chariste \ 0.75 \ 0.25 \ 0
-Refer to Table 7-5. If the market price of an orange is $0.40, then
(Multiple Choice)
4.9/5 (79)
(79) Figure 7-9  -Refer to Figure 7-9. If the supply curve is S and the demand curve shifts from D to D', what is the increase in producer surplus due to new producers entering the market?
 (Multiple Choice)
4.8/5 (78)
(78) In which of the following circumstances would a buyer be indifferent about buying a good?
(Multiple Choice)
4.8/5 (95)
(95) If the current allocation of resources in the market for wallpaper is efficient, then it must be the case that
(Multiple Choice)
4.9/5 (66)
(66) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)