



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics237 Questions
Exam 2: Thinking Like an Economist267 Questions
Exam 3: Interdependence and the Gains From Trade217 Questions
Exam 4: The Market Forces of Supply and Demand303 Questions
Exam 5: Elasticity and Its Applications282 Questions
Exam 6: Supply, demand, and Government Policies252 Questions
Exam 7: Consumers, producers, and the Efficiency of Markets248 Questions
Exam 8: Application: the Costs of Taxation245 Questions
Exam 9: Application: International Trade245 Questions
Exam 10: Externalities288 Questions
Exam 11: Public Goods and Common Resources258 Questions
Exam 12: The Design of the Tax System328 Questions
Exam 13: The Costs of Production303 Questions
Exam 14: Firms in Competitive Markets271 Questions
Exam 15: Monopoly306 Questions
Exam 16: Oligopoly291 Questions
Exam 17: Monopolistic Competition257 Questions
Exam 18: The Markets for the Factors of Production284 Questions
Exam 19: Earnings and Discrimination286 Questions
Exam 20: Income Inequality and Poverty247 Questions
Exam 21: The Theory of Consumer Choice238 Questions
Exam 22: Frontiers of Microeconomics199 Questions
Exam 23: Measuring a Nations Income215 Questions
Exam 24: Measuring the Cost of Living208 Questions
Exam 25: Production and Growth240 Questions
Exam 26: Saving, investment, and the Financial System282 Questions
Exam 27: The Basic Tools of Finance249 Questions
Exam 28: Unemployment242 Questions
Exam 29: The Monetary System277 Questions
Exam 30: Money Growth and Inflation224 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts256 Questions
Exam 32: A Macroeconomic Theory of the Open Economy217 Questions
Exam 33: Aggregate Demand and Aggregate Supply302 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand249 Questions
Exam 35: The Short Run Trade Off Between Inflation and Unemployment246 Questions
Exam 36: Five Debates Over Macroeconomic Policy140 Questions
Select questions type


For a certain firm,the 100th unit of output that the firm produces has a marginal revenue of $10 and a marginal cost of $7.It follows that
(Multiple Choice)
4.9/5  (66)
(66) In the short run,a market consists of 100 identical firms.The market price is $8,and the total cost to each firm of producing various levels of output is given in the table below.What will total quantity supplied be in the market? 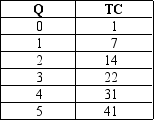
(Multiple Choice)
4.8/5 (77)
(77) Table 14-3
Use the information for a competitive firm in the table below to answer the following questions.
 -Refer to Table 14-3.If this firm chooses to maximize profit it will choose a level of output where marginal revenue is equal to
 (Multiple Choice)
5.0/5 (81)
(81) Which of the following statements best reflects a price-taking firm?
(Multiple Choice)
4.8/5 (71)
(71) List and describe the characteristics of a perfectly competitive market.
(Essay)
4.8/5 (84)
(84) The assumption of free entry and exit is necessary for firms in a competitive market to be price takers.
(True/False)
4.8/5 (89)
(89) A profit-maximizing firm in a competitive market will increase production when average revenue exceeds marginal cost.
(True/False)
4.7/5 (92)
(92) Explain how a firm in a competitive market identifies the profit-maximizing level of production.When should the firm raise production,and when should the firm lower production?
(Essay)
4.7/5 (93)
(93) News reports from the western United States occasionally report incidents of cattle ranchers slaughtering a large number of newborn calves and burying them in mass graves rather than transporting them to markets.Assuming that this is rational behavior by profit-maximizing "firms," explain what economic factors may influence such behavior.
(Essay)
5.0/5 (85)
(85) Table 14-2
The following table presents cost and revenue information for Soper's Port Vineyard.
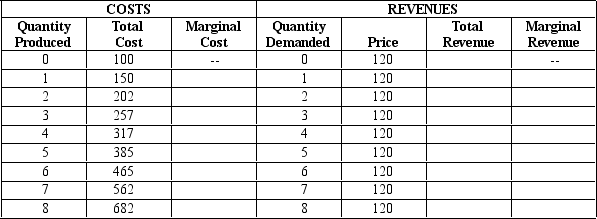 -Refer to Table 14-2.Consumers are willing to pay $120 per unit of port wine.What is the marginal cost of the 1st unit?
 (Multiple Choice)
4.8/5 (100)
(100) A competitive firm's short-run supply curve is part of which of the following curves?
(Multiple Choice)
4.9/5 (70)
(70) Use a graph to demonstrate the circumstances that would prevail in a perfectly competitive market where firms are experiencing economic losses.Identify costs,revenue,and the economic losses on your graph.Using your graph,determine whether this firm will shut down in the short run,or choose to remain in the market.Explain your answer.
(Essay)
4.9/5 (82)
(82) As a general rule,when accountants calculate profit they account for explicit costs but usually ignore
(Multiple Choice)
4.9/5 (86)
(86) Which of these types of costs can be ignored when an individual or a firm is making decisions?
(Multiple Choice)
4.8/5 (83)
(83) If a competitive firm is currently producing a level of output at which profit is not maximized,then it must be true that
(Multiple Choice)
4.9/5 (87)
(87) Figure 14-1
The graph below depicts the cost structure for a firm in a competitive market.
 -Refer to Figure 14-1.When price rises from P₂ to P₃,the firm finds that
 (Multiple Choice)
4.9/5 (69)
(69) Figure 14-5
The figure below depicts the cost structure of a firm in a competitive market.
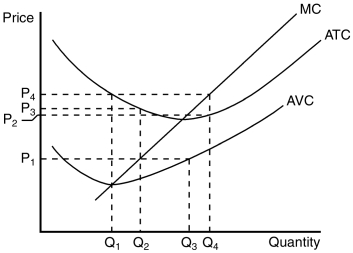 -Refer to Figure 14-5.When market price is P₁,a profit-maximizing firm's total profit or loss can be represented by which area?
 (Multiple Choice)
4.7/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)