



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics237 Questions
Exam 2: Thinking Like an Economist267 Questions
Exam 3: Interdependence and the Gains From Trade217 Questions
Exam 4: The Market Forces of Supply and Demand303 Questions
Exam 5: Elasticity and Its Applications282 Questions
Exam 6: Supply, demand, and Government Policies252 Questions
Exam 7: Consumers, producers, and the Efficiency of Markets248 Questions
Exam 8: Application: the Costs of Taxation245 Questions
Exam 9: Application: International Trade245 Questions
Exam 10: Externalities288 Questions
Exam 11: Public Goods and Common Resources258 Questions
Exam 12: The Design of the Tax System328 Questions
Exam 13: The Costs of Production303 Questions
Exam 14: Firms in Competitive Markets271 Questions
Exam 15: Monopoly306 Questions
Exam 16: Oligopoly291 Questions
Exam 17: Monopolistic Competition257 Questions
Exam 18: The Markets for the Factors of Production284 Questions
Exam 19: Earnings and Discrimination286 Questions
Exam 20: Income Inequality and Poverty247 Questions
Exam 21: The Theory of Consumer Choice238 Questions
Exam 22: Frontiers of Microeconomics199 Questions
Exam 23: Measuring a Nations Income215 Questions
Exam 24: Measuring the Cost of Living208 Questions
Exam 25: Production and Growth240 Questions
Exam 26: Saving, investment, and the Financial System282 Questions
Exam 27: The Basic Tools of Finance249 Questions
Exam 28: Unemployment242 Questions
Exam 29: The Monetary System277 Questions
Exam 30: Money Growth and Inflation224 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts256 Questions
Exam 32: A Macroeconomic Theory of the Open Economy217 Questions
Exam 33: Aggregate Demand and Aggregate Supply302 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand249 Questions
Exam 35: The Short Run Trade Off Between Inflation and Unemployment246 Questions
Exam 36: Five Debates Over Macroeconomic Policy140 Questions
Select questions type


In the long-run equilibrium of a market with free entry and exit,marginal firms are operating
(Multiple Choice)
4.8/5  (82)
(82) The production decisions of perfectly competitive firms follow one of the Ten Principles of Economics,which states that rational people
(Multiple Choice)
4.9/5 (79)
(79) The competitive firm's long-run supply curve is that portion of the marginal cost curve that lies above average
(Multiple Choice)
4.7/5 (75)
(75) A firm will shut down in the short run if the total revenue that it would get from producing and selling its output is less than its
(Multiple Choice)
4.9/5 (90)
(90) By comparing the marginal revenue and marginal cost from each unit produced,a firm in a competitive market can determine the profit-maximizing level of production.
(True/False)
4.8/5 (67)
(67) In a competitive market,firms are unable to differentiate their product from that of other producers.
(True/False)
4.9/5 (72)
(72) Suppose the total cost for various levels of output for a competitive firm are given in the table below: 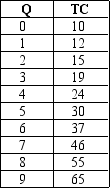 If the market price is $8,how many units should the firm produce to maximize profit?
 (Multiple Choice)
4.9/5 (85)
(85) In a competitive market with free entry and exit,if all firms have the same cost structure,then
(Multiple Choice)
4.8/5 (84)
(84) Figure 14-7
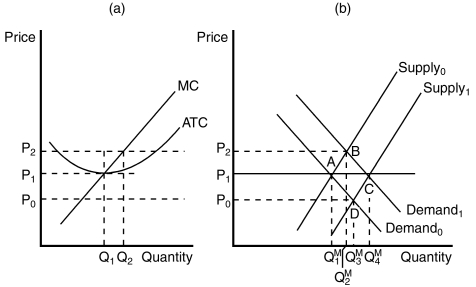 -Refer to Figure 14-7.Suppose a firm in a competitive market,like the one depicted in panel (a),observes market price rising from P₁ to P₂.Which of the following could explain this observation?
 (Multiple Choice)
4.9/5 (91)
(91) Table 14-4
The following table presents cost and revenue information for John's Vineyard.
 -Refer to Table 14-4.What is the average revenue when 4 units are sold?
 (Multiple Choice)
4.7/5 (85)
(85) A market is competitive if (i) firms have the flexibility to price their own product.
(ii) each buyer is small compared to the market.
(iii) each seller is small compared to the market.
(Multiple Choice)
4.8/5 (77)
(77) A competitive market is in long-run equilibrium.If demand decreases,we can be certain that price will
(Multiple Choice)
5.0/5 (70)
(70) A firm will shutdown in the short run if,for all positive levels of output,
(Multiple Choice)
4.9/5 (78)
(78) Scenario 14-2
Assume a certain firm is producing Q = 1,000 units of output. At Q = 1,000, the firm's marginal cost equals $15 and its average total cost equals $11. The firm sells its output for $12 per unit.
-Refer to Scenario 14-2.At Q = 1,000,the firm's profit amounts to
(Multiple Choice)
4.8/5 (72)
(72) A firm's incentive to compare marginal revenue and marginal cost is an application of the principle that rational people think at the margin.
(True/False)
4.9/5 (89)
(89) The textile industry is composed of a large number of small firms.In recent years,these firms have suffered economic losses and many sellers have left the industry.Economic theory suggests that these conditions will
(Multiple Choice)
5.0/5 (71)
(71) Whenever a perfectly competitive firm chooses to change its level of output,holding the price of the product constant,its marginal revenue
(Multiple Choice)
5.0/5 (72)
(72) To answer the question,"How much revenue does the farm receive for the typical gallon of milk?" a dairy farmer must be able to calculate sunk cost.
(True/False)
4.9/5 (82)
(82) There are 500 identical firms in a competitive market.The firms do not use any resources that are available in limited quantities,and all of them have the following long-run cost structure: 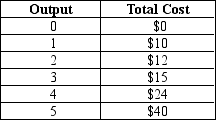 The long-run supply curve for this market is
 (Multiple Choice)
4.9/5 (86)
(86) When a profit-maximizing firm's fixed costs are considered sunk in the short run,then the firm
(Multiple Choice)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)