



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics237 Questions
Exam 2: Thinking Like an Economist267 Questions
Exam 3: Interdependence and the Gains From Trade217 Questions
Exam 4: The Market Forces of Supply and Demand303 Questions
Exam 5: Elasticity and Its Applications282 Questions
Exam 6: Supply, demand, and Government Policies252 Questions
Exam 7: Consumers, producers, and the Efficiency of Markets248 Questions
Exam 8: Application: the Costs of Taxation245 Questions
Exam 9: Application: International Trade245 Questions
Exam 10: Externalities288 Questions
Exam 11: Public Goods and Common Resources258 Questions
Exam 12: The Design of the Tax System328 Questions
Exam 13: The Costs of Production303 Questions
Exam 14: Firms in Competitive Markets271 Questions
Exam 15: Monopoly306 Questions
Exam 16: Oligopoly291 Questions
Exam 17: Monopolistic Competition257 Questions
Exam 18: The Markets for the Factors of Production284 Questions
Exam 19: Earnings and Discrimination286 Questions
Exam 20: Income Inequality and Poverty247 Questions
Exam 21: The Theory of Consumer Choice238 Questions
Exam 22: Frontiers of Microeconomics199 Questions
Exam 23: Measuring a Nations Income215 Questions
Exam 24: Measuring the Cost of Living208 Questions
Exam 25: Production and Growth240 Questions
Exam 26: Saving, investment, and the Financial System282 Questions
Exam 27: The Basic Tools of Finance249 Questions
Exam 28: Unemployment242 Questions
Exam 29: The Monetary System277 Questions
Exam 30: Money Growth and Inflation224 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts256 Questions
Exam 32: A Macroeconomic Theory of the Open Economy217 Questions
Exam 33: Aggregate Demand and Aggregate Supply302 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand249 Questions
Exam 35: The Short Run Trade Off Between Inflation and Unemployment246 Questions
Exam 36: Five Debates Over Macroeconomic Policy140 Questions
Select questions type


Scenario 14-1
As part of an estate settlement Mary received $1 million. She decided to use the money to purchase a small business in Anywhere, USA. If Mary would have invested the $1 million in a risk-free bond fund she could have made $100,000 each year. She also quit her job with Lucky.Com Inc. to devote all of her time to her new business; her salary at Lucky.Com Inc. was $75,000 per year.
-Refer to Scenario 14-1.How large would Mary's accounting profits need to be to allow her to attain zero economic profit?
(Multiple Choice)
4.9/5  (86)
(86) The marginal firm in a competitive market will earn zero economic profit in the long run.
(True/False)
4.9/5 (63)
(63) In the long-run equilibrium of a competitive market,the number of firms in the market adjusts until the market demand is satisfied at a price equal to
(Multiple Choice)
4.9/5 (72)
(72) The short-run market supply curve in a perfectly competitive industry
(Multiple Choice)
4.9/5 (71)
(71) At its current level of production a profit-maximizing firm in a competitive market receives $12.50 for each unit it produces and faces an average total cost of $10.At the market price of $12.50 per unit,the firm's marginal cost curve crosses the marginal revenue curve at an output level of 1,000 units.What is the firm's current profit? What is likely to occur in this market and why?
(Essay)
4.8/5 (82)
(82) One of the most important determinants of the success of free-market capitalism is
(Multiple Choice)
4.7/5 (90)
(90) Table 14-2
The following table presents cost and revenue information for Soper's Port Vineyard.
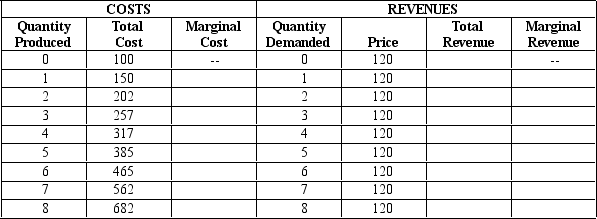 -Refer to Table 14-2.Consumers are willing to pay $120 per unit of port wine.What is the marginal cost of the 8th unit?
 (Multiple Choice)
4.8/5 (75)
(75) In the long-run equilibrium of a market with free entry and exit,if all firms have the same cost structure,then
(Multiple Choice)
4.8/5 (81)
(81) When economic profits are zero in equilibrium,the firm's revenue must be sufficient to cover all opportunity costs.
(True/False)
4.9/5 (85)
(85) As a general rule,profit-maximizing producers in a competitive market produce output at a point where
(Multiple Choice)
4.8/5 (87)
(87) Suppose a firm in a competitive market produces and sells 8 units of output and has a marginal revenue of $8.00.What would be the firm's total revenue if it instead produced and sold 4 units of output?
(Multiple Choice)
4.8/5 (82)
(82) Scenario 14-3
In March of 2000 a study sponsored by the Food Consumer Safety Board found that consumption of irradiated grapefruit increased the health of laboratory rats. As a result of national press coverage of the report, the demand for irradiated grapefruit increased dramatically. Organic farmers were able to switch from organic production of grapefruit to irradiated production with no additional cost. Assume that the grapefruit market satisfies all of the attributes of perfect competition.
-Refer to Scenario 14-3.If the increased production of irradiated grapefruit caused a rise in the marginal transportation costs of moving irradiated grapefruit to market,the
(Multiple Choice)
4.9/5 (74)
(74) When all firms and potential firms in a market have the same cost curves,the long-run equilibrium of a competitive market with free entry and exit will be characterized by firms
(Multiple Choice)
4.7/5 (86)
(86) Which of the following is NOT a characteristic of a perfectly competitive market?
(Multiple Choice)
4.9/5 (78)
(78) In making a short-run profit-maximizing production decision,the firm must consider both fixed and variable cost.
(True/False)
5.0/5 (80)
(80) A firm will shut down in the short run if revenue is not sufficient to cover its variable costs of production.
(True/False)
4.8/5 (77)
(77) Refer to Figure 14-6.When 100 identical firms participate in this market,at what price will 15,000 units be supplied to this market?
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)