



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics237 Questions
Exam 2: Thinking Like an Economist267 Questions
Exam 3: Interdependence and the Gains From Trade217 Questions
Exam 4: The Market Forces of Supply and Demand303 Questions
Exam 5: Elasticity and Its Applications282 Questions
Exam 6: Supply, demand, and Government Policies252 Questions
Exam 7: Consumers, producers, and the Efficiency of Markets248 Questions
Exam 8: Application: the Costs of Taxation245 Questions
Exam 9: Application: International Trade245 Questions
Exam 10: Externalities288 Questions
Exam 11: Public Goods and Common Resources258 Questions
Exam 12: The Design of the Tax System328 Questions
Exam 13: The Costs of Production303 Questions
Exam 14: Firms in Competitive Markets271 Questions
Exam 15: Monopoly306 Questions
Exam 16: Oligopoly291 Questions
Exam 17: Monopolistic Competition257 Questions
Exam 18: The Markets for the Factors of Production284 Questions
Exam 19: Earnings and Discrimination286 Questions
Exam 20: Income Inequality and Poverty247 Questions
Exam 21: The Theory of Consumer Choice238 Questions
Exam 22: Frontiers of Microeconomics199 Questions
Exam 23: Measuring a Nations Income215 Questions
Exam 24: Measuring the Cost of Living208 Questions
Exam 25: Production and Growth240 Questions
Exam 26: Saving, investment, and the Financial System282 Questions
Exam 27: The Basic Tools of Finance249 Questions
Exam 28: Unemployment242 Questions
Exam 29: The Monetary System277 Questions
Exam 30: Money Growth and Inflation224 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts256 Questions
Exam 32: A Macroeconomic Theory of the Open Economy217 Questions
Exam 33: Aggregate Demand and Aggregate Supply302 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand249 Questions
Exam 35: The Short Run Trade Off Between Inflation and Unemployment246 Questions
Exam 36: Five Debates Over Macroeconomic Policy140 Questions
Select questions type


Use a graph to demonstrate the circumstances that would prevail in a competitive market where firms are earning economic profits.Can this scenario be maintained in the long run? Carefully explain your answer.
(Essay)
4.7/5  (81)
(81) Figure 14-4
The figure below depicts the cost structure of a firm in a competitive market.
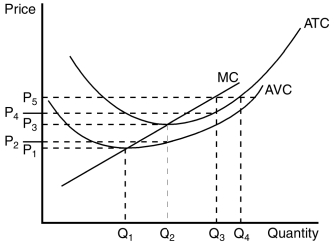 -Refer to Figure 14-4.Firms would be encouraged to enter this market for all prices that exceed
 (Multiple Choice)
4.7/5 (69)
(69) Table 14-5
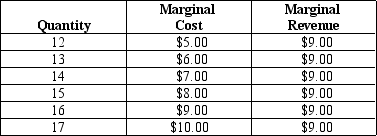 -Refer to Table 14-5.This table provides information on a firm's output,marginal revenue,and marginal cost for a firm.If the firm is maximizing profit,how much profit is it earning?
 (Multiple Choice)
4.8/5 (79)
(79) Profit-maximizing firms enter a competitive market when,for existing firms in that market,
(Multiple Choice)
4.8/5 (95)
(95) A firm in a competitive market will maximize profit when the level of production is such that marginal cost equals price.
(True/False)
4.8/5 (79)
(79) Figure 14-2
The figure below depicts the cost structure of a profit-maximizing firm in a competitive market.
 -Refer to Figure 14-2.Which line segment best reflects the short-run supply curve for this firm?
 (Multiple Choice)
4.8/5 (78)
(78) In a perfectly competitive market,the horizontal sum of all the individual firms' supply curves is
(Multiple Choice)
4.9/5 (68)
(68) Describe the difference between average revenue and marginal revenue.Why are both of these revenue measures important to a profit-maximizing firm?
(Essay)
5.0/5 (84)
(84) When firms have an incentive to exit a competitive market,their exit will
(Multiple Choice)
4.8/5 (78)
(78) In a long-run equilibrium,it is possible that some firms in a competitive market are making a positive economic profit.
(True/False)
4.8/5 (71)
(71) In the long run,a competitive market with 1,000 identical firms will experience an equilibrium price equal to the minimum of each firm's average total cost.
(True/False)
4.8/5 (75)
(75) If occupational safety laws were changed so that firms no longer had to take expensive steps to meet regulatory requirements,we would expect that
(Multiple Choice)
4.7/5 (78)
(78) When firms in a competitive market have different costs,it is likely that
(Multiple Choice)
4.9/5 (78)
(78) Carla's Candy Store is maximizing profits by producing 1,000 pounds of candy per day.If Carla's fixed costs unexpectedly increase and the market price remains constant,then the short run profit-maximizing level of output
(Multiple Choice)
4.8/5 (73)
(73) If there is an increase in market demand in a perfectly competitive market,then in the short run
(Multiple Choice)
4.7/5 (75)
(75) A competitive firm has been selling its output for $20 per unit and has been maximizing its profit,which is positive.Then,the price rises to $25 and the firm makes whatever adjustments are necessary to maximize its profit at the now-higher price.Once the firm has adjusted,which of the following statements is correct?
(Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)