



 Chat with AI
Exam 7: Consumers, producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics237 Questions
Exam 2: Thinking Like an Economist267 Questions
Exam 3: Interdependence and the Gains From Trade217 Questions
Exam 4: The Market Forces of Supply and Demand303 Questions
Exam 5: Elasticity and Its Applications282 Questions
Exam 6: Supply, demand, and Government Policies252 Questions
Exam 7: Consumers, producers, and the Efficiency of Markets248 Questions
Exam 8: Application: the Costs of Taxation245 Questions
Exam 9: Application: International Trade245 Questions
Exam 10: Externalities288 Questions
Exam 11: Public Goods and Common Resources258 Questions
Exam 12: The Design of the Tax System328 Questions
Exam 13: The Costs of Production303 Questions
Exam 14: Firms in Competitive Markets271 Questions
Exam 15: Monopoly306 Questions
Exam 16: Oligopoly291 Questions
Exam 17: Monopolistic Competition257 Questions
Exam 18: The Markets for the Factors of Production284 Questions
Exam 19: Earnings and Discrimination286 Questions
Exam 20: Income Inequality and Poverty247 Questions
Exam 21: The Theory of Consumer Choice238 Questions
Exam 22: Frontiers of Microeconomics199 Questions
Exam 23: Measuring a Nations Income215 Questions
Exam 24: Measuring the Cost of Living208 Questions
Exam 25: Production and Growth240 Questions
Exam 26: Saving, investment, and the Financial System282 Questions
Exam 27: The Basic Tools of Finance249 Questions
Exam 28: Unemployment242 Questions
Exam 29: The Monetary System277 Questions
Exam 30: Money Growth and Inflation224 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts256 Questions
Exam 32: A Macroeconomic Theory of the Open Economy217 Questions
Exam 33: Aggregate Demand and Aggregate Supply302 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand249 Questions
Exam 35: The Short Run Trade Off Between Inflation and Unemployment246 Questions
Exam 36: Five Debates Over Macroeconomic Policy140 Questions
Select questions type


Donald produces nails at a cost of $200 per ton.If he sells the nails for $350 per ton,his producer surplus per ton is
(Multiple Choice)
5.0/5  (79)
(79) If the government allowed a free market for transplant organs (such as kidneys)to exist,
(Multiple Choice)
4.9/5 (77)
(77) The Surgeon General announces that eating chocolate increases tooth decay.As a result,the equilibrium price of chocolate
(Multiple Choice)
4.8/5 (76)
(76) Given the following equations two equations:
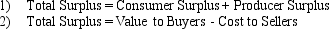 Show how equation (1)can be used to derive equation (2).
 (Essay)
4.9/5 (84)
(84) Figure 7-8
 -Refer to Figure 7-8.If the government mandated a price increase from Pₑ to a higher price,then
 (Multiple Choice)
4.8/5 (78)
(78) Market Supply and Demand for Pepperoni Pizza
Table 7-5
 -Refer to Table 7-5.At a price of $4.00,total surplus is
 (Multiple Choice)
5.0/5 (97)
(97) A simultaneous increase in both the demand for radios and the supply of radios would imply that
(Multiple Choice)
4.8/5 (75)
(75) Suppose Lauren,Leslie and Lydia all purchase bulletin boards for their rooms for $15 each.Lauren's willingness to pay was $35,Leslie's willingness to pay was $25,and Lydia's willingness to pay was $30.Total consumer surplus for these three would be
(Multiple Choice)
4.9/5 (75)
(75) Figure 7-6
 -Refer to Figure 7-6.When the price falls from P₂ to P₁,producer surplus
 (Multiple Choice)
4.9/5 (90)
(90) Figure 7-10
 -Refer to Figure 7-10.The equilibrium (market-clearing)price is
 (Multiple Choice)
4.7/5 (96)
(96) Figure 7-8
-Refer to Figure 7-8.Buyers who value this good less than price are represented by which line segment?
-Refer to Figure 7-8.Buyers who value this good less than price are represented by which line segment? (Multiple Choice)
4.8/5 (94)
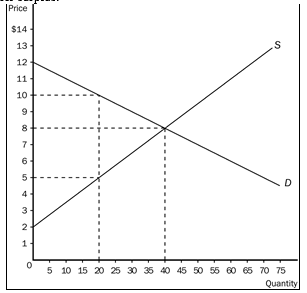
(94) Answer the following questions based on the graph that represents J.R.'s demand for ribs per week of ribs at Judy's rib shack.
a.At the equilibrium price, how many ribs would J.R.be willing to purchase?
b.How much is J.R.willing to pay for 20 ribs?
c.What is the magnitude of J.R.'s consumer surplus be at the equilibrium price?
d.At the equilibrium price, how many ribs would Judy be willing to sell?
e.How high must the price of ribs be for Judy to supply 20 ribs to the market?
f.At the equilibrium price, what is the magnitude of total surplus in the market?
g.If the price of ribs rose to $10, what would happen to J.R.'s consumer surplus?
h.If the price of ribs fell to $5, what would happen to Judy's producer surplus?
i.Explain why the graph that is shown verifies the fact that the market equilibrium (quantity) maximizes the sum of producer and consumer surplus.
(Essay)
4.8/5 (88)
(88) Market Supply and Demand for Pepperoni Pizza
Table 7-5
-Refer to Table 7-5.As the table suggests,the demand curve is a straight line and so is the supply curve.Taking this into account,when there is equilibrium,consumer surplus is
-Refer to Table 7-5.As the table suggests,the demand curve is a straight line and so is the supply curve.Taking this into account,when there is equilibrium,consumer surplus is (Multiple Choice)
5.0/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)