



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics483 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity530 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action205 Questions
Exam 8: Utility and Demand366 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition318 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality351 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


What is the relationship between the price, P, and the average total cost, ATC, for a firm in perfect competition that makes an economic profit? That makes zero economic profit? That incurs an economic loss?
(Essay)
4.7/5  (69)
(69) Fresno County, California is the largest agricultural producing county in the country and almonds are an important crop with more than 99,000 acres harvested. Each acre produces about a ton of almonds and sold at a price of $4300 a ton. The Sagardia Brothers grew 600 acres of almonds. How many tons would the brothers sell if they priced the almonds at $4500 a ton?
(Multiple Choice)
4.8/5 (78)
(78) Fresno County, California is the largest agricultural producing county in the country and almonds are an important crop with more than 99,000 acres harvested. Each acre produces about a ton of almonds and sold at a price of $4300 a ton. The Sagardia Brothers grew 600 acres of almonds. What would happen if the Sagardia Brothers priced their almonds at $4500 a ton?
(Multiple Choice)
4.9/5 (79)
(79) A perfectly competitive firm maximizes its economic profit when it produces the quantity that sets
(Multiple Choice)
4.9/5 (80)
(80) As long as it does NOT shut down, a profit-maximizing perfectly competitive firm will
(Multiple Choice)
4.8/5 (86)
(86) 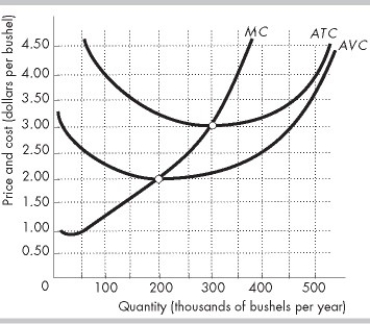 -The figure above shows a typical perfectly competitive corn farm, whose marginal cost curve is MC and average total cost curve is ATC. The market is initially in a long-run equilibrium, where the price is $3.00 per bushel. Then, the market demand for corn decreases and, in the short run, the price falls to $2.50 per bushel. In the new short-run equilibrium, the farm produces ________ bushels of corn and sells corn at ________ per bushel.
 (Multiple Choice)
4.8/5 (76)
(76) When a firm is considered to be a "price taker" that means that the firm
(Multiple Choice)
4.9/5 (76)
(76) Why is the demand for a perfectly competitive firm's good perfectly elastic even though the market demand is not?
(Essay)
4.8/5 (84)
(84) 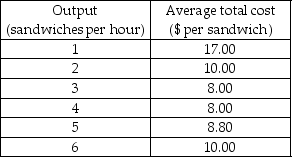 -The table above shows output and costs of Evan's Subs, a typical perfectly competitive firm in a local market for sandwiches. Evan's fixed cost is $9 per hour. The current market price of a sandwich is $6. What is Evan's shut-down price?
 (Multiple Choice)
4.9/5 (72)
(72) 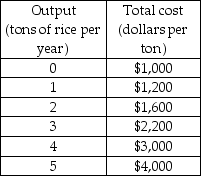 -Based on the table above which shows Chip's costs, if rice sells for $600 a ton, Chip's profit-maximizing output is
 (Multiple Choice)
4.9/5 (70)
(70) John keeps beehives and sells 100 quarts of honey per month. The honey market is perfectly competitive, and the price of a quart of honey is $10. John has an average variable cost of $5 and an average fixed cost of $3. At 100 quarts per month, John's marginal cost is $10.
a) Is John maximizing his profit? If not, what should John do?
b) Calculate John's total revenue, total cost, and total economic profit or economic loss when he produces 100 quarts of honey.
(Essay)
4.8/5 (89)
(89) "For a perfectly competitive market, an economic profit attracts new firms. But when these firms enter the market, the price falls and the economic profit is eliminated." Are the previous statements correct or incorrect? What is the long-run profit or loss outcome for firms in a perfectly competitive market?
(Essay)
4.8/5 (68)
(68) Perfectly competitive firms will sometimes operate even though they incur an economic loss in the short run.
(True/False)
4.8/5 (97)
(97) Suppose that newspaper companies are now required to use recycled paper, which is more expensive than new paper. Which of the following is most likely to result if the newspaper industry is highly competitive?
(Multiple Choice)
4.8/5 (88)
(88) Individual firms in perfectly competitive industries are price takers because
(Multiple Choice)
5.0/5 (72)
(72) 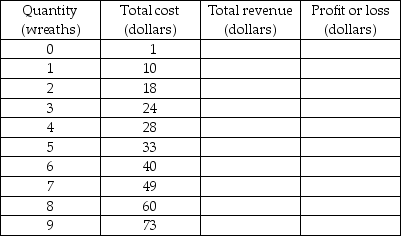 -The above table gives Amy's total cost schedule for producing holiday wreaths. Amy is a perfect competitor and can sell each wreath for $9.
a) Complete the table by calculating Amy's total revenue and her profit or loss schedule.
b) When Amy is producing 4 wreaths, what is her total cost? What is her total revenue? What is her economic profit or economic loss?
c) What number of wreaths maximizes Amy's profit?
-The above table gives Amy's total cost schedule for producing holiday wreaths. Amy is a perfect competitor and can sell each wreath for $9.
a) Complete the table by calculating Amy's total revenue and her profit or loss schedule.
b) When Amy is producing 4 wreaths, what is her total cost? What is her total revenue? What is her economic profit or economic loss?
c) What number of wreaths maximizes Amy's profit? (Essay)
4.8/5 (89)
(89) Because of a decrease in the wage rate it must pay, a perfectly competitive firm's marginal costs decrease but its demand curve stays the same. As a result, the firm
(Multiple Choice)
4.8/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)