



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics483 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity530 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action205 Questions
Exam 8: Utility and Demand366 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition318 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality351 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


A perfectly competitive firm definitely will shut down in the short run if its price is below its average total cost.
(True/False)
4.9/5  (85)
(85) The apple market is perfectly competitive and is in long-run equilibrium. Now a disease kills 50 percent of the apple orchards. In the short run, the price of a bag of apples ________ and the remaining apple growers make ________ economic profit. In the long run, the ________.
(Multiple Choice)
4.9/5 (67)
(67) In a perfectly competitive market, if a firm finds it is producing an amount of output such that its marginal cost exceeds its price, it will
(Multiple Choice)
4.9/5 (71)
(71) In the long run, for a perfectly competitive market, if economic profit is
(Multiple Choice)
4.8/5 (84)
(84) In a perfectly competitive market, which of the following will increase the economic profit the firms make in the short run?
(Multiple Choice)
4.8/5 (83)
(83) 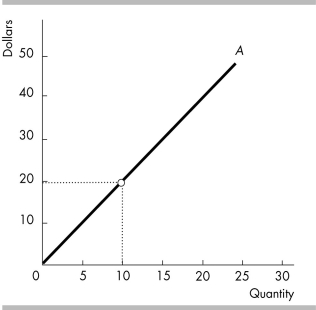 -For a perfectly competitive firm, curve A in the above figure is the firm's
 (Multiple Choice)
4.8/5 (73)
(73) In the long run, perfectly competitive firms make zero economic profit, that is, their owners make a normal profit.
(True/False)
4.8/5 (69)
(69) Suppose a perfectly competitive market is in a long-run equilibrium when a permanent decrease in the market demand occurs. In the long run, which of the following definitely occurs?
(Multiple Choice)
4.9/5 (73)
(73) 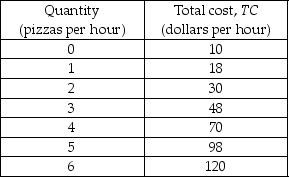 -Giuseppe's Pizza is a perfectly competitive firm. The firm's costs are shown in the table above. If the market price is $20, what is Giuseppe's profit-maximizing output?
 (Multiple Choice)
4.7/5 (73)
(73) 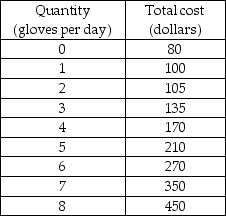 -The above table shows the per day total cost for Kiley's Baseball Glove Company. Each glove is priced at $50 and Kiley's Baseball Glove Company is a perfectly competitive firm. Between which two amounts of output does Kiley's Baseball Glove Company make an economic profit?
 (Multiple Choice)
4.7/5 (79)
(79)
-Giuseppe's Pizza is a perfectly competitive firm. The firm's costs are shown in the table above. The firm's shutdown point is
-Giuseppe's Pizza is a perfectly competitive firm. The firm's costs are shown in the table above. The firm's shutdown point is (Multiple Choice)
4.9/5 (96)
(96) During the first half of the 2000s, the price of pork rose. After that, within a couple of years the price fell back to about the level before the initial increase. What might have led to these events?
(Essay)
5.0/5 (84)
(84) Which of the following best describes the short-run supply curve for an individual perfectly competitive firm?
(Multiple Choice)
5.0/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)