



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics483 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity530 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action205 Questions
Exam 8: Utility and Demand366 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition318 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality351 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


The break-even point is defined as occurring at an output rate at which
(Multiple Choice)
4.8/5  (85)
(85) If the market for maple syrup is perfectly competitive, then in the long-run equilibrium, firms are
(Multiple Choice)
4.8/5 (84)
(84) Can a perfectly competitive firm make an economic profit in the short run? Can it incur an economic loss?
(Essay)
4.9/5 (87)
(87) 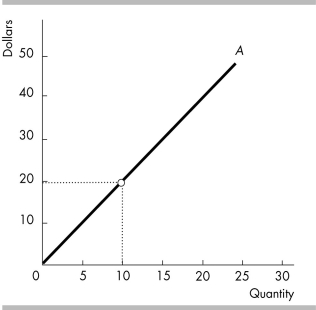 -In the above figure showing a perfectly competitive firm's total revenue line, the firm's marginal revenue
 (Multiple Choice)
4.9/5 (88)
(88) In a perfectly competitive market, the price elasticity of demand for the market demand is ________ and the price elasticity of demand for an individual firm's demand is ________.
(Multiple Choice)
4.8/5 (80)
(80) The section of the marginal cost curve that lies above the average variable cost curve is
(Multiple Choice)
4.8/5 (76)
(76) In a perfectly competitive market, many firms sell an identical product.
(True/False)
4.9/5 (80)
(80) 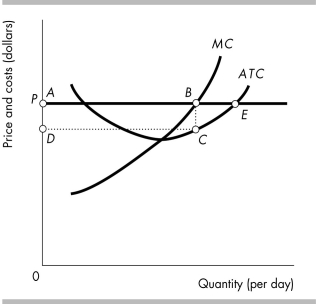 -Consider the perfectly competitive firm in the figure above. At the profit maximizing level of output, the firm will
 (Multiple Choice)
4.9/5 (70)
(70) 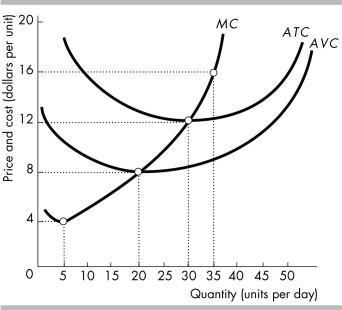 -In the above figure, at what price does a perfectly competitive firm make zero economic profit?
 (Multiple Choice)
5.0/5 (80)
(80) In a perfectly competitive market that is in long-run equilibrium, a permanent leftward shift in the market demand curve
(Multiple Choice)
4.9/5 (92)
(92) Homer's Holesome Donuts has determined that its profit-maximizing quantity is 10,000 donuts per year. Homer's earns $12,000 in revenue from the sale of those donuts. Homer's has two costs. First he pays $16,000 in annual rental payments for its five-year lease on its store. Second Homer incurs an additional cost of $5,000 for ingredients. Should Homer's shut down in the short run?
(Multiple Choice)
4.9/5 (76)
(76) 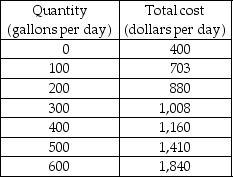 -Petunia's Farm produces and sells milk. The market for milk is perfectly competitive. The market price of milk is $2.50 per gallon. The relationship between the farm's output and total costs is shown in the table above.
a) Draw Petunia's average variable, average total, and marginal cost curves.
b) Use your graphs to find Petunia's profit-maximizing output.
c) If Petunia maximizes her profit, how much profit does she make?
d) What is Petunia's shutdown point? What is her economic profit at the shut-down point?
e) Should Petunia shut down? Will farms with costs the same as Petunia's enter or exit the milk market? Explain.
-Petunia's Farm produces and sells milk. The market for milk is perfectly competitive. The market price of milk is $2.50 per gallon. The relationship between the farm's output and total costs is shown in the table above.
a) Draw Petunia's average variable, average total, and marginal cost curves.
b) Use your graphs to find Petunia's profit-maximizing output.
c) If Petunia maximizes her profit, how much profit does she make?
d) What is Petunia's shutdown point? What is her economic profit at the shut-down point?
e) Should Petunia shut down? Will farms with costs the same as Petunia's enter or exit the milk market? Explain. (Essay)
4.9/5 (84)
(84) 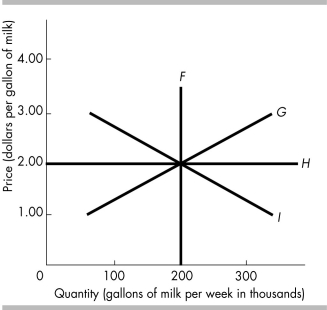 -In the above figure, if the milk industry is perfectly competitive, then the firm's marginal revenue curve is represented by
 (Multiple Choice)
4.8/5 (83)
(83)
-The figure above portrays a total revenue curve for a perfectly competitive firm. The firm's marginal revenue from selling a unit of output
-The figure above portrays a total revenue curve for a perfectly competitive firm. The firm's marginal revenue from selling a unit of output (Multiple Choice)
4.8/5 (87)
(87) Initially, a perfectly competitive industry that has 1,000 firms is in long-run equilibrium. Then 100 firms in the industry adopt a new technology that reduces the average cost of producing the good. In the short run, the price ________, firms with the new technology make ________ economic profit, and firms with the old technology ________.
(Multiple Choice)
4.9/5 (77)
(77) The demand for wheat from farm A is perfectly elastic because wheat from farm A is
(Multiple Choice)
4.8/5 (72)
(72) 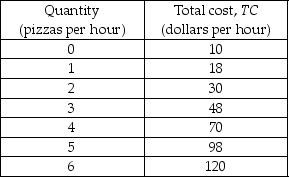 -Giuseppe's Pizza is a perfectly competitive firm. The firm's costs are shown in the table above. If the market price is $15, what is Giuseppe's profit-maximizing output?
 (Multiple Choice)
4.9/5 (73)
(73) In perfect competition, the market demand for the good ________ perfectly elastic and the demand for the output of one firm ________ perfectly elastic.
(Multiple Choice)
4.8/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)