



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics483 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity530 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action205 Questions
Exam 8: Utility and Demand366 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition318 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality351 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


Which of the following characterizes a perfectly competitive market?

Free
(Multiple Choice)
4.8/5  (82)
(82) Correct Answer: Verified
B
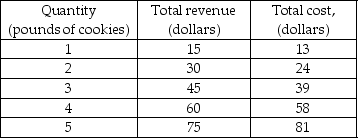 -The table above gives the total revenue and total cost for a perfectly competitive firm producing chocolate chip cookies. If the firm is producing 1 pound of cookies, to maximize its profit it will
Free
(Multiple Choice)
4.9/5 (78)
(78) Correct Answer:Verified
VerifiedA
The short-run market supply curve for a perfectly competitive market is obtained by summing the part of each firm's
(Multiple Choice)
4.9/5 (70)
(70) In the long run, the economic profit of a firm in a perfectly competitive market
(Multiple Choice)
4.8/5 (70)
(70) A perfectly competitive firm is definitely making an economic profit when
(Multiple Choice)
4.8/5 (80)
(80) In a perfectly competitive market, an increase in market demand
(Multiple Choice)
4.7/5 (70)
(70) Which of the following four firms would most likely NOT be part of a perfectly competitive market?
(Multiple Choice)
4.8/5 (78)
(78) The short-run supply curve for a perfectly competitive firm is its
(Multiple Choice)
4.8/5 (83)
(83) A perfectly competitive firm will shut down rather than produce if its
(Multiple Choice)
4.8/5 (74)
(74) In a perfectly competitive market, the market supply curve is the sum of the
(Multiple Choice)
4.7/5 (67)
(67) 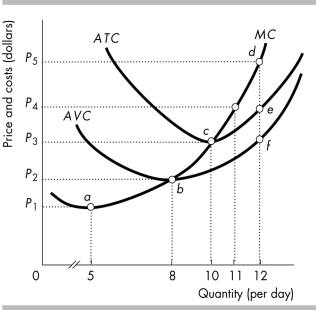 -The figure above shows a firm in a perfectly competitive market. The firm will shut down if price falls below
 (Multiple Choice)
4.7/5 (77)
(77) Entry of new firms into a perfectly competitive market lowers the profits of the existing firms.
(True/False)
4.9/5 (76)
(76) Homer's Holesome Donuts has determined that its profit-maximizing quantity is 10,000 donuts per year. Homer's earns $12,000 in revenue from the sale of those donuts. Homer's has two costs. First he pays $16,000 in annual rental payments for its five-year lease on its store. Second Homer incurs an additional cost of $5,000 for ingredients. Homer's variable cost is equal to
(Multiple Choice)
4.8/5 (83)
(83) When the market demand increases in a perfect competition, the long-run result is a larger number of firms, a higher price, and a permanent economic profit for the firms.
(True/False)
4.9/5 (76)
(76) Because the demand for a perfectly competitive firm's product is perfectly elastic, marginal revenue is equal to
(Multiple Choice)
4.9/5 (88)
(88) Hubert's Copy Services is in perfect competition. Hubert currently charges 10 cents per page, which is the going market price. He thinks that he can increase his profit by raising the price. Is it possible? Why or why not?
(Essay)
4.7/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)