



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics483 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity530 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action205 Questions
Exam 8: Utility and Demand366 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition318 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality351 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


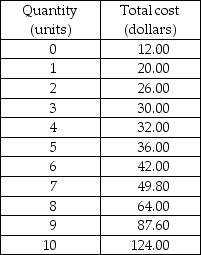 -Acme is a perfectly competitive firm. It has the total cost schedule given in the above table. Acme's product sells for $8.00 per unit. What amount of output is the most profitable and what is Acme's economic profit or economic loss?
 (Essay)
4.9/5  (83)
(83) Ellen's Painting Services is a perfectly competitive firm that currently paints 10 houses a month and charges $100 per house, which is the going market price. Ellen's marginal cost is positively related with the quantity of service she provides and is currently $120. What should Ellen do to increase her economic profit? Paint more houses? Raise her price? Explain your answer.
(Essay)
4.9/5 (74)
(74) For a perfectly competitive firm, as its output increases its marginal revenue ________ and its marginal cost ________.
(Multiple Choice)
4.8/5 (78)
(78) The smallest quantity of output at which long-run average cost is at a minimum is a firm's
(Multiple Choice)
4.8/5 (82)
(82) 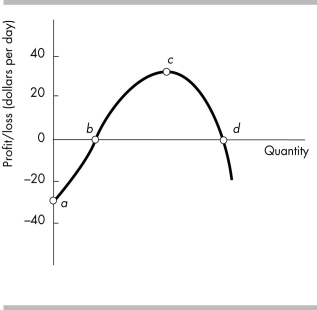 -In the above figure, when the firm produces output corresponding to point c, the firm's marginal cost
 (Multiple Choice)
4.8/5 (72)
(72) Will a perfectly competitive firm ever produce in the short run even though it is incurring an economic loss?
(Essay)
4.9/5 (78)
(78) In the long-run equilibrium, perfectly competitive firms make zero economic profit because of
(Multiple Choice)
4.9/5 (83)
(83) In the long run, the firms in a perfectly competitive market
(Multiple Choice)
4.7/5 (88)
(88) For prices above the minimum average variable cost, a perfectly competitive firm's supply curve is
(Multiple Choice)
4.9/5 (91)
(91) 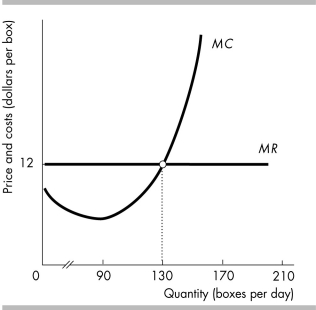 -Carol's Candies is producing 150 boxes of candy a day. Carol's marginal revenue and marginal cost curves are shown in the figure above. To increase her profit, Carol should
 (Multiple Choice)
4.8/5 (84)
(84) 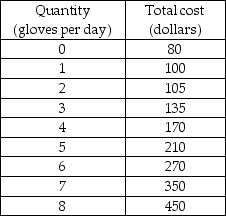 -The above table shows the per day total cost for Kiley's Baseball Glove Company. Each glove is priced at $50 and Kiley's Baseball Glove Company is a perfectly competitive firm. At which of the following amounts of output is the economic profit maximized for Kiley's Baseball Glove Company?
 (Multiple Choice)
4.8/5 (83)
(83) 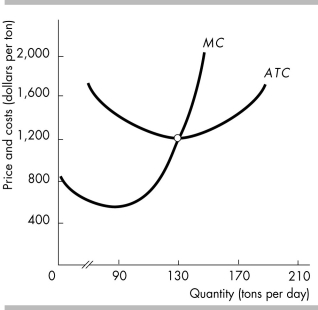 -The figure above shows the costs for the typical grower in the perfectly competitive turnip market. Currently, the price of a ton of turnips is $1,200. The demand for turnips increases permanently. The turnip industry experiences neither external economies nor external diseconomies. In the long run, the price of a ton of turnips
 (Multiple Choice)
4.9/5 (66)
(66) If a perfectly competitive market is in long-run equilibrium and there is a permanent decrease in demand, then
(Multiple Choice)
4.9/5 (76)
(76) In the long-run equilibrium for a perfectly competitive market
(Multiple Choice)
4.8/5 (90)
(90) "Higher ethanol production definitely and directly raises the price of corn," said USDA economist Ephraim Leibtag. In the long run in the corn market, what is TRUE if the production of ethanol increases?
(Multiple Choice)
4.9/5 (79)
(79) In a perfectly competitive market that is in long-run equilibrium, which of the following will NOT occur?
(Multiple Choice)
4.9/5 (66)
(66) Which of the following is NOT an assumption of perfect competition?
(Multiple Choice)
4.9/5 (85)
(85) A perfectly competitive firm initially is earning zero economic profit. Then, a decrease in demand for the firm's product occurs. Of the following, in the long run which action listed below is the firm most likely to take?
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)