



 Chat with AI
Exam 12: Perfect Competition

Exam 1: What Is Economics483 Questions
Exam 2: The Economic Problem440 Questions
Exam 3: Demand and Supply515 Questions
Exam 4: Elasticity530 Questions
Exam 5: Efficiency and Equity450 Questions
Exam 6: Government Actions in Markets412 Questions
Exam 7: Global Markets in Action205 Questions
Exam 8: Utility and Demand366 Questions
Exam 10: Organizing Production385 Questions
Exam 11: Output and Costs493 Questions
Exam 12: Perfect Competition487 Questions
Exam 13: Monopoly599 Questions
Exam 14: Monopolistic Competition318 Questions
Exam 15: Oligopoly276 Questions
Exam 16: Public Choices, Public Goods, and Healthcare205 Questions
Exam 17: Externalities437 Questions
Exam 18: Markets for Factors of Production382 Questions
Exam 19: Economic Inequality351 Questions
Exam 20: Uncertainty and Information233 Questions
Select questions type


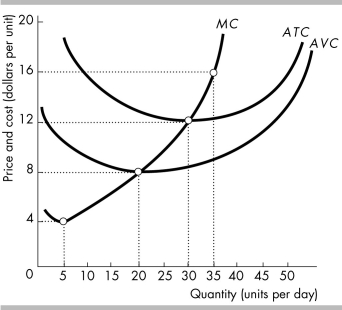 -In the above figure, if the price is $12 per unit, how many units will a profit maximizing perfectly competitive firm produce?
 (Multiple Choice)
4.8/5  (73)
(73) 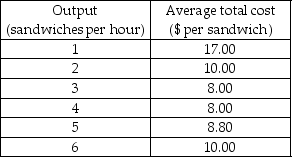 -The table above shows output and costs of Evan's Subs, a typical perfectly competitive firm in a local market for sandwiches. Evan's fixed cost is $9 per hour. The current market price of a sandwich is $6. What quantity of sandwiches produced will maximize Evan's economic profit in the short run?
 (Multiple Choice)
4.8/5 (78)
(78) 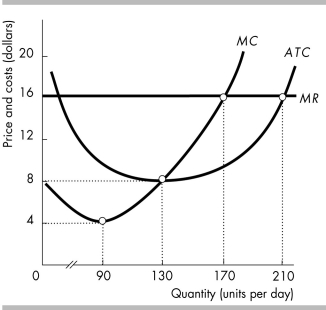 -The figure above shows the marginal revenue and costs of a perfectly competitive firm. The marginal cost of the last unit produced is
 (Multiple Choice)
4.8/5 (77)
(77) Which of the following is NOT present in a perfectly competitive market?
(Multiple Choice)
4.8/5 (81)
(81) If Steve's Apple Orchard, Inc. is a perfectly competitive firm, the demand for Steve's apples has
(Multiple Choice)
4.9/5 (79)
(79) 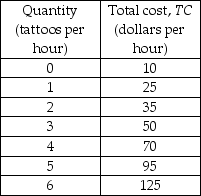 -Archibald's Tattoos is a perfectly competitive firm. The firm's costs are shown in the table above. If the market price of a tattoo is $17.50, what is the firm's economic profit?
 (Multiple Choice)
4.9/5 (79)
(79) "Higher ethanol production definitely and directly raises the price of corn," said USDA economist Ephraim Leibtag. In the long run in the corn market, what is TRUE if the production of ethanol increases?
(Multiple Choice)
4.9/5 (69)
(69) 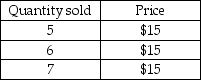 -In the above table, if the quantity sold by the firm rises from 6 to 7, its marginal revenue is
 (Multiple Choice)
4.8/5 (83)
(83) The difference between a perfectly competitive firm's total revenue and its total cost is
(Multiple Choice)
4.8/5 (72)
(72) All along the beach in San Diego, California are shops which rent boogie boards by the hour. Tourists perceive that all rental boogie boards are identical, all prices are clearly listed on signs in front of the shops, and there are no restrictions on entry and exit in the boogie board market. Suppose Surf's Up is a boogie board rental shop. What is the shape of Surf's Up's demand curve as compared to the market demand curve?
(Multiple Choice)
4.7/5 (88)
(88) 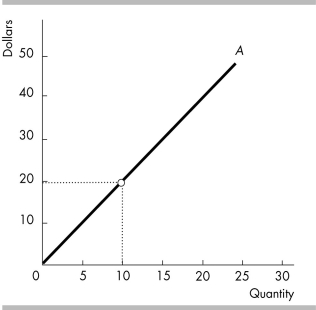 -The figure above portrays a total revenue curve for a perfectly competitive firm. The price of the product in this industry
 (Multiple Choice)
4.9/5 (81)
(81) 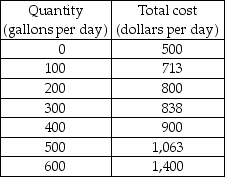 -Brennan's Farm produces and sells milk. The market for milk is perfectly competitive. The market price of milk is $2.50 per gallon. The relationship between the farm's output and total costs is shown in the table above.
a) Draw Brennan's average variable, average total, and marginal cost curves.
b) Use your graphs to find Brennan's profit-maximizing output.
c) If Brennan maximizes his profit, how much profit does he make?
d) Should Brennan stay in business? Will other farms with costs the same as Brennan's enter the milk market? Explain.
-Brennan's Farm produces and sells milk. The market for milk is perfectly competitive. The market price of milk is $2.50 per gallon. The relationship between the farm's output and total costs is shown in the table above.
a) Draw Brennan's average variable, average total, and marginal cost curves.
b) Use your graphs to find Brennan's profit-maximizing output.
c) If Brennan maximizes his profit, how much profit does he make?
d) Should Brennan stay in business? Will other farms with costs the same as Brennan's enter the milk market? Explain. (Essay)
4.9/5 (87)
(87) Fresno County, California is the largest agricultural producing county in the country and almonds are an important crop with more than 99,000 acres harvested. Each acre produces about a ton of almonds and sold at a price of $4300 a ton. The Sagardia Brothers grew 600 acres of almonds that year and they are price takers. What is the Brother's total revenue?
(Multiple Choice)
4.8/5 (92)
(92) A perfectly competitive industry is in long-run equilibrium. Some firms in the industry adopt new technology that reduces the average total cost of producing the good. In the long run, the price is ________, firms with the new technology make ________ economic profit, and firms with the old technology ________.
(Multiple Choice)
4.9/5 (83)
(83) 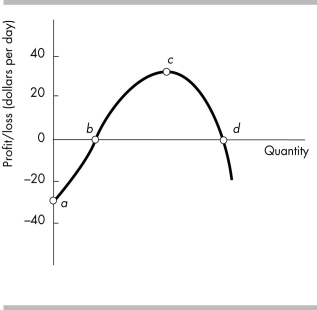 -In the above figure, the firm is incurring an economic loss at
 (Multiple Choice)
4.9/5 (83)
(83) 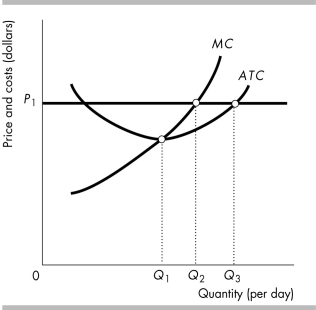 -In the above figure, if the price is P1, the firm will produce
 (Multiple Choice)
5.0/5 (79)
(79)
-The figure above shows the marginal revenue and costs of a perfectly competitive firm. When 170 units are produced, the
-The figure above shows the marginal revenue and costs of a perfectly competitive firm. When 170 units are produced, the (Multiple Choice)
4.8/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)