



 Chat with AI
Exam 16: Monopolistic Competition

Exam 1: Ten Principles of Economics220 Questions
Exam 2: Thinking Like an Economist284 Questions
Exam 3: Interdependence and the Gains From Trade192 Questions
Exam 4: The Market Forces of Supply and Demand277 Questions
Exam 5: Elasticity and Its Application222 Questions
Exam 6: Supply, Demand, and Government Policies321 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets218 Questions
Exam 8: Applications: The Costs of Taxation203 Questions
Exam 9: Application: International Trade214 Questions
Exam 10: Externalities204 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System225 Questions
Exam 13: The Costs of Production261 Questions
Exam 14: Firms in Competitive Markets243 Questions
Exam 15: Monopoly231 Questions
Exam 16: Monopolistic Competition246 Questions
Exam 17: Oligopoly204 Questions
Exam 18: The Markets for the Factors of Production232 Questions
Exam 19: Earnings and Discrimination230 Questions
Exam 20: Income Inequality and Poverty194 Questions
Exam 21: The Theory of Consumer Choice209 Questions
Exam 22: Frontiers in Microeconomics185 Questions
Exam 23: Measuring a Nations Income231 Questions
Exam 24: Measuring the Cost of Living214 Questions
Exam 25: Production and Growth187 Questions
Exam 26: Saving, Investment, and the Financial System225 Questions
Exam 27: Tools of Finance198 Questions
Exam 28: Unemployment and Its Natural Rate361 Questions
Exam 29: The Monetary System210 Questions
Exam 30: Money Growth and Inflation201 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts194 Questions
Exam 32: A Macroeconomic Theory of the Open Economy188 Questions
Exam 33: Aggregate Demand and Aggregate Supply189 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand207 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment223 Questions
Exam 36: Six Debates Over Macroeconomic Policy154 Questions
Select questions type


Figure 16-3  -Refer to Figure 16-3. At the profit-maximizing, or loss-minimizing, output level, how many units of output will the firm in this figure produce?
 (Multiple Choice)
4.8/5  (82)
(82) The fact that monopolistically competitive firms charge a price that exceeds marginal cost is responsible for the
(Multiple Choice)
4.8/5 (69)
(69) If a firm in a monopolistically competitive market successfully uses advertising to decrease the elasticity of demand for its product, the firm will
(Multiple Choice)
4.7/5 (79)
(79) Free entry eliminates long-run profits for firms in competitive and monopolistic industries.
(True/False)
4.7/5 (66)
(66) When the loss from a business-stealing externality exceeds the gain from a product-variety externality,
(Multiple Choice)
5.0/5 (69)
(69) Figure 16-6
The figure is drawn for a monopolistically competitive firm. 
-Refer to Figure 16-6. The firm's maximum profit
-Refer to Figure 16-6. The firm's maximum profit (Multiple Choice)
4.9/5 (61)
(61) Figure 16-9
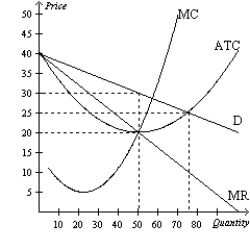
-Refer to Figure 16-9. If this firm profit-maximizes, what price will it charge?
-Refer to Figure 16-9. If this firm profit-maximizes, what price will it charge? (Short Answer)
4.8/5 (82)
(82) In the debate between the critics and defenders of advertising, what conclusion have policymakers come to regarding the effect of advertising on competition - advertising makes markets more competitive or less competitive?
(Essay)
4.9/5 (82)
(82) Scenario 16-4
Peter operates an ice cream shop in the center of Fairfield. He sells several unusual flavors of organic, homemade ice cream so he has a monopoly over his own ice cream, though he competes with many other firms selling ice cream in Fairfield for the same customers. Peter's demand and cost values for sales per day are given in the table below. (Everyone who purchases Peter's ice cream buys a double scoop cone because it's so delicious.)
Quantity Price MR MC ATC 20 \ 5.60 \ 5.20 \ 2.20 \ 2.05 40 \ 5.20 \ 4.40 \ 2.40 \ 2.10 60 \ 4.80 \ 3.60 \ 2.60 \ 2.15 80 \ 4.40 \ 2.80 \ 2.80 \ 2.20 100 \ 4.00 \ 2.00 \ 3.00 \ 2.25 120 \ 3.60 \ 1.20 \ 3.20 \ 2.30 140 \ 3.20 \ 0.40 \ 3.40 \ 2.35 160 \ 2.80 -\ 0.40 \ 3.60 \ 2.40 180 \ 2.40 -\ 1.20 \ 3.80 \ 2.45
-Refer to Scenario 16-4. How many ice cream cones should Peter sell in one day to maximize his profits?
(Short Answer)
4.9/5 (72)
(72) In a market that is characterized by imperfect competition,
(Multiple Choice)
4.9/5 (88)
(88) Scenario 16-6
Dean goes to the grocery store to buy chips and soda for a party. He purchases brand name products even though generic versions are available at lower prices. His friend John says he was irrational to spend more for a nearly identical product. His friend Martina agreed with Dean's decision to spend more for the brand name products.
-Refer to Scenario 16-6. Which friend is a critic of brand names?
(Short Answer)
4.8/5 (71)
(71) Figure 16-4
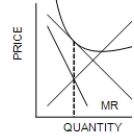
Graph (a)
 Graph (b)
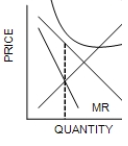 Graph (c)
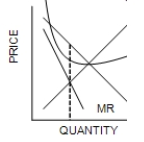 Graph (d)
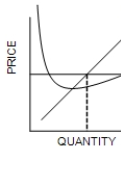
-Refer to Figure 16-4. Graph (b) is consistent with a firm in a monopolistically competitive market that is
Graph (b)
Graph (c)
Graph (d)
-Refer to Figure 16-4. Graph (b) is consistent with a firm in a monopolistically competitive market that is (Multiple Choice)
4.9/5 (85)
(85) Table 16-1
The following table shows the output produced by each of the top eight firms in four industries as well as the total industry output for those industries.
Firm Industry A Industry B Industry C Industry D 1 50,000 18,000 37,000 40,000 2 47,000 17,750 36,500 39,000 3 43,000 17,250 35,500 37,000 4 38,000 16,500 34,000 34,000 5 32,000 15,500 32,000 30,000 6 25,000 14,250 29,500 25,000 7 17,000 12,750 26,500 19,000 8 8,000 11,000 23,000 12,000 Total
-Refer to Table 16-1. Which industry has the lowest concentration ratio?
(Multiple Choice)
4.9/5 (74)
(74) Monopolistic competition is the only market structure that features many sellers.
(True/False)
4.8/5 (83)
(83) Which of the following industries has the highest concentration ratio?
(Multiple Choice)
4.9/5 (79)
(79) In markets where the government imposes an excise tax on unit sales, it also has a tendency to dabble with restrictions on advertising (for example, cigarettes and hard liquor). Do potential (or actual) restrictions on advertising in these markets serve the interest of a government that is interested in maximizing its tax revenue from the sale of these products? Explain your answer.
(Essay)
4.7/5 (72)
(72) Entry of new firms in monopolistically competitive industries can convey a negative externality on producers because firms lose customers and profits from the entry of new competitors. This externality is called the
(Short Answer)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)