



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law92 Questions
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities65 Questions
Exam 3: Corporations: Introduction and Operating Rules105 Questions
Exam 4: Corporations: Organization and Capital Structure108 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions129 Questions
Exam 6: Corporations: Redemptions and Liquidations117 Questions
Exam 7: Corporations: Reorganizations139 Questions
Exam 8: Consolidated Tax Returns154 Questions
Exam 9: Taxation of International Transactions128 Questions
Exam 10: Partnerships: Formation, Operations, and Basis163 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations164 Questions
Exam 12: S Corporations121 Questions
Exam 13: Comparative Forms of Doing Business113 Questions
Exam 14: Taxes on the Financial Statements71 Questions
Exam 15: Exempt Entities129 Questions
Exam 16: Multistate Corporate Taxation184 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes145 Questions
Exam 19: Family Tax Planning118 Questions
Exam 20: Income Taxation of Trusts and Estates166 Questions
Select questions type


The Rack, Spill, and Ton corporations file Federal income tax returns on a consolidated basis. The group's tax return currently is under audit. Under a valid tax-sharing agreement, each corporation is liable for one-third of the group's consolidated tax liability. The affiliates have agreed with the auditor that the group's unpaid tax liability for the year is $90,000. Because of an incorrect tax return position, another $3,000 in interest and an $18,000 penalty is attributable solely to Ton.
At present, only Rack is solvent and has the cash with which to make such a tax payment. What is the maximum amount for which the government could be successful in forcing Rack to satisfy the outstanding liabilities of the consolidated group?
(Multiple Choice)
4.9/5  (80)
(80) When a member departs from a consolidated group, it leaves behind any NOLs that it generated while in the group.
The parent corporation and remaining affiliates apply those NOLs against future consolidated taxable income.
(True/False)
4.9/5 (87)
(87) ParentCo purchased all of the stock of ChildCo on January 2, year 2, and the two companies filed consolidated returns for year 2 and thereafter. Both entities were incorporated in year 1. Taxable income computations for the members include the following. Neither group member incurred any capital gain or loss transactions during these years, nor did they make any charitable contributions. No § 382 limit applies. 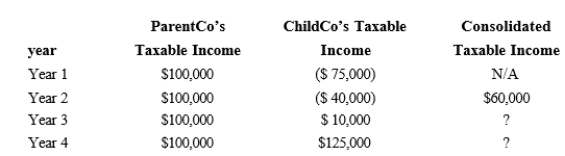 To what extent can ChildCo's year 1 losses be used by the group in year 4?
 (Multiple Choice)
5.0/5 (81)
(81) ParentCo owned 100% of SubCo for the entire year, and both companies use the accrual method of tax accounting. During the year, SubCo purchased $20,000 of supplies from ParentCo. In addition, SubCo provided internal audit services to ParentCo, which were worth $40,000. Including these transactions, ParentCo's separate taxable income was $75,000, and SubCo's separate taxable income was $100,000. What is the group's consolidated taxable income for the year?
(Multiple Choice)
4.9/5 (76)
(76) Cooper Corporation joined the Duck consolidated Federal income tax return group when Cooper held a $1 million NOL carryforward. In its first year as a part of the Duck group, Cooper generated a $150,000 operating profit. For that year, Duck can deduct only $150,000 of Cooper's NOL in computing consolidated taxable income.
(True/False)
4.7/5 (83)
(83) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
-Member's operating loss.
(Multiple Choice)
4.9/5 (78)
(78) Which of the following is not a requirement that must be met before a group files a consolidated return?
(Multiple Choice)
4.9/5 (81)
(81) All affiliates joining in a newly formed consolidated return must consent to the election on Form 1122, as attached to the Form 1120 for the group.
(True/False)
4.8/5 (72)
(72) With the filing of its first consolidated return, the parent corporation of a Federal consolidated group makes an irrevocable election as to how the group will allocate a tax year's income tax liability among the group members.
(True/False)
4.8/5 (70)
(70) ParentCo and SubCo report the following items of income and deduction for the current year. 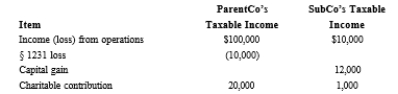 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.8/5 (80)
(80) In terms of the consolidated return rules, the Radcliffe Charitable Foundation is an)
entity.
(Short Answer)
4.8/5 (71)
(71) The starting point in computing consolidated taxable income is the sum of the separate Federal taxable income amounts of the affiliated group members.
(True/False)
4.9/5 (69)
(69) Match each of the following terms with the appropriate description in the context of a consolidated Federal income tax return.
-Choice of tax year-ends by affiliates.
(Multiple Choice)
4.9/5 (70)
(70) The treatment of group items on a Federal consolidated corporate income tax return always, sometimes, never) results in a reduction of consolidated taxable income.
(Short Answer)
5.0/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)