



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law92 Questions
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities65 Questions
Exam 3: Corporations: Introduction and Operating Rules105 Questions
Exam 4: Corporations: Organization and Capital Structure108 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions129 Questions
Exam 6: Corporations: Redemptions and Liquidations117 Questions
Exam 7: Corporations: Reorganizations139 Questions
Exam 8: Consolidated Tax Returns154 Questions
Exam 9: Taxation of International Transactions128 Questions
Exam 10: Partnerships: Formation, Operations, and Basis163 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations164 Questions
Exam 12: S Corporations121 Questions
Exam 13: Comparative Forms of Doing Business113 Questions
Exam 14: Taxes on the Financial Statements71 Questions
Exam 15: Exempt Entities129 Questions
Exam 16: Multistate Corporate Taxation184 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes145 Questions
Exam 19: Family Tax Planning118 Questions
Exam 20: Income Taxation of Trusts and Estates166 Questions
Select questions type


Which of the following statements is true with regard to intercompany transactions?
(Multiple Choice)
4.7/5  (73)
(73) Describe the general computational method used by a Federal consolidated group in computing taxable income.
(Essay)
4.7/5 (80)
(80) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
-Increase in affiliate's E & P.
(Multiple Choice)
4.8/5 (70)
(70) ParentCo owns all of the stock of both SubOne and SubTwo. List three "intercompany transactions" that might occur among the three members of the consolidated filing group.
(Essay)
4.8/5 (76)
(76) The consolidated net operating loss of the Parent Group includes all of the following except the:
(Multiple Choice)
4.8/5 (73)
(73) In computing a group's consolidated taxable income, the first step is to:
(Multiple Choice)
5.0/5 (86)
(86) JuniorCo sells an asset to SeniorCo at a realized loss. That loss is not recognized by the group in the year of the sale, because of the:
(Multiple Choice)
4.8/5 (76)
(76) An example of an intercompany transaction is the use of the trademarks of the parent corporation by a subsidiary for an arm's length licensing fee.
(True/False)
4.9/5 (87)
(87) Match each of the following terms with the appropriate description in the context of a consolidated Federal income tax return.
-Gain deferral on intercompany transactions.
(Multiple Choice)
4.8/5 (70)
(70) Each member of a consolidated group must use the same tax year-end, and all of the members must use the same tax accounting methodse.g., LIFO or FIFO).
(True/False)
4.8/5 (95)
(95) Subsidiary holds an allocated net operating loss NOL) when it leaves the Parent consolidated group. As a result:
(Multiple Choice)
4.7/5 (70)
(70) A subsidiary corporation must leave the consolidated group if it is restructured as an LLC.
(True/False)
4.8/5 (78)
(78) Deferring recognition of an intercompany gain is one advantage/disadvantage) of electing to file consolidated returns.
(Short Answer)
4.8/5 (81)
(81) The consolidated income tax return rules apply only for Federal tax purposes. Financial accounting rules can be quite different from the corresponding tax rules, but the tax professional should be familiar with both sets of requirements. Describe the major differences between the book and tax treatment for the conglomerate's reporting of:
a. The ownership levels required to consolidate.
b. Goodwill.
c. The entities included on the report.
(Essay)
4.9/5 (87)
(87) A Federal consolidated filing group aggregates its separate charitable contributions for the tax year, deductions for which are then subject to an annual limitation of 10% of consolidated taxable income.
(True/False)
4.9/5 (74)
(74) ParentCo and SubCo report the following items of income and deduction for the current year. 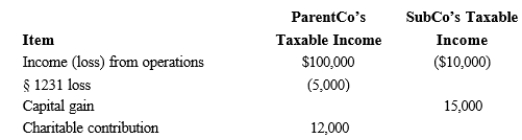 Compute ParentCo and SubCo's consolidated taxable income or loss.
 (Multiple Choice)
4.9/5 (75)
(75) Forming a Federal consolidated tax return group is a discretionary action by eligible affiliates. List several tax attributes and situations that might make a subsidiary an attractive partner for a parent corporation on a consolidated return.
(Essay)
4.9/5 (84)
(84) How must the IRS collect the liability for Federal taxes from among a consolidated group?
(Multiple Choice)
4.7/5 (72)
(72) Consolidated estimated tax payments must begin for the first, second, etc.) tax year after the group's election.
(Short Answer)
4.9/5 (88)
(88) All members of an affiliated group have and liability for each other's Federal income tax liabilities.
(Short Answer)
4.9/5 (90)
(90) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)