



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law92 Questions
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities65 Questions
Exam 3: Corporations: Introduction and Operating Rules105 Questions
Exam 4: Corporations: Organization and Capital Structure108 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions129 Questions
Exam 6: Corporations: Redemptions and Liquidations117 Questions
Exam 7: Corporations: Reorganizations139 Questions
Exam 8: Consolidated Tax Returns154 Questions
Exam 9: Taxation of International Transactions128 Questions
Exam 10: Partnerships: Formation, Operations, and Basis163 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations164 Questions
Exam 12: S Corporations121 Questions
Exam 13: Comparative Forms of Doing Business113 Questions
Exam 14: Taxes on the Financial Statements71 Questions
Exam 15: Exempt Entities129 Questions
Exam 16: Multistate Corporate Taxation184 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes145 Questions
Exam 19: Family Tax Planning118 Questions
Exam 20: Income Taxation of Trusts and Estates166 Questions
Select questions type


The consolidated return rules combine the members' transactions involving items
e.g., §
1231 gain/loss) when computing consolidated taxable income.
(Short Answer)
4.9/5  (79)
(79) List some of the nontax reasons that groups of corporations form conglomerates and may be eligible also to file consolidated Federal income tax returns.
(Essay)
4.9/5 (78)
(78) Calendar year ParentCo purchased all of the stock of SubCo on January 1, year 1, for $500,000. In year 1, SubCo produced a loss of $150,000 and distributed cash of $25,000 to ParentCo. In year 2, SubCo generated a loss of $450,000; in year 3, it recognized net income of $90,000. What is ParentCo's capital gain or loss) if it sells all of its
SubCo stock to a nongroup member on year 4 for $150,000?
(Multiple Choice)
4.9/5 (81)
(81) Match each of the following items with the appropriate description, indicating whether the item's treatment for financial accounting and Federal income tax purposes is the same or not.
-Joining the consolidated group is mandatory if ownership requirements are met by the entities.
(Multiple Choice)
4.7/5 (74)
(74) ParentCo owned 100% of SubCo for the entire year. ParentCo uses the accrual method of tax accounting whereas SubCo uses the cash method. During the year, SubCo sold raw materials to ParentCo for $35,000 under a contract that requires no payment to SubCo until the following year. Exclusive of this transaction, ParentCo had income for the year of $30,000, and SubCo had income of $50,000. The group's consolidated taxable income for the year was:
(Multiple Choice)
4.8/5 (72)
(72) The calendar year parent and affiliates must elect to file on a consolidated basis by 15 after the first consolidated tax year.
(Essay)
4.9/5 (89)
(89) A joint venture subject to income tax laws like a partnership can join in a consolidated Federal income tax return.
(True/False)
4.9/5 (76)
(76) One of the motivations for the consolidated return rules is to discourage conglomerates from trafficking in the deductible of other entities.
(Short Answer)
4.8/5 (93)
(93) Conformity among the members of a consolidated group must be implemented for which of the following tax items?
(Multiple Choice)
4.7/5 (71)
(71) Most of the rules governing the use of consolidated returns are found in tax
____________________ Code/Regulations), and not the ____________________ Code/Regulations).
(Short Answer)
4.8/5 (79)
(79) If subsidiary stock is redeemed or sold outside the group when an excess loss account exists, the selling parent corporation recognizes ordinary income equal to the account balance.
(True/False)
4.9/5 (85)
(85) Which of the following entities is eligible to file Federal income tax returns on a consolidated basis?
(Multiple Choice)
4.8/5 (80)
(80) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
-Member's operating gains/profits.
(Multiple Choice)
4.9/5 (77)
(77) Which of the following items is not computed on a group basis for a Federal consolidated income tax return?
(Multiple Choice)
5.0/5 (82)
(82) The rules for computing Federal consolidated taxable income are some of the most complex in the tax law.
(True/False)
4.8/5 (93)
(93) In the current year, Parent Corporation provided advertising services to its 100% owned subsidiary, SubCo, under a
contract that requires no payments to Parent until next year. Both parties use the accrual method of tax accounting and a calendar tax year. The services that Parent rendered were valued at $250,000. In addition, Parent received
$20,000 of interest payments from SubCo. relative to an arm's length note between them.
Including these transactions, Parent's taxable income for the year amounted to $400,000. SubCo reported $200,000 separate taxable income. Derive the group's consolidated taxable income using the format of Exhibit 8.3. 
(Essay)
4.7/5 (83)
(83) For each of the indicated tax years, compute consolidated taxable income for the calendar year Holloway Group, which elected consolidated status immediately upon creation of the two member corporations in January year 1. All recognized income related to the data processing services of the firms. No intercompany transactions were completed during the indicated years. Tax Year Holloway Corporation Olson Corporation Year 1 \ 250,000 (\ 70,000) Year 2 250,000 (120,000) Year 3 250,000 (180,000) Year 4 250,000 110,000
(Essay)
4.7/5 (88)
(88) Parent's basis in the stock of Child, its subsidiary, is $1 million at the beginning of the year. Child's share of consolidated taxable income this year is a $1.25 million operating loss. Parent's basis in the Child stock now is zero. Explain.
(Essay)
4.9/5 (78)
(78) LargeCo files on a consolidated basis with LittleCo. The subsidiary was acquired for $400,000 on January 1, year 1, and it paid a $75,000 dividend to LargeCo at the end of both year 2 and year 3.
a. Given the following information about the subsidiary's operating results, derive the requested amounts as of
December 31 of each year. The group files using a calendar year.
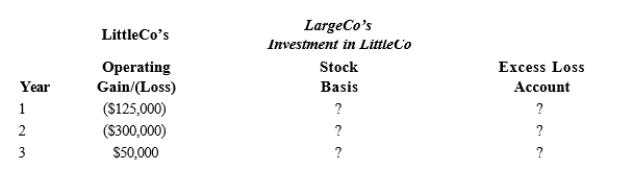 b. LargeCo sold LittleCo to an unrelated competitor for $600,000 on December 31, year 3. How will LargeCo account for this sale?
 (Essay)
4.9/5 (81)
(81) Most of the Federal consolidated income tax return rules are found in detailed sections of the tax Regulations.
(True/False)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)