



 Chat with AI
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities


Tanuja Singh is a CPA and operates her own accounting firm Singh CPA, LLC). As a single-member LLC, she reports her accounting firm operations as a sole proprietor. Tanuja has QBI from her accounting firm of $540,000, reports W-2 wages of $156,000, and the unadjusted basis of property used in the LLC is $425,000. Tanuja is married and will file a joint tax return with her spouse. Their taxable income before the QBI deduction is $475,000, and their modified taxable income is $448,000. What is Tanuja's QBI deduction for 2019.

 (86)
 Verified
A
Alicia is the sole shareholder and CEO of ABC, Inc., an S corporation that is a qualified trade or business. During the current year, ABC has net income of $325,000 after deducting Alicia's $100,000 salary. In addition to her compensation, ABC pays Alicia dividends of $250,000. After reviewing comparable companies, you determine that reasonable compensation for someone with her experience and responsibilities is $200,000. What is Alicia's qualified business income?
(87) VerifiedC
Felicia, who is single, operates three sole proprietorships that generate the following information in 2019 none is a
"specified services" businesses): Business QBI W-2 Wages Capital Investment A \ 240,000 \ 72,000 \ -0- B \ (108,000) \ 48,000 \ -0- C \ 120,000 \ -0- \ -0- Felcia chooses not to aggregate the businesses. She also earns $150,000 of wages from an unrelated business and modified taxable income before any QBI deduction) is $304,000.
a. What is Felicia's QBI deduction?
b. Assume that Felicia can aggregate these businesses. Determine her QBI deduction if she decides to aggreg the businesses.
(79) Verified a. Under Prop. Reg. § 1.199A-1d), Felicia must allocate Business B's negative QBI t Business A and Business C in proportion to their positive QBI amounts $240,000 for Business A; $120,000 for Business C). As a result, the negative QBI from Business C apportioned 66.66% to Business A and 33.33% to Business C. So $72,000) is apportioned to Business A and $36,000) to Business C.
Felicia now applies the "W-2 Wages" limitation by determining the lesser of 20% of QBI
50% of W-2 wages for each business. Felicia's "combined qualified business income amount" is $33,600 $33,600 + $-0- + $
). Because this amount is less than 20% of Felicia's modified taxable income $60,800;
$304,000 x 20%), Felicia's QBI deduction is $33,600 and her taxable income is $270,400. There is no carryover of any loss into the following taxable year for purposes of § 199A Business B negative QBI was completely used).
b. Because Felicia's taxable income is above the threshold amount, her QBI deduction subject to the W-2 wages and capital investment limitations. Because the businesses a aggregated, these limitations are applied on an aggregated basis. None of the businesses own "qualified property." As a result, only the "W-2 Wages"
limitation applies. Felicia's "combined qualified income amount" is $50,400, the lesser
20% of the QBI from the aggregated businesses $50,400; $252,000 x 20%), or 50% W-2 wages from the aggregated businesses $60,000; $120,000 x 50%).
Felicia's QBI deduction is equal to the lesser of $50,400 or 20% of her modified taxa income $60,800; $304,000 x 20%). As a result, Felicia's QBI deduction is $50,400, her taxable income is $253,600. By aggregating her businesses, Felicia has increased size of her QBI deduction.
Describe the limitations on the qualified business income deduction that apply to high income taxpayers.
(83) The corporate marginal income tax rate is lower than the top individual tax rate.
(79) Which of the following statements is incorrect about LLCs and the check-the-box Regulations?
(88) A partnership will need to report wages paid to its employees as a separate line item on Schedule K-1 to help partners calculate their QBI deduction.
(75) Compare the basic tax and nontax factors of doing business as a partnership, an S corporation, and a C
corporation. Circle the correct answers. 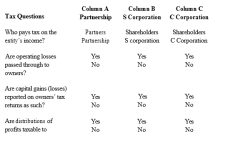 owners?
 (88) Employment taxes apply to all entity forms of operating a business. As a result, employment taxes are a neutral factor in selecting the most tax effective form of operating a business.
(67) A qualified trade or business includes any trade or business including providing services as an employee.
(87) Thrush Corporation files its Form 1120, which reports taxable income of $200,000 in the current year. The corporation's tax is $42,000.
(74) Jason and Paula are married. They file a joint return for 2019 on which they report taxable income before the QBI deduction of $200,000. Jason operates a sole proprietorship, and Paula is a partner in the PQRS Partnership. Both are a qualified trade or business and neither is a specified services business. Jason's sole proprietorship reports $150,000 of net income, W-2 wages of $45,000, and has qualified property of $50,000. Paula's partnership reports a loss for the year, and her allocable share of the loss is $40,000. The partnership reports no W-2 wages and Paula's share of the partnership's qualified property is $20,000. What is their qualified business income deduction for the year?
(94) Luis is the sole shareholder of a regular C corporation, and Eduardo owns a proprietorship. In the current year, both businesses make a profit of $80,000, and each owner withdraws $50,000 from his business. With respect to this information, which of the following statements is incorrect?
(84) What happens to the § 199A deduction if a qualified trade or business generates a loss?
(86) Matt, the sole shareholder of Pastel Corporation a C corporation), has the corporation pay him a salary of $600,000 in the current year. The Tax Court has held that $200,000 represents unreasonable compensation. Matt must report a salary of $400,000 and a dividend of $200,000 on his individual tax return.
(77) Carol and Candace are equal partners in Peach Partnership. In the current year, Peach had a net profit of $75,000 $250,000 gross income - $175,000 operating expenses) and distributed $25,000 to each partner. Peach must pay tax on $75,000 of income.
(75) The qualified business income deduction is severely limited for specified services businesses. What is a specified serv trade or business?
(96) Quail Corporation is a C corporation that generates net income of $125,000 during the current year. If Quail paid dividends of $25,000 to its shareholders, the corporation must pay tax on $100,000 of net income. Shareholders must report the $25,000 of dividends as income.
(94) Rajib is the sole shareholder of Cardinal Corporation, a calendar year S corporation. In the current year, Cardinal generated a net profit of $350,000 $520,000 gross income - $170,000 operating expenses) and distributed $80,000 to Rajib. Rajib must report the Cardinal Corporation profit of $350,000 on his Federal income tax return.
(75) Tammy has $200,000 of QBI from her neighborhood clothing store a sole proprietorship). Her proprietorship paid $30,000 in W-2 wages and has $20,000 of qualified property.Tammy's spouse earned $50,000 of wages as an employee, and the couple earned $20,000 of interest income during the year and will be filing jointly.What is their QBI deduction for 2019?
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)