



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law92 Questions
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities65 Questions
Exam 3: Corporations: Introduction and Operating Rules105 Questions
Exam 4: Corporations: Organization and Capital Structure108 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions129 Questions
Exam 6: Corporations: Redemptions and Liquidations117 Questions
Exam 7: Corporations: Reorganizations139 Questions
Exam 8: Consolidated Tax Returns154 Questions
Exam 9: Taxation of International Transactions128 Questions
Exam 10: Partnerships: Formation, Operations, and Basis163 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations164 Questions
Exam 12: S Corporations121 Questions
Exam 13: Comparative Forms of Doing Business113 Questions
Exam 14: Taxes on the Financial Statements71 Questions
Exam 15: Exempt Entities129 Questions
Exam 16: Multistate Corporate Taxation184 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes145 Questions
Exam 19: Family Tax Planning118 Questions
Exam 20: Income Taxation of Trusts and Estates166 Questions
Select questions type


How are the members of a Federal consolidated group affected by computations related to E & P?

Free
(Multiple Choice)
4.8/5  (90)
(90) Correct Answer: Verified
A
ParentCo and SubCo report the following items of income and deduction for the current year. ParentCo's SubCo's Taxable Item Taxable Income Income Income loss) from operations $100,000 $10,000)
§ 1231 loss 5,000)
Capital gain 15,000
Charitable contribution 12,000
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis. Then compute the total of those amounts if appropriate. 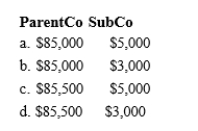
Free
(Short Answer)
4.9/5 (76)
(76) Correct Answer:Verified
VerifiedC
Generally, when a subsidiary leaves an ongoing consolidated group, it must wait years before it again can reenter the parent's consolidated group.
Free
(Short Answer)
4.8/5 (87)
(87) Correct Answer:Verified
Verifiedfive
5
SubCo sells an asset to ParentCo at a realized gain. While ParentCo still holds the asset, SubCo leaves the consolidated group. As a result:
(Multiple Choice)
4.8/5 (86)
(86) Outline the major advantages and disadvantages of filing Federal corporate income tax returns on a consolidated basis. Limit your comments to the income tax effects of the election.
(Essay)
4.8/5 (90)
(90) After a takeover, the parent's balance sheet shows a fair market value cost basis in the subsidiary for both book and tax purposes.
(True/False)
4.7/5 (76)
(76) ParentCo's separate taxable income was $200,000, and JuniorCo's was $50,000. Consolidated taxable income before contributions was $200,000. Charitable contributions made by the affiliated group included $5,000 by ParentCo and $1,000 by JuniorCo. Compute the group's maximum charitable contribution deduction.
(Multiple Choice)
4.7/5 (63)
(63) Consolidated group members each are jointly and severally liable for the entire consolidated Federal income tax liability.
(True/False)
4.8/5 (80)
(80) The rules can limit the net operating loss deduction claimed on a Federal consolidated return.
(Essay)
4.9/5 (77)
(77) Within a Federal consolidated income tax group, SubOne can/cannot) use the LIFO
inventory method at the same time that SubTwo uses the FIFO method.
(Short Answer)
4.8/5 (81)
(81) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
-Net operating loss.
(Multiple Choice)
4.9/5 (88)
(88) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
-Compensation deductions.
(Multiple Choice)
4.7/5 (89)
(89) In computing consolidated E & P, a negative adjustment is allowed for the group's disallowed entertainment expenditures.
(True/False)
4.9/5 (82)
(82) When a corporate group elects to file Federal income tax returns on a consolidated basis, it is subject to several tax return filing requirements for its first and subsequent tax years. List the most important of those requirements.
(Essay)
4.9/5 (81)
(81) The consolidated tax return regulations use "SRLY" limitations with respect to losses of a subsidiary that can be deducted on the consolidated return. Describe the various SRLY rules that might apply to a consolidated group member's losses.
(Essay)
4.9/5 (88)
(88) In computing consolidated taxable income, capital gains and losses are removed from the taxable incomes of the group members and determined on a group basis.
(True/False)
4.7/5 (82)
(82) In computing consolidated taxable income, the purchase at a realized gain of a depreciable asset by Subsidiary from
Parent is an example of an) transaction.
(Short Answer)
4.9/5 (82)
(82) A Federal consolidated group reported the following taxable income amounts. Parent owns all of the stock of both Junior and Minor. Determine the net operating loss NOL) that is apportioned to Parent.
(Multiple Choice)
4.7/5 (97)
(97) Discuss how a parent corporation computes its stock basis for a subsidiary that joins in a Federal consolidated income tax return.
(Essay)
4.9/5 (91)
(91) The consolidated return rules are designed to allow a tax-neutral means by which to elect to file on a consolidated basis.
(True/False)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)