



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law92 Questions
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities65 Questions
Exam 3: Corporations: Introduction and Operating Rules105 Questions
Exam 4: Corporations: Organization and Capital Structure108 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions129 Questions
Exam 6: Corporations: Redemptions and Liquidations117 Questions
Exam 7: Corporations: Reorganizations139 Questions
Exam 8: Consolidated Tax Returns154 Questions
Exam 9: Taxation of International Transactions128 Questions
Exam 10: Partnerships: Formation, Operations, and Basis163 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations164 Questions
Exam 12: S Corporations121 Questions
Exam 13: Comparative Forms of Doing Business113 Questions
Exam 14: Taxes on the Financial Statements71 Questions
Exam 15: Exempt Entities129 Questions
Exam 16: Multistate Corporate Taxation184 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes145 Questions
Exam 19: Family Tax Planning118 Questions
Exam 20: Income Taxation of Trusts and Estates166 Questions
Select questions type


Business reasons, and not tax incentives, constitute the primary motivation for most corporations to form a conglomerate and file tax and financial accounting reports on a consolidated basis.
(True/False)
4.8/5  (79)
(79) For each of the indicated tax years. compute consolidated taxable income for the calendar year Whitman Group, which elected consolidated status immediately upon creation of the two member corporations in January year 1. All recognized income related to the data processing services of the firms. No intercompany transactions were completed during the indicated years. Tax Year Whitman Corporation Draper Corporation Year 1 \ 250,000 \ 90,000 Year 2 250,000 (170,000) Year 3 250,000 (560,000) Year 4 250,000 145,000
(Essay)
4.8/5 (77)
(77) Certain business entities are ineligible to join an affiliated group and file a consolidated Federal income tax return.
List three or more entities that cannot be part of a Federal consolidated tax return group.
(Essay)
4.8/5 (77)
(77) When a subsidiary sells to the parent some business-use property that has appreciated from its $20,000 basis to a
$50,000 fair market value, the subsidiary immediately recognizes $30,000 ordinary income on the consolidated return.
(True/False)
4.8/5 (79)
(79) Which of the following potentially is a disadvantage of electing to file a Federal consolidated corporate income tax return?
(Multiple Choice)
4.8/5 (85)
(85) Giant Ltd. owns 100% of the stock of Middle Corporation. Bottom Corp is owned 60% by Giant and 40% by Middle.
Giant's Federal consolidated income tax return includes both Middle and Bottom.
(True/False)
4.9/5 (84)
(84) Match each of the following items with the appropriate description, indicating whether the item's treatment for financial accounting and Federal income tax purposes is the same or not.
-Parent owns 100% of a U.S. partnership and wants the entity to join the consolidated group.
(Multiple Choice)
4.9/5 (64)
(64) The Parent consolidated group reports the following results for the tax year. Determine each member's share of the consolidated tax liability, assuming that the members all have consented to use the relative tax liability tax-sharing method. Dollar amounts are listed in millions, and a 21% income tax rate applies to all of the entities. Parent SubOne SubTwo SubThree Consolidated Ordinary income \ 600 \ 200 \ 60 (\ 30) \ 830 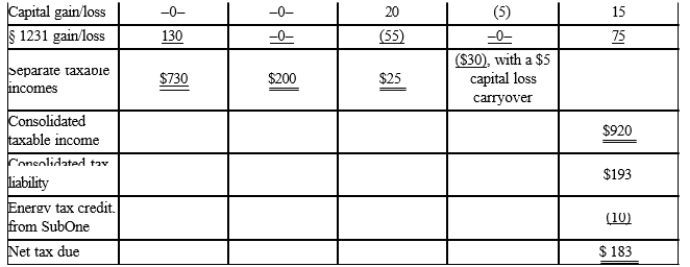
(Essay)
4.8/5 (82)
(82) A parent-subsidiary controlled group exists where there is percent ownership of all of the affiliates within the group, and there is an identifiable corporation.
(Short Answer)
4.9/5 (69)
(69) Calendar year Parent Corporation acquired all of the stock of SubCo on January 1, year 1, for $500,000. The subsidiary's operating gains and losses are shown below. In addition, a $50,000 dividend is paid early in year 2.
Complete the following chart, indicating the appropriate stock basis and excess loss account amounts. Year Operating Gain/Loss Stock Basis Excess Loss Account 1 (\ 100,000) ? ? 2 (\ 150,000) ? ? 3 \ 300,000 ? ?
(Essay)
4.8/5 (77)
(77) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
-Charitable contributions.
(Multiple Choice)
4.8/5 (68)
(68) In computing consolidated E & P, dividends paid to the parent by group members are subtracted.
(True/False)
4.7/5 (72)
(72) Cooper Corporation joined the Duck consolidated Federal income tax return group when Cooper held a $1 million NOL carryforward. In its first year as a part of the Duck group, Cooper generated a $150,000 taxable loss. For that year, Duck cannot deduct any of Cooper's NOL in computing consolidated taxable income.
(True/False)
4.7/5 (83)
(83) ParentCo and SubCo report the following items of income and deduction for the current year. 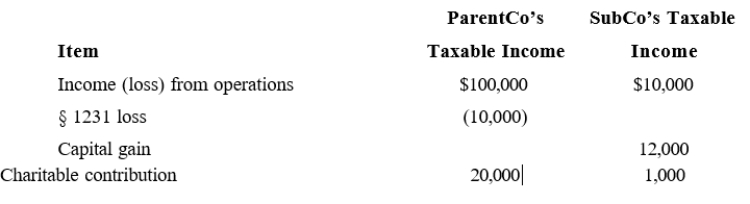 Compute ParentCo and SubCo's taxable income or loss computed on a separate basis.
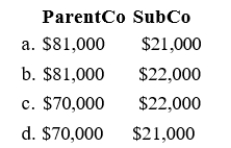
Compute ParentCo and SubCo's taxable income or loss computed on a separate basis. (Short Answer)
4.9/5 (80)
(80) Match each of the following terms with the appropriate description in the context of a consolidated Federal income tax return.
-Offsetting gains against other members' losses.
(Multiple Choice)
4.8/5 (81)
(81) Which of the following potentially is a disadvantage of electing to file a Federal corporate income tax consolidated return?
(Multiple Choice)
4.9/5 (84)
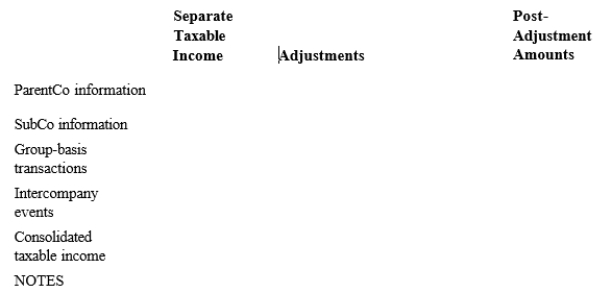
(84) Parent Corporation's current-year taxable income included $100,000 net profit from operations and a $30,000 net long-term capital gain. Parent also made a $22,000 contribution to State University. SubCo produced $85,000 of income from operations and incurred a $25,000 net short-term capital loss.
Use the computational worksheet of Exhibit 8.3 to derive the group members' separate taxable incomes and the group's consolidated taxable income.
(Essay)
4.9/5 (80)
(80) A tax-exempt charitable trust created by a U.S. C corporation can join in a Federal consolidated return.
(True/False)
4.9/5 (71)
(71) When negative adjustments are made to the stock basis of the subsidiary that exceed the basis as of the beginning of the tax year, an) account is created rather than giving the parent a negative tax basis in the stock.
(Short Answer)
4.7/5 (76)
(76) The calendar year Sterling Group files its Federal corporate income tax return on a consolidated basis. The group's
Form 1120 is due on April 15, or October 15 if an extended due date is approved by the IRS.
(True/False)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)