



 Chat with AI
Exam 8: Consolidated Tax Returns

Exam 1: Understanding and Working With the Federal Tax Law92 Questions
Exam 2: The Deduction for Qualified Business Income for Pass-Through Entities65 Questions
Exam 3: Corporations: Introduction and Operating Rules105 Questions
Exam 4: Corporations: Organization and Capital Structure108 Questions
Exam 5: Corporations: Earnings and Profits and Dividend Distributions129 Questions
Exam 6: Corporations: Redemptions and Liquidations117 Questions
Exam 7: Corporations: Reorganizations139 Questions
Exam 8: Consolidated Tax Returns154 Questions
Exam 9: Taxation of International Transactions128 Questions
Exam 10: Partnerships: Formation, Operations, and Basis163 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations164 Questions
Exam 12: S Corporations121 Questions
Exam 13: Comparative Forms of Doing Business113 Questions
Exam 14: Taxes on the Financial Statements71 Questions
Exam 15: Exempt Entities129 Questions
Exam 16: Multistate Corporate Taxation184 Questions
Exam 17: Tax Practice and Ethics174 Questions
Exam 18: The Federal Gift and Estate Taxes145 Questions
Exam 19: Family Tax Planning118 Questions
Exam 20: Income Taxation of Trusts and Estates166 Questions
Select questions type


When the net accumulated taxable losses of a subsidiary exceed the parent's acquisition price, the parent's basis in the subsidiary's stock becomes negative.
(True/False)
4.9/5  (72)
(72) Azure Corporation joins the Colorful Corporation Federal consolidated return group. As a result:
(Multiple Choice)
4.9/5 (96)
(96) Match each of the following items with the appropriate description, indicating whether the item is computed on a group basis on a consolidated tax return.
-Interest income from Detroit School District bonds.
(Multiple Choice)
4.9/5 (97)
(97) Dividends paid out of a subsidiary's E & P to the parent cause a positive/negative)
adjustment to the parent's stock basis of the subsidiary.
(Short Answer)
4.8/5 (85)
(85) The Nanie consolidated group reported the following taxable income amounts. Parent owns all of the stock of both Junior and Minor. Determine the net operating loss NOL) that is apportioned to Minor.
Parent (\ 400,000) Junior (\ 600,000) Minor \ 100,000
(Multiple Choice)
4.7/5 (92)
(92) ParentCo, SubOne, and SubTwo have filed consolidated returns since year 2. All of the entities were incorporated in Taxable income computations for the members include the following. None of the group members incurred any capita transactions during these years, nor did they make any charitable contributions. Year ParentCo's Taxable Income SubOne's Taxable Income SubTwo's Taxable Income Consolidated Taxable Income Year 1 \ 200,000 \ 50,000 \ 150,000 N/A Year 2 \ 200,000 (\ 60,000) \ 70,000 \ 210,000 Year 3 \ 20,000 (\ 60,000) (\ 40,000) ? Year 4 \ 200,000 \ 130,000 \ 10,000 ? How should the Year 3 consolidated net operating loss be apportioned among the group members? 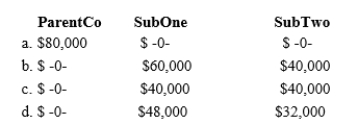
(Short Answer)
4.8/5 (87)
(87) The right to file on a consolidated basis is available to a group of corporations when they constitute a "parent- subsidiary affiliated group."
(True/False)
4.9/5 (83)
(83) If, on joining an affiliated group, SubCo has a different tax year than that of ParentCo, SubCo must switch its year- end to ParentCo's by the end of the first, second, etc.) tax year after the election to consolidate.
(Short Answer)
4.8/5 (83)
(83) ParentCo's separate taxable income was $200,000, and SubCo's was $50,000. Consolidated taxable income before contributions was $200,000. Charitable contributions made by the affiliated group included $60,000 by ParentCo and $10,000 by SubCo. Compute the group's maximum charitable contribution deduction.
(Multiple Choice)
4.9/5 (69)
(69) Calendar year ParentCo acquired all of the stock of SubCo on January 1, year 1, for $1,000,000. The parties immediately elected to file consolidated income tax returns. SubCo generated taxable income of $250,000 for year 1 and paid a dividend of $100,000 to ParentCo. In year 2, SubCo generated an operating loss of $350,000, and in year 3, it produced taxable income of $750,000. As of the last day of year 3, what was ParentCo's basis in the stock of
SubCo?
(Multiple Choice)
4.7/5 (79)
(79) A calendar year parent corporation wants to file its tax returns on a consolidated basis with its affiliates. The group's election to file consolidated Federal corporate income tax returns must be made by the extended due date of the first return on which the consolidation is applied i.e., October 15).
(True/False)
4.9/5 (89)
(89) ParentCo purchased all of the stock of ChildCo on January 2, year 2, and the two companies filed consolidated returns for that year and thereafter. Both entities were incorporated in year 1. Taxable income computations for the members include the following. Neither group member incurred any capital gain or loss transactions during these years, nor did either member make any charitable contributions. No § 382 limit applies. Year ParentCo's Taxable Income ChildCo's Taxable Income Consolidated Taxable Income Year 1 \ 10,000 (\ 95,000) N/A Year 2 \ 10,000 \ 50,000 ? Year 3 (\ 25,000) \ 40,000 ? Year 4 \ 10,000 \ 10,000 ? To what extent are ChildCo's year 1 losses used by the group in year 2-year 4?
(Multiple Choice)
5.0/5 (92)
(92) When a consolidated NOL is generated, each affiliate is allocated a share of the loss.
(True/False)
4.8/5 (68)
(68) When an affiliated group elects to file Federal consolidated income tax returns, it gives up the ability to claim a
deduction for distributions of profits paid to other members.
(Short Answer)
4.8/5 (83)
(83) Match each of the following items with the appropriate description, indicating whether the item increases or decreases the parent's basis in the stock of a subsidiary.
-Member's capital gain.
(Multiple Choice)
4.9/5 (82)
(82) A Federal consolidated tax return group can apply the "relative taxable income" method as a means to apportion the tax liabilities of the members among the affiliates.
(True/False)
5.0/5 (78)
(78) A limited partnership can join the parent's consolidated group for book and for tax purposes.
(True/False)
4.8/5 (79)
(79) ParentCo and SubCo recorded the following items of income and deduction for the current tax year. Item ParentCo's Taxable Income SubCo's Taxable Income Income (loss) from operations \ 100,000 \ 20,000 \S1231 loss (8,000) Capital gain (loss) (10,000) 14,000 Charitable contribution 20,000 1,000 Compute ParentCo and SubCo's consolidated taxable income or loss.
(Multiple Choice)
4.8/5 (84)
(84) Keep Corporation joined an affiliated group by merger in 2010. The group generated a 2018 consolidated NOL, and Keep's share of the loss was $50,000. Keep's share of the loss is included in the group's NOL carryforward to 2019.
(True/False)
4.8/5 (70)
(70) Match each of the following terms with the appropriate description in the context of a consolidated Federal income tax return.
-Tax compliance deadlines and recordkeeping.
(Multiple Choice)
4.9/5 (63)
(63) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)