



 Chat with AI
Exam 22: Perfect Competition

Exam 1: What Economics Is About174 Questions
Exam 2: Production Possibilities Frontier Framework156 Questions
Exam 3: Supply and Demand Theory224 Questions
Exam 4: Prices Free Controlled and Relative122 Questions
Exam 5: Supply Demand and Price Applications76 Questions
Exam 6: Macroeconomic Measurements Part I Prices and Unemployment151 Questions
Exam 7: Macroeconomic Measurements Part II Gdp and Real Gdp150 Questions
Exam 8: Aggregate Demand and Aggregate Supply204 Questions
Exam 9: Classical Macroeconomics and the Self Regulating Economy172 Questions
Exam 10: Keynesian Macroeconomics and Economic Instability a Critique of the Self Regulating Economy200 Questions
Exam 11: Fiscal Policy and the Federal Budget167 Questions
Exam 12: Money Banking and the Financial System150 Questions
Exam 13: The Federal Reserve System180 Questions
Exam 14: Money and the Economy150 Questions
Exam 15: Monetary Policy185 Questions
Exam 16: Expectations Theory and the Economy150 Questions
Exam 17: Economic Growth Resources Technology Ideas and Institutions103 Questions
Exam 18: Debates in Macroeconomics Over the Role and Effects of Government100 Questions
Exam 19: Elasticity204 Questions
Exam 20: Consumer Choice and Behavioral Economics179 Questions
Exam 21: Production and Costs245 Questions
Exam 22: Perfect Competition187 Questions
Exam 23: Monopoly195 Questions
Exam 24: Monopolistic Competition Oligopoly and Game Theory172 Questions
Exam 25: Government and Product Markets Antitrust and Regulation158 Questions
Exam 26: Factor Markets With Emphasis on the Labor Market184 Questions
Exam 27: Wages Unions and Labor138 Questions
Exam 28: The Distribution of Income and Poverty99 Questions
Exam 29: Interest Rent and Profit198 Questions
Exam 30: Market Failure Externalities Public Goods and Asymmetric Information187 Questions
Exam 31: Public Choice and Special Interest Group Politics135 Questions
Exam 32: Building Theories to Explain Everyday Life From Observations to Questions to Theories to Predictions62 Questions
Exam 33: International Trade152 Questions
Exam 34: International Finance122 Questions
Exam 35: The Economic Case for and Against Government Five Topics Considered87 Questions
Exam 36: Stocks Bonds Futures and Options110 Questions
Select questions type


Exhibit 22-10
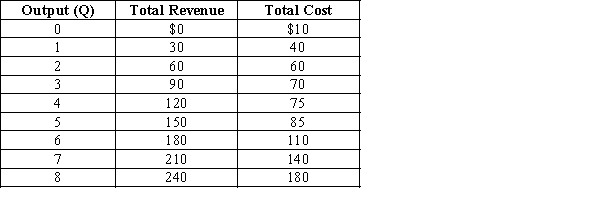
-Refer to Exhibit 22-10. What quantity of output should the profit-maximizing firm produce?
-Refer to Exhibit 22-10. What quantity of output should the profit-maximizing firm produce? (Multiple Choice)
4.7/5  (83)
(83) What is the shape of the demand curve faced by the perfectly competitive firm? Why does it have this shape?
(Essay)
4.8/5 (76)
(76) Explain the difference between resource allocative efficiency and productive efficiency.
(Essay)
4.8/5 (77)
(77) A perfectly competitive firm that maximizes profit exhibits resource allocative efficiency because it produces where price
(Multiple Choice)
4.8/5 (90)
(90) Which of the following statements about a perfectly competitive firm is necessarily false?
(Multiple Choice)
4.8/5 (89)
(89) A perfectly competitive market is initially in long-run competitive equilibrium. Then, market demand increases. As a result, existing firms in the market begin to __________. By the time all adjustments have been made, profits will __________.
(Multiple Choice)
4.9/5 (90)
(90) Equilibrium price is $19 in a perfectly competitive market. For a perfectly competitive firm, MR = MC at 120 units of output. At 120 units, ATC is $11, and AVC is $8. The best policy for this firm is to __________ in the short run. Also, this firm earns __________ of __________ if it produces and sells 120 units. Finally, the difference between total revenue and total fixed cost for this firm is __________.
(Multiple Choice)
4.8/5 (86)
(86) Consider the following data: equilibrium price = $40, quantity of output produced = 100 units, average total cost = $47, and average variable cost = $37. What should the firm do and why?
(Multiple Choice)
4.9/5 (68)
(68) If a seller is a price taker it means that the seller sells his product at the price
(Multiple Choice)
4.9/5 (69)
(69) In order for a firm to earn economic profits, price must exceed average total cost.
(True/False)
4.9/5 (73)
(73) When a perfectly competitive firm incurs losses, it follows that price
(Multiple Choice)
4.9/5 (77)
(77) Exhibit 22-4
 -Refer to Exhibit 22-4. Where can you find the lowest price that will motivate the firm to produce Q1 in the short run?
 (Multiple Choice)
4.8/5 (66)
(66) Resource allocative efficiency exists for a perfectly competitive firm because
(Multiple Choice)
4.8/5 (75)
(75) In long-run competitive equilibrium SRATC = LRATC, because if SRATC > LRATC (at the quantity of output at which MR = MC) firms would
(Multiple Choice)
4.8/5 (91)
(91) A perfectly-competitive firm produces 2,000 units of a good during some period of time. For the 2,000th unit, marginal cost is equal to marginal revenue. The difference between marginal revenue and marginal cost is greater for the first unit the firm produces than the second, and greater for the second than the third, and so on. Furthermore, marginal revenue is greater than marginal cost for every unit from the first to the 1,999th. It follows that the
(Multiple Choice)
4.9/5 (85)
(85) Exhibit 22-8
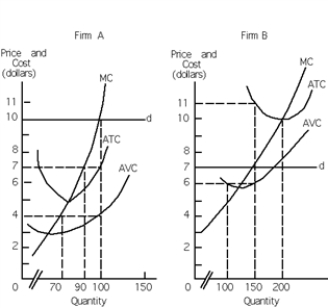 -Refer to Exhibit 22-8. What is the profit (loss) of firm A at the profit-maximizing (or loss-minimizing) level of production?
 (Multiple Choice)
4.8/5 (88)
(88) In a perfectly competitive market, the market demand curve is perfectly elastic.
(True/False)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)